 ProMapRanker
Best Wealth Management Companies in 2026

Accessible planning · Pricing starts at: See website
Key takeaways
- Fidelity, Schwab, and Vanguard suit accessible planning and retirement investors, with broad tools and lower entry points.
- Morgan Stanley, Merrill, UBS, and J.P. Morgan suit high-net-worth clients who want a dedicated adviser and private services.
- Edward Jones and Ameriprise suit people who want a local adviser relationship and regular in-person planning.
- Fees, minimums, and fiduciary status vary by service, so confirm the exact service and fee schedule before you move assets.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
| Fidelity Wealth Management | Accessible planning | See website | No | Visit |
 Charles Schwab Wealth Management | Broad tools and advice | See website | No | Visit |
 Vanguard Personal Advisor | Low cost advice | See website | No | Visit |
 Morgan Stanley Wealth Management | High-net-worth advice | See website | No | Visit |
 Merrill Wealth Management | Bank plus investing | See website | No | Visit |
 Edward Jones | Local adviser relationship | See website | No | Visit |
 UBS Wealth Management | Global private wealth | See website | No | Visit |
 Ameriprise Financial | Comprehensive planning | See website | No | Visit |
 J.P. Morgan Wealth Management | Private bank clients | See website | No | Visit |
The best wealth management companies
This is general information, not financial advice. Investing carries risk, including possible loss, and past performance does not predict future results. Wealth management fees, minimums, and services vary by firm, by service tier, and by account type, so the figures below are starting points from recent coverage, not quotes for your account. Confirm the fee schedule, minimum, and adviser model for the exact service you are considering, and check whether advice is fiduciary for that service.
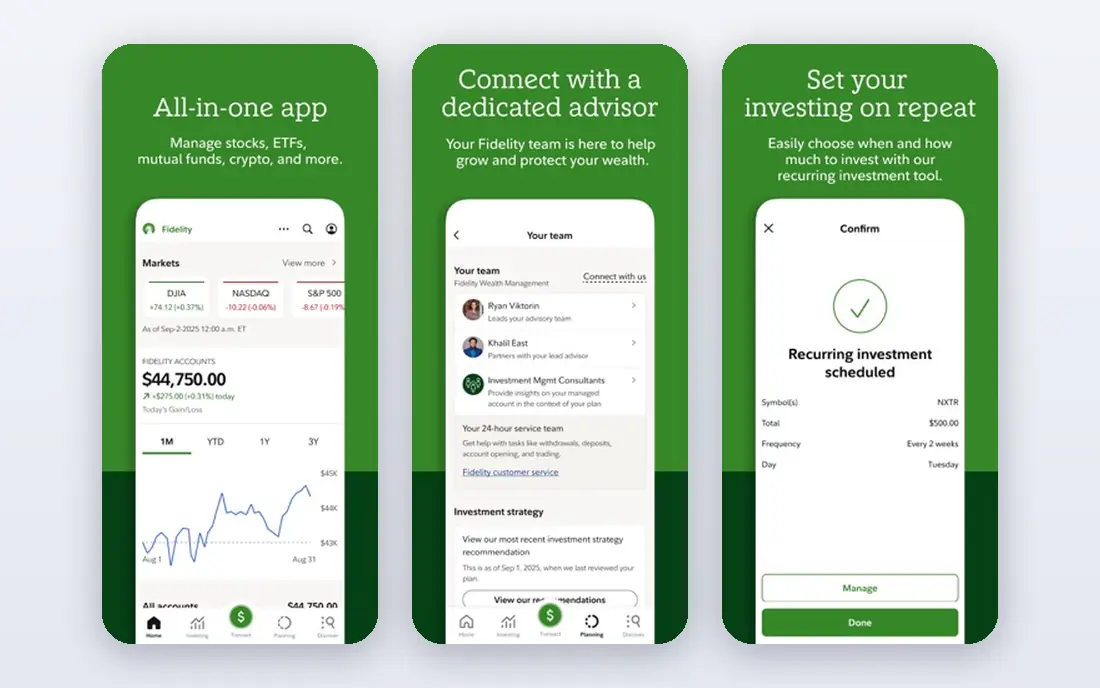
Fidelity is a strong first stop for many investors because it covers a wide range, from self-directed brokerage to digital advice and dedicated wealth management. Planning tools, retirement calculators, and educational resources are broad, and employer retirement plans often link to Fidelity accounts, which can simplify rollovers and consolidation. Recent coverage describes Fidelity Wealth Services fees in a range around 0.50 percent to 1.50 percent of assets per year depending on service, with minimums starting around $50,000 for some services.
The catch is tier confusion. Fidelity Go, Fidelity Wealth Services, and private wealth services are different products with different fees, minimums, and adviser access. A low-cost digital service will not give you the same planning depth as a dedicated adviser service. Ask which service you are being offered, what the fee covers, and whether the adviser acts as a fiduciary for that service before you move assets.
- Broad planning tools and retirement resources
- Large branch and digital presence
- Range of services from digital advice to dedicated advisers
- Fee and minimum vary sharply by service tier
- Higher-touch services cost more
- Service experience depends on the tier you choose
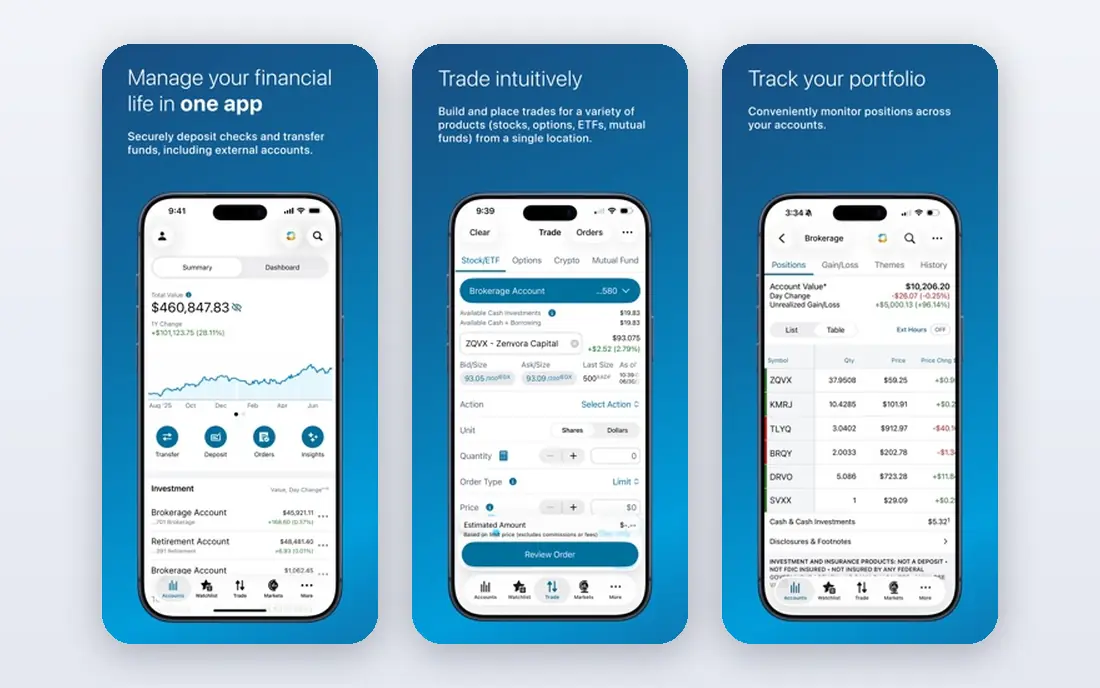
Schwab suits investors who want strong tools plus a choice of advice levels. Schwab Intelligent Portfolios offers automated investing, while Intelligent Portfolios Premium adds access to certified financial planners for a monthly fee plus a setup fee in recent coverage. Full wealth advisory services add a dedicated adviser, deeper planning, and more personal service for larger accounts.
Recent coverage lists Schwab wealth advisory fees around 0.80 percent per year for some services, though exact fees depend on assets and service. The honest limit is that the cheapest Schwab service is not the same as a dedicated adviser service. If you want a human adviser who knows your plan, confirm the service tier, the minimum, and how often you will meet. If you want low-cost automated investing, the digital service may be enough.
- Strong research, planning tools, and branch access
- Range from Intelligent Portfolios to dedicated wealth advisory
- Transparent service descriptions
- Advisory fees vary by service
- Intelligent Portfolios Premium needs a $25,000 minimum in recent coverage
- Higher-touch advice costs more
Vanguard Personal Advisor is often cited as the low-cost leader for advised investing. Recent coverage lists a fee around 0.30 percent of assets per year, with a $50,000 minimum for the main Personal Advisor service. You get a financial plan, a managed portfolio of low-cost funds, and access to human advisers, with digital tools for tracking goals and progress.
The trade-off is access and breadth. Vanguard has fewer branches than Fidelity, Schwab, or Edward Jones, and its service is more focused on investment and retirement planning than on complex estate, business, or tax services at the entry tier. For a long-term investor who wants low-cost advice and a clear plan, Vanguard is a strong pick. For a client who wants frequent in-person meetings or complex private wealth services, a full-service firm may fit better.
- Low-cost advice model
- Hybrid human and digital service
- Focus on low-cost funds and long-term planning
- Clear fee structure in recent coverage
- Minimum of $50,000 in recent coverage for Personal Advisor
- Less branch access than Fidelity or Schwab
- Planning depth varies by tier
Morgan Stanley Wealth Management is built for clients who want a dedicated adviser relationship and a full range of wealth services. Advisers can cover investment management, retirement planning, estate and tax coordination, lending, and family office style services for larger clients. Global research and a wide investment menu support more complex portfolios and goals.
Minimums and fees are the barrier. Recent coverage describes Morgan Stanley private services with minimums around $1,000,000 for some tiers, with fees around 1.00 percent per year in some summaries, though exact terms depend on service and assets. Small investors will find better value in Fidelity, Schwab, or Vanguard digital advice. Morgan Stanley fits best when your assets, complexity, and need for a dedicated team justify a full-service fee.
- Dedicated advisers and private wealth services
- Broad investment, lending, and planning options
- Global research and market access
- High minimums for private services in recent coverage
- Fees vary by service and assets
- Less suited to small accounts
Merrill, part of Bank of America, suits clients who want banking and investing in one relationship. Checking, savings, credit cards, and investment accounts can be viewed together, and Preferred Rewards tiers can add banking benefits for larger combined balances. Merrill Guided Investing offers digital advice at a lower cost, while Merrill Wealth Management offers dedicated advisers for larger clients.
Recent coverage lists Merrill Guided Investing at 0.45 percent per year with a $1,000 minimum, and an adviser version at $20,000, while full wealth management fees are higher and vary by assets. The catch is tier choice again. A digital service will not give you the same planning depth as a dedicated adviser, and banking integration is most valuable if you already bank with Bank of America. If you do, Merrill is a convenient and strong option.
- Integrated banking and investing through Bank of America
- Dedicated advisers on higher tiers
- Merrill Guided Investing for digital advice
- Fees and minimums vary by service
- Guided investing fee around 0.45 percent per year in recent coverage
- Adviser version needs a higher minimum
Edward Jones suits people who want a local adviser they can meet in person. With thousands of branch offices across the US, Edward Jones offers face-to-face planning, regular reviews, and a relationship model that appeals to retirees and long-term investors who prefer personal contact over a digital dashboard. Advisers cover retirement, education, estate coordination, and investment planning.
Fees depend on whether you choose a commission-based brokerage account, a fee-based advisory account, or another service, so a single fee figure does not describe Edward Jones. That variety means you must ask for the exact fee schedule for your account type. If you value local, in-person advice and a steady relationship, Edward Jones is a strong fit. If you want low-cost digital advice, Vanguard or Schwab digital services may cost less.
- Large network of local branch offices
- Relationship-based planning with a dedicated adviser
- Strong for retirement and long-term goals
- Fees vary by account type and service
- Less digital-first than Fidelity or Schwab
- Branch experience varies by adviser
UBS Wealth Management, part of UBS Group, is a global private wealth firm with a strong US presence for high-net-worth clients. It offers dedicated adviser teams, family office services, philanthropy planning, and global investment access, which suit clients with complex cross-border needs, business interests, or large family wealth.
UBS is not built for small accounts. Minimums, fees, and service tiers for private wealth are set for larger clients, and the experience depends heavily on the specific team. For a client with global assets or complex family planning, UBS is a credible top-tier choice. For a typical retirement investor, Fidelity, Schwab, or Vanguard will offer lower cost and easier access.
- Global private wealth expertise
- Dedicated teams for high-net-worth and ultra-high-net-worth clients
- Broad investment and lending options
- High minimums and fees for private services
- Less accessible for smaller investors
- Service model varies by region and team
Ameriprise Financial offers comprehensive planning through a large network of advisers, with a focus on retirement, tax, estate, and investment coordination. Clients get a written financial plan, regular reviews, and a managed portfolio, which suits people who want one adviser to coordinate several parts of their financial life rather than separate tools for each goal.
Fees are the main thing to clarify. Ameriprise fees can include planning fees, advisory fees, and fund costs, depending on service, so ask for a total cost breakdown before you sign. Adviser experience also varies, as with any large network, so interview the specific adviser, not just the firm. If you want a single comprehensive plan and a dedicated adviser, Ameriprise is a strong option to compare with Edward Jones and Merrill.
- Comprehensive financial planning with a dedicated adviser
- Large adviser network
- Retirement, tax, and estate coordination
- Fees vary by service and assets
- Planning fees may apply in addition to investment fees
- Adviser experience varies
J.P. Morgan Wealth Management and J.P. Morgan Private Bank serve clients who want a bank, a wealth manager, and a private banker in one relationship. Services cover investment management, trust and estate planning, lending, and family office support for larger clients, with Chase banking integration for clients who already bank with Chase. Research and market access are broad.
Private bank minimums are high, and the exact service you get depends on assets and tier. Smaller investors can use Chase and J.P. Morgan digital investing services, but those are different from private bank advice. For a high-net-worth client who wants integrated banking and private wealth services, J.P. Morgan is a top-tier choice. For a typical investor, Fidelity, Schwab, or Vanguard will be simpler and cheaper.
- Private bank and wealth management services for high-net-worth clients
- Integrated banking, lending, and investing through Chase
- Strong research
- Private bank minimums are high
- Service tiers vary widely
- Less suited to small or digital-only investors
How we picked these
We compared recent wealth management coverage, firm service descriptions, and fee and minimum summaries from independent roundups. We included accessible digital and hybrid advice firms, full-service wirehouses, and relationship-based firms, because the best firm depends on assets, complexity, and service style. We did not invent a single fee or minimum for any firm, since fees vary by service tier, and we list See website where a quote is needed. This article is general information, not financial advice, and you should verify registration, disciplinary history, and fiduciary status before hiring an adviser.
What to check before you choose
Ask about fees in total, not just the headline advisory fee. Add fund expense ratios, planning fees, trading costs, and any account fees to get a true annual cost. A 0.30 percent advisory fee with low-cost funds can cost less overall than a 0.80 percent fee with higher fund costs. Ask whether the fee is based on assets, a flat fee, hourly, or a mix, and whether it changes as assets grow.
Ask about fiduciary status and conflicts next. A fiduciary adviser must act in your best interest for that service, while a broker may operate under a different standard for some accounts. Ask the adviser to state, in writing, which standard applies to your account and how they are paid. Also ask how often you will meet, who your day-to-day contact will be, and what happens if your adviser leaves the firm.
Minimums, service style, and fit
Match the service to your assets and style. Digital advice suits smaller accounts and hands-off investors. Hybrid advice suits investors who want a plan plus occasional human help. Dedicated advice suits larger, more complex clients who want regular meetings and coordination. A firm that is excellent for a $5 million client may be a poor fit for a $50,000 client, and vice versa. Interview two or three advisers, compare their plans and fees, and choose the person and service, not just the brand.
Questions to ask any adviser
Ask how they invest, how they handle downturns, how they coordinate tax and estate planning, and how they are paid. Ask for a sample plan, a fee schedule, and references or disciplinary history through public regulator records. A good adviser will answer clearly, explain risks, and welcome a second opinion. If fees, conflicts, or investment choices are unclear, keep looking.
Frequently asked questions
Which wealth management company is the best overall?
There is no single best firm for every investor. Fidelity, Schwab, and Vanguard suit accessible planning and retirement investors, while Morgan Stanley, Merrill, UBS, and J.P. Morgan suit high-net-worth clients. The best firm for you depends on assets, complexity, service style, and total fees.
What is the best investment advisory service for beginners?
Digital and hybrid services such as Fidelity Go, Schwab Intelligent Portfolios, and Vanguard Personal Advisor suit beginners with lower minimums and clear fees. Start with a service that matches your assets, and move to dedicated advice as complexity grows.
How much do wealth management companies charge?
Fees vary by service, from around 0.25 percent to 0.30 percent per year for some digital and hybrid services in recent coverage, to around 0.80 percent to 1.00 percent or more for dedicated advice, plus fund costs. Always ask for a total fee breakdown for your exact service.
What minimum do I need for wealth management?
Minimums vary widely. Some digital services start at $0 to $5,000, hybrid services often start at $25,000 to $50,000, and private wealth services can start at $250,000 to $1,000,000 or more. Check the minimum for the specific service, not just the firm name.
Is a wealth manager a fiduciary?
It depends on the service and registration. Some advisory services are fiduciary, while brokerage services may operate under a different standard. Ask the adviser to confirm, in writing, whether they act as a fiduciary for your account and how they are paid.
Should I choose a local adviser or a digital service?
Choose a local adviser if you want in-person meetings and a long-term relationship, such as Edward Jones or Ameriprise. Choose a digital or hybrid service if you want lower cost and mostly online access, such as Vanguard, Schwab, or Fidelity digital advice. Many investors use a hybrid service as a middle path.
Sources
- https://www.fidelity.com/
- https://www.schwab.com/
- https://investor.vanguard.com/
- https://www.morganstanley.com/
- https://www.ml.com/
- https://www.edwardjones.com/
- https://www.ubs.com/
- https://www.ameriprise.com/
- https://www.jpmorgan.com/
- https://morningconsult.com/articles/fidelity-schwab-jpmorgan-wealth-management-brand-analysis
- https://vaultzeno.com/financial-planning/best-financial-advisors/
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 best rank tracking software
Best Rank Tracking Software in 2026
Searching for the best rank tracking software? We compare 8 tools for daily keyword tracking, local rankings, client reports, and competitor checks in 2026.
Read → best platform for ecommerce website
Best Platform for Ecommerce Website in 2026
Find the best platform for ecommerce website builds in 2026. We compare Shopify, WooCommerce, BigCommerce, Wix and more on price, fees and scale for stores.
Read → best math apps
Best Math Apps in 2026: 8 Apps Compared
Find the best math apps for homework, revision, and deeper study in our 2026 comparison of 8 free and paid solvers, courses, and visual tools for students.
Read →