 ProMapRanker
Best Retirement Planning Companies in 2026

Key takeaways
- Fidelity, Vanguard and Charles Schwab suit investors who want low-cost accounts plus planning tools.
- Empower suits workers who want to track a workplace plan and outside accounts in one view.
- T. Rowe Price and Principal suit investors who want managed funds and workplace plan support.
- Betterment suits hands-off investors who want automated portfolios and goal planning.
- This guide is general information only, not financial advice, and no return or outcome is promised.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 Fidelity | All-round retirement planning | See website | No | Visit |
 Vanguard | Low-cost retirement investing | See website | No | Visit |
 Charles Schwab | Planning tools and support | See website | No | Visit |
 Empower | Workplace plan tracking | See website | No | Visit |
 T. Rowe Price | Managed retirement funds | See website | No | Visit |
 Merrill | Bank-linked retirement advice | See website | No | Visit |
 Betterment | Automated retirement investing | See website | No | Visit |
 Principal | Workplace plans and advice | See website | No | Visit |
 Edward Jones | Branch-based personal advice | See website | No | Visit |
The best retirement planning companies
Retirement planning is not one product. Some people need an IRA and a simple plan, others need help with a workplace 401k, a rollover, Social Security timing and withdrawals. The firms below cover those needs in different ways, from low-cost self-directed accounts to branch-based advice and automated portfolios. The right firm depends on how much help you want and how you prefer to manage money.
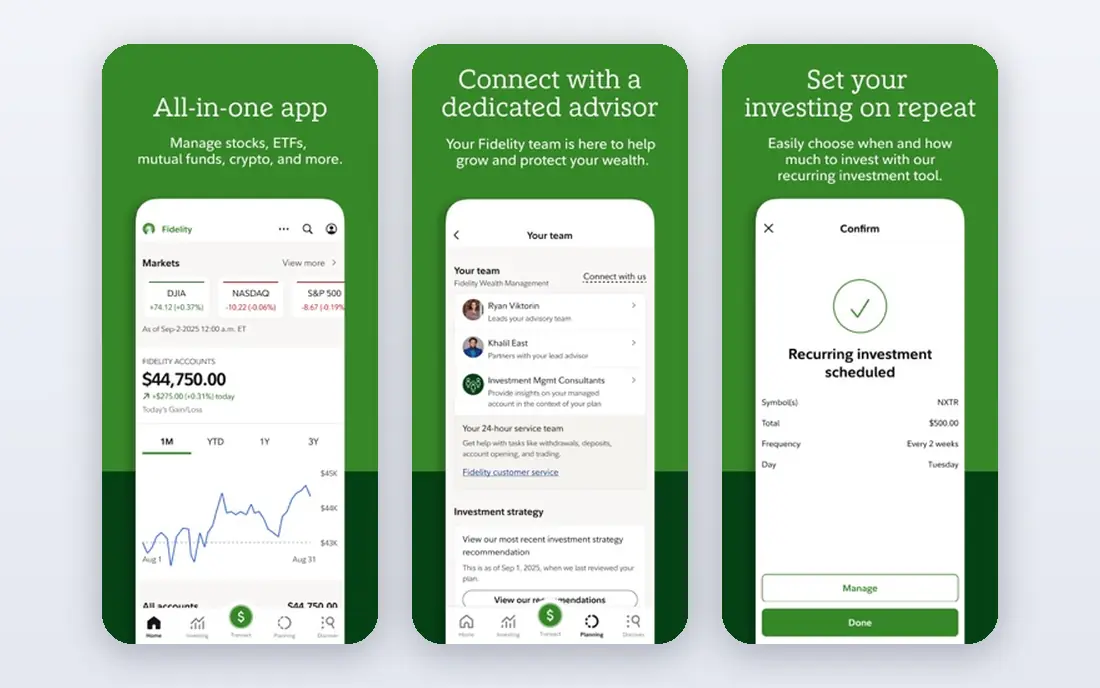
Fidelity is a strong all-round choice for retirement planning, with IRAs, workplace plan support, planning tools and a broad range of funds, ETFs and other investments. Its calculators help with saving rates, Social Security timing and withdrawal planning, and its workplace plan tools can pull actual balances into a plan. That combination suits investors who want to manage their own plan but also want tools and support when a decision is complex.
The breadth can overwhelm a new investor, because the range of funds and account types is large. Advice services are available, but they cost extra and should be compared with the cost of managing the account yourself. For most retirement savers, Fidelity offers a good balance of low-cost investing, planning tools and human support.
- Wide IRA and 401k support
- Planning tools and calculators
- Broad investment range
- Choice can overwhelm new investors
- Advice services cost extra
Vanguard is known for low-cost index funds and target-date funds, which suit retirement savers who want a simple, diversified portfolio that needs little ongoing trading. Target-date funds adjust their mix over time toward a retirement year, which helps investors who do not want to rebalance manually. IRA and rollover support lets workers move an old workplace plan into an account they control.
The digital experience is plainer than some rivals, and the advice offer is narrower than a full-service wealth firm. Investors who want a slick app or frequent human advice may prefer Fidelity or Schwab. For a low-cost, long-term retirement portfolio, Vanguard remains a central choice, and its target-date funds are a sensible default for many savers.
- Low-cost index funds and target-date funds
- IRA and rollover support
- Long-term investing focus
- Digital tools are plainer than some rivals
- Advice options are more limited in scope
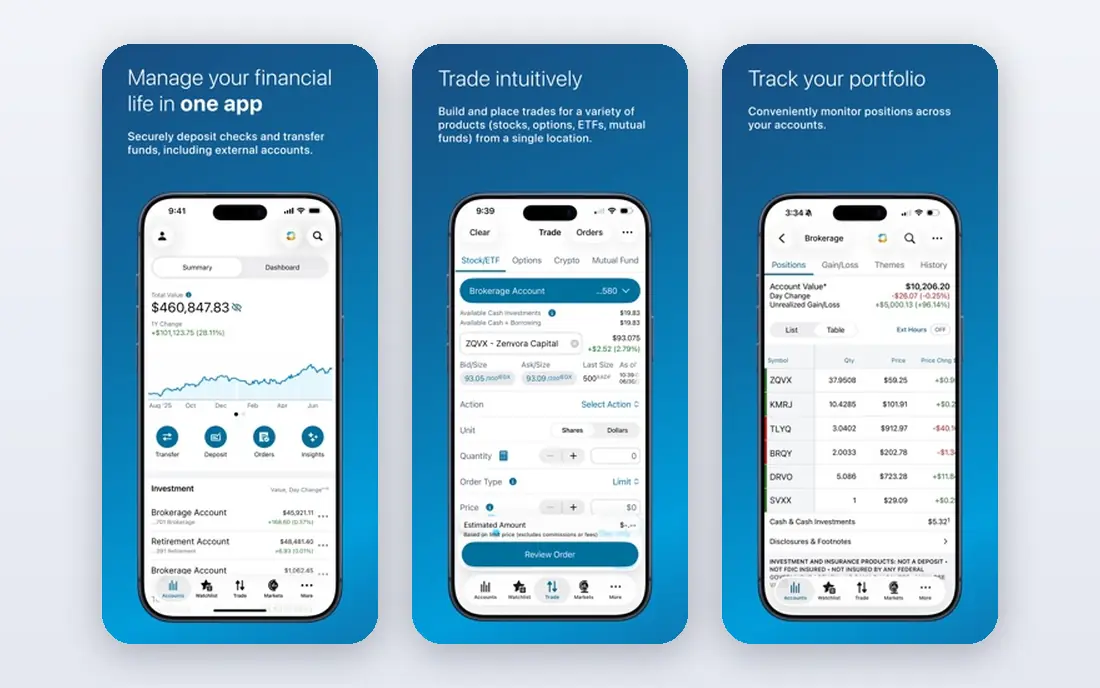
Charles Schwab combines planning tools, IRA and workplace plan support, and branch and phone help, which suits investors who want both digital tools and a person to talk to. Its retirement planners cover saving, Social Security and withdrawals, and its managed portfolio options suit investors who want help but do not want a traditional adviser relationship. The firm also ranked highly in recent digital experience studies for retirement plan participants.
Managed services can need higher balances, and the fund range still needs care, because not every fund is low cost. Check expense ratios and advice fees before you choose a managed option. For investors who want strong tools plus support, Schwab is a well-rounded retirement firm.
- Planning tools and calculators
- IRA and 401k support
- Branch and phone support
- Some managed services need higher balances
- Fund choice needs care
Empower, formerly Empower Retirement, is a major workplace retirement plan provider, and its personal dashboard helps workers see a workplace plan alongside outside accounts. That single view matters, because many savers hold a 401k, an IRA and a taxable account at different firms, and a plan built on only one account will be incomplete. Retirement income tools help model withdrawals and spending in retirement.
The experience depends on the employer plan, because plan rules, funds and fees vary by employer. Full advice services cost extra, and self-directed investors may prefer a firm with a broader fund range for an IRA. For workers whose main retirement savings sit in a workplace plan, Empower is a natural place to start planning.
- Workplace retirement plan expertise
- Account aggregation and dashboard
- Retirement income tools
- Full advice services cost extra
- Experience depends on the employer plan
T. Rowe Price suits investors who want actively managed retirement funds and a clear retirement income planning tool. Its Retirement Income Calculator uses scenario modelling to show how a plan might hold up under different market outcomes, which helps savers move from a single savings target to a range of possible outcomes. IRA and workplace plan support covers rollovers and ongoing saving.
Actively managed funds cost more than index funds, and some funds have minimum investments, with $2,500 for some accounts and $1,000 for some IRAs in recent fund information. That cost needs to be weighed against the value of active management for your situation. For investors who prefer managed funds and a strong income planning tool, T. Rowe Price is a credible choice.
- Actively managed retirement funds
- Retirement income calculator
- IRA and workplace support
- Actively managed funds cost more than index funds
- Minimums apply to some funds
Merrill, part of Bank of America, suits savers who want retirement advice linked to a bank relationship. IRA and rollover support, adviser access and guided investing options help investors who want a plan built with a professional, rather than a purely self-directed account. Bank integration also makes it easy to see banking and investment accounts together, and recent digital experience studies ranked Bank of America, including Merrill, highly for retirement plan participants.
Guided investing needs a minimum balance, with $5,000 noted for Merrill Guided Investing in recent information, and advice fees apply. Self-directed investors who want the lowest cost may prefer Fidelity, Vanguard or Schwab. For savers who value an adviser and a bank link, Merrill is a strong option.
- IRA and rollover support
- Adviser access
- Bank of America integration
- Managed investing needs a minimum balance
- Advice fees apply
Betterment suits hands-off retirement savers who want an automated portfolio built around a retirement goal. You set the goal, time horizon and risk level, and Betterment builds and rebalances a diversified portfolio, with tax-aware features on taxable accounts. IRA and rollover support lets you move an old workplace plan into an automated retirement account.
The trade-off is control. You choose a goal and a risk level, not individual funds, which suits many savers but not investors who want to pick stocks or specific funds. Advice is mainly digital, though human advice options exist on higher tiers. For a saver who wants retirement investing handled with little ongoing work, Betterment is a clear choice.
- Automated portfolios and goal planning
- IRA and rollover support
- Low starting balance on some plans
- Less control over individual funds
- Advice is mainly digital
Principal Financial Group is a major workplace retirement plan provider, with planning tools and support for both employers and participants. Workers with a Principal workplace plan can use its tools to model saving, income and withdrawals, and employers can use its plan services for administration and participant education. That workplace focus makes Principal a natural planning firm for many employees.
The experience depends on the employer plan, as with Empower, because funds, fees and features vary by plan. Retail investors opening a standalone IRA may find a broader fund range at Fidelity, Vanguard or Schwab. For workers whose retirement savings are mainly in a Principal workplace plan, starting with Principal's tools and advice is the practical move.
- Major workplace plan provider
- Retirement planning tools
- Adviser and employer support
- Experience depends on the employer plan
- Retail IRA range is narrower than some rivals
Edward Jones suits savers who want a personal adviser and a branch relationship, rather than a purely digital account. Advisers help with retirement planning, IRA and rollover decisions, and wider goals such as estate planning, in face-to-face meetings. That personal model appeals to savers who want a trusted adviser to talk through major decisions such as retirement timing and withdrawals.
Advice fees and fund costs can be higher than a low-cost self-directed account, so compare total costs before you commit. Self-directed investors who want index funds and a simple app will find better value elsewhere. For savers who value a long-term adviser relationship and in-person support, Edward Jones is a well-known choice.
- Personal adviser relationship
- Branch network
- Retirement and estate planning support
- Advice fees and fund costs can be higher
- Less suited to self-directed low-cost investing
How we picked these
We compared public information on retirement firms, including account types, planning tools, workplace plan scale, advice models and fund ranges in October 2026. We kept firms that offer retirement planning today and that cover a clear saver type, from self-directed to advised to automated. We did not promise returns, and we wrote See website where fees, minimums and advice costs vary by account and plan, because the vendor page for your exact account is the reliable source.
How to choose a retirement planning company
Start with how much help you want. A self-directed saver needs low costs, good funds and clear tools. A hands-off saver needs automation and goal planning. A saver with a complex situation, such as a pension, rental income or a business, may need an adviser. The firm that fits your help level matters more than any single fund.
Accounts, fees and funds
Check whether the firm offers the accounts you need, such as a traditional IRA, Roth IRA, rollover IRA or a workplace plan link. Compare account fees, fund expense ratios and advice fees, not just one of them. A low account fee with high fund costs is not low cost overall, and a managed service fee should be judged against the help it actually provides.
Planning tools and advice
Test the planning tool with your own numbers, including saving rate, retirement age and spending needs. A good tool shows a range of outcomes, not a single confident number, and lets you change assumptions. If you want advice, ask how the adviser is paid, what the advice covers, and whether the adviser is a fiduciary for your account.
Rollovers, Social Security and withdrawals
If you are moving an old 401k, ask about direct rollovers, tax handling and timing, and do not cash out a workplace plan without advice, because taxes and penalties may apply. For Social Security, the claiming age affects lifetime income, so model it carefully. For withdrawals, check how the firm helps with required minimum distributions and tax-aware withdrawal order. These decisions matter more than picking a single fund.
Frequently asked questions
What is the best retirement planning company?
The best retirement planning company depends on how you want to invest. Fidelity, Vanguard and Schwab suit low-cost self-directed planning, Empower and Principal suit workplace plan savers, Betterment suits automated investing, and Edward Jones suits branch-based advice. This guide is general information only, not financial advice, and no outcome is promised.
Should I use a target-date fund for retirement?
A target-date fund can be a simple choice, because it holds a diversified mix and adjusts toward a retirement year. Check the expense ratio, the glide path and whether the fund is index-based or actively managed, because those details vary by firm. A target-date fund suits savers who want one fund to handle diversification and rebalancing, but it is not a personal plan on its own.
How do I roll over an old 401k?
A direct rollover moves money from a workplace plan to an IRA without you holding the funds, which usually avoids tax withholding issues. Contact the new firm first, confirm the receiving account type, and follow its rollover steps. Do not cash out the plan without advice, because taxes and early withdrawal penalties may apply, and this guide is not financial advice.
When should I start retirement planning?
Now, whatever your age, because earlier saving gives compounding more time to work, and small increases in saving rate matter more than perfect fund choices. Start with a saving rate you can sustain, use a planning tool to test it, and review the plan each year or after a major life change. A simple plan started today beats a perfect plan delayed for years.
Do I need a financial adviser for retirement?
Not everyone does. Self-directed savers with simple accounts can use low-cost funds and planning tools, while savers with pensions, business income, complex taxes or a near retirement date may benefit from advice. If you hire an adviser, ask how they are paid, what they cover, and whether they act as a fiduciary for your account.
How much should I save for retirement?
A common starting point is to save at least 15 percent of pre-tax income, including any employer match, but the right rate depends on age, income, retirement age and spending plans. Use a planning tool with your own numbers, test different saving rates and retirement ages, and treat any rule of thumb as a starting point, not a personal plan.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 wpforms alternatives
Best WPForms Alternatives in 2026
We compare 9 wpforms alternatives for WordPress forms, with free and paid options, current pricing notes, and honest limits for small business sites in 2026.
Read → windows task scheduler alternatives
Best Windows Task Scheduler Alternatives in 2026
Looking for Windows Task Scheduler alternatives? We compare 9 schedulers for Windows and cross-platform work, from free tools to enterprise automation.
Read → which ai video service is best
Which AI Video Service Is Best in 2026
which ai video service is best? We compare 10 legitimate AI video services on price, avatars, editing and output quality to help you pick the right tool.
Read →