 ProMapRanker
Best House Insurance Companies in 2026

Key takeaways
- State Farm suits most households that want a local agent and bundling, while Amica suits households that put claims service first.
- USAA leads for eligible military families, but membership is restricted to the military community and eligible family members.
- Erie and Auto-Owners offer strong service where they operate, but both cover fewer states than national carriers.
- Premiums vary by home, location, and coverage, so get at least three quotes for the same coverage limits before choosing.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 State Farm | Local agents and bundling | See website | No | Visit |
 USAA | Military families | See website | No | Visit |
 Amica | Claims satisfaction | See website | No | Visit |
 Allstate | Bundling and digital tools | See website | No | Visit |
 Travelers | Coverage breadth | See website | No | Visit |
 Lemonade | Digital-first buyers | See website | No | Visit |
 Chubb | High-value homes | See website | No | Visit |
 Erie Insurance | Regional service quality | See website | No | Visit |
The best house insurance companies
We compared coverage, claims satisfaction, financial strength, discounts, and availability for homeowners choosing a policy in 2026. Coverage varies by state and policy, so check policy details before buying.
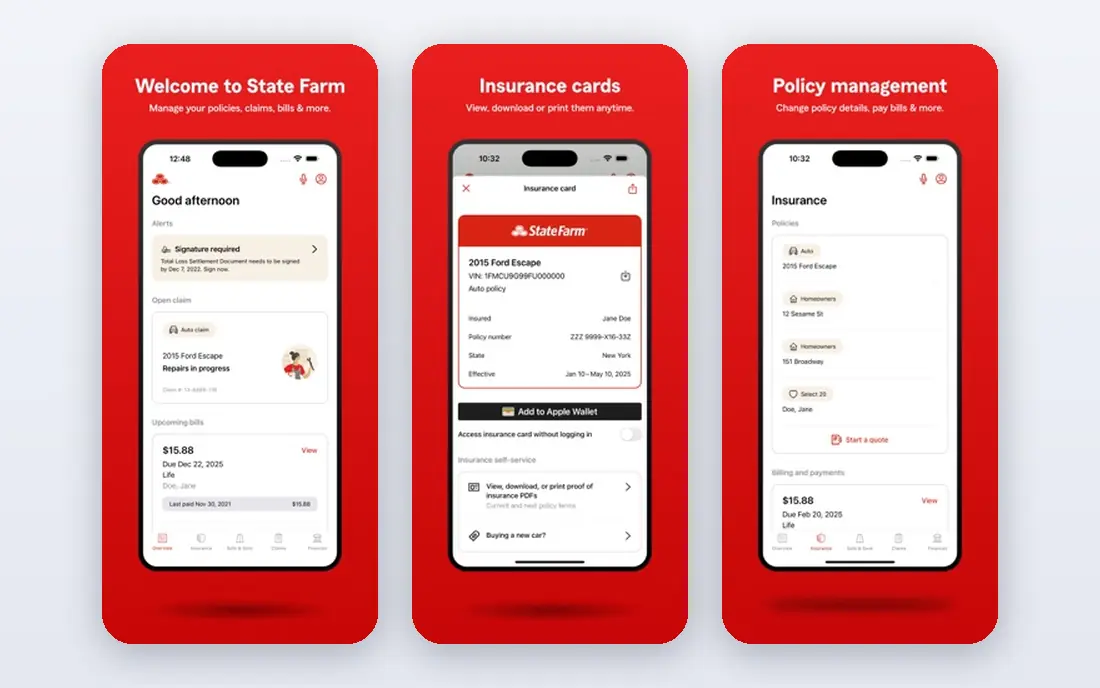
State Farm is a steady default for many households because it combines national scale with local agents. A local agent can walk through dwelling limits, deductibles, and endorsements in person, and bundling home and auto often brings a meaningful discount. Claims support through a large network also helps after regional storms.
Flexibility is the trade-off. Some rivals offer more custom endorsements or digital-first tools, and State Farm does not include flood coverage as standard. Get a quote for the same limits as rivals, and ask specifically about replacement cost, water damage, and roof coverage.
- Largest US home insurer in many comparisons
- Extensive local agent network
- Strong bundling discounts with auto
- Coverage options can feel less flexible than some rivals
- Flood coverage is not standard and needs a separate policy
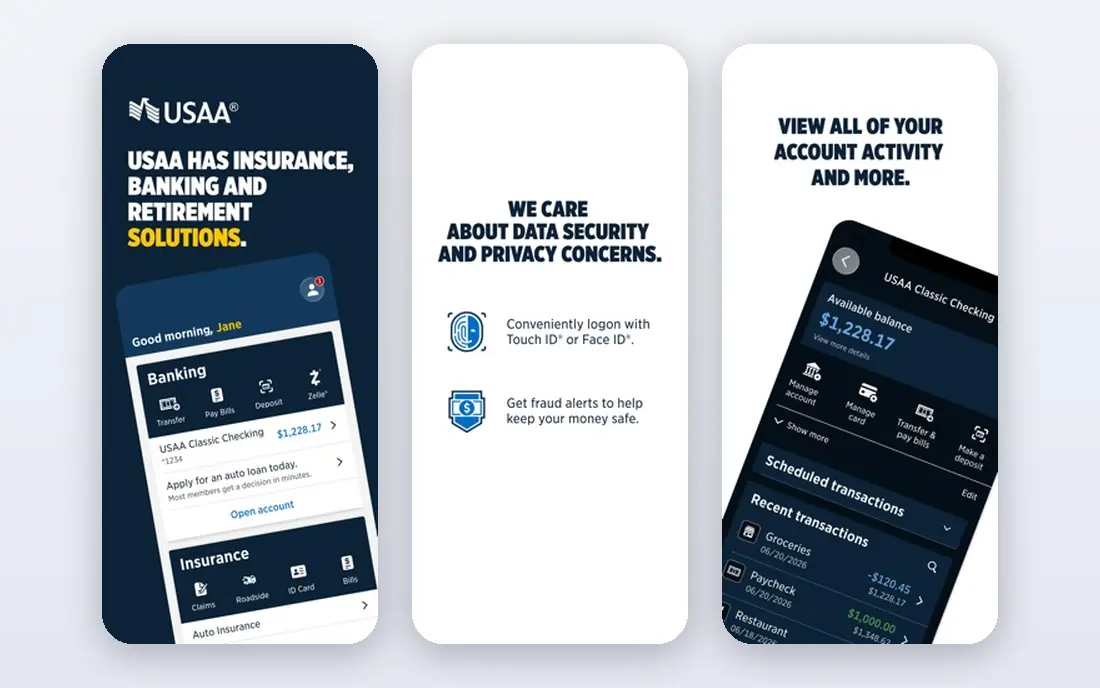
USAA consistently ranks near the top for member satisfaction and value, but only for those who qualify. Eligible military members, veterans, and family members get access to policies with replacement cost coverage as standard in many cases, plus strong digital tools and member service. Published 2026 comparisons show lower sample premiums for USAA than for many national rivals.
Eligibility is the gate. If you do not qualify, USAA is not an option, no matter how strong its scores look. Eligible readers should get a USAA quote first, then compare it with two other carriers on identical limits.
- Strong satisfaction scores in published studies
- Replacement cost coverage standard in many policies
- Rates often below market median for members
- Membership restricted to military members, veterans, and eligible family
- Few local branch offices
Amica is the pick for households that care most about the claims experience. It has led homeowner satisfaction studies for years, and its mutual structure means policyholders can receive dividends that return part of their premium. That service focus matters most when a claim is stressful and complex.
Price is the catch. Amica premiums often sit above the median, and it sells mainly direct rather than through local agents. If service at claim time matters more than the lowest quote, Amica is worth a quote, especially for households that plan to stay long term.
- Top claims satisfaction in J.D. Power studies
- Dividend policies can return part of premium
- Strong financial strength
- Premiums often sit above median
- No local agent network in the traditional sense
Allstate balances agents and technology. Households get local agent access, a strong app for claims and policy management, and bundling options with auto. Claim-free rewards in some policies can lower deductibles over time for households with no claims, which suits low-risk areas.
Regional variation is the warning. Satisfaction and pricing differ by state and even by area, so national averages tell only part of the story. Check local reviews, get a quote for identical coverage, and ask about roof, water, and smart-home discounts in your area.
- Large agent network plus digital tools
- Bundling discounts
- Claim-free rewards in some policies
- Customer satisfaction varies by region
- Premiums can be higher in some markets
Travelers suits households that want broad coverage options and discounts. It offers a wide discount menu, including smart-home device discounts, plus endorsements such as green rebuilding that help after a loss. Financial strength ratings are strong, which matters for large claims.
Satisfaction is the weaker point. Published studies place Travelers below Amica, USAA, and Erie on some satisfaction measures, though results vary by year and region. Compare its quote and endorsements carefully, especially for water damage and roof coverage, before choosing on price alone.
- Strong financial strength
- Broad discount menu
- Green rebuilding and smart-home endorsements
- Satisfaction scores sit below some rivals
- Coverage varies by state
Lemonade appeals to buyers who want to quote, buy, and claim from a phone. Its app-first process is fast, its pricing can be competitive for younger and urban homeowners, and its giveback model donates leftover premiums to causes chosen by policyholders. For a straightforward condo or newer home, that simplicity is attractive.
Complex homes are the limit. Older homes, high-value homes, and homes needing many endorsements may fit better with a traditional carrier. Check dwelling limits, replacement cost options, and exclusions carefully, and confirm availability in your state.
- Fast digital quotes and claims
- Simple app experience
- Charitable giveback model
- Coverage options are narrower for older or high-value homes
- Less personal agent service
Chubb is built for high-value homes, not for the cheapest quote on a standard house. It offers extended replacement cost, cash settlement options, and risk consulting that helps owners protect art, collections, and custom features. Complaint volume is very low in published data, and satisfaction scores are strong.
Standard homes will find Chubb costly. Its pricing reflects higher limits and broader coverage, so households with a typical home should compare it only if they need high limits or specialist coverage. For a high-value home, get a Chubb quote beside a traditional carrier quote on identical limits.
- Extended replacement cost and cash settlement options
- Very low complaint volume
- Risk consulting for high-value homes
- Premium pricing is high for standard homes
- Built for higher-value properties
Erie Insurance offers excellent service where it operates. It provides guaranteed replacement cost options, low complaint volume, and strong local agent support, with satisfaction scores near the top in published studies. Households in its states often find it a strong value pick.
Geography is the barrier. Erie writes policies in only about a dozen states plus D.C., so most US readers cannot buy it. If you live in an Erie state, get a quote; if not, look to State Farm, Amica, or Travelers for a similar service focus at national scale.
- Guaranteed replacement cost available
- Consistently low complaint volume
- Strong local agent support
- Available in only 12 states plus D.C. in published comparisons
- Digital tools are more limited than national carriers
How we picked these
We compared published 2026 homeowner comparisons, J.D. Power satisfaction data as reported in those comparisons, AM Best financial strength ratings, and official carrier pages for coverage, discounts, and availability. We favoured carriers with strong financial strength, clear replacement cost options, and low complaint volume, and we kept regional carriers where their service justified inclusion. We did not claim hands-on claims testing, and premiums shown in third-party comparisons are sample figures, not quotes for your home.
How to choose the best house insurance company for you
Get quotes for identical coverage. Use the same dwelling limit, deductible, personal property limit, and liability limit for every carrier, or the cheapest quote may simply be the thinnest policy. Ask about replacement cost versus actual cash value for dwelling and belongings, since that choice changes claim payouts more than a small premium difference.
Check endorsements that matter for your home. Water damage, sewer backup, ordinance and law, roof coverage, and valuable items often need separate endorsements or limits. Flood and earthquake coverage are usually separate policies, so ask about them even if your main quote looks complete.
Discounts that actually help
Bundling home and auto, adding monitored alarms or smart-home devices, raising your deductible to a level you can afford, and keeping a claim-free record can all lower premiums. Ask each carrier to list every discount you qualify for, and check whether a discount requires a device, an inspection, or a multi-year commitment. A discount that changes your daily life may not be worth a small saving.
Claims service matters more than price
A low premium helps every month, but claims service matters when a pipe bursts or a storm damages a roof. Check complaint ratios, satisfaction scores, and local agent reviews, and ask how claims are filed, how fast an adjuster responds, and whether repairs use the carrier network or your own contractor. That service picture, plus financial strength, should weigh beside price.
Frequently asked questions
Which home insurance company is the best?
There is no single best company for every home. State Farm suits most households that want agents and bundling, Amica suits households that put claims service first, and USAA suits eligible military families. Get at least three quotes for identical coverage, then weigh price, claims service, and financial strength together.
What is the best insurance company for home insurance in 2026?
Published 2026 comparisons place USAA, State Farm, Amica, Erie, and Auto-Owners near the top on a mix of price, satisfaction, and financial strength. The best pick for you depends on your state, home value, and whether you qualify for USAA or live in an Erie state. Compare identical limits, not headline premiums alone.
How much does house insurance cost?
Premiums vary widely by home value, location, roof age, claims history, and coverage limits, so national averages are only a planning guide. Sample 2026 figures in published comparisons run roughly from $1,200 to $2,000 per year for a typical home, with high-value homes costing more. Your quote will differ, so get personal quotes for your exact home.
Does house insurance cover floods?
Standard homeowners policies usually do not cover flood damage. Flood coverage usually requires a separate policy through the National Flood Insurance Program or a private flood insurer. If you live near water or in a flood-prone area, ask your agent about flood coverage even if your main policy looks complete.
Should I bundle home and auto insurance?
Bundling often brings a discount and simpler billing, and State Farm, Allstate, and other large carriers offer strong bundling options. Bundling is not always cheapest, though, since one carrier may price home well and auto poorly. Compare bundled and separate quotes for identical coverage before deciding.
What is replacement cost coverage?
Replacement cost coverage pays to rebuild or replace damaged property with similar new materials, without deducting for depreciation, up to your policy limit. Actual cash value coverage deducts depreciation, which can leave a large gap after a major loss. Ask whether your dwelling and belongings use replacement cost, and whether extended or guaranteed replacement cost is available.
Sources
- https://www.statefarm.com
- https://www.usaa.com
- https://www.amica.com
- https://www.allstate.com
- https://www.travelers.com
- https://www.lemonade.com
- https://www.chubb.com
- https://www.erieinsurance.com
- https://www.monitorbankrates.com/homeowners-insurance
- https://vaultzeno.com/insurance/best-homeowners-insurance/
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 zoom alternatives
Best Zoom Alternatives in 2026
Compare Zoom alternatives in 2026, with free meeting limits and prices, so you can pick the best alternative to Zoom for your team, class, or community.
Read → which software is best for remote work
Which Software Is Best for Remote Work in 2026
Answering which software is best for remote work, we compare Slack, Zoom, Asana, Notion, Teams and more, with pricing and honest tradeoffs in 2026 now.
Read → which ai tool is best for content writing
Which AI Tool Is Best for Content Writing in 2026
Wondering which ai tool is best for content writing? We compare ChatGPT, Claude, Jasper, Grammarly, and more on price, quality, and best use in 2026 now.
Read →