 ProMapRanker
Best Fixed Annuity Companies in 2026

Financial strength and income annuities · Pricing starts at: See website
Key takeaways
- Fixed annuities, including multi-year guaranteed annuities, offer a guaranteed rate for a set term plus tax-deferred growth, but rates, terms, and surrender charges vary by state and contract.
- New York Life and MassMutual both hold A++ ratings from AM Best in recent comparisons, while Pacific Life, Nationwide, Allianz Life, and others hold A+ ratings.
- A higher financial strength rating does not guarantee the best rate or income, so compare the actual contract rate, term, surrender period, and withdrawal terms.
- This article is general information only and is not financial advice. Annuity rates are not promised here, and you should get a current rate sheet and read the contract before buying.
- An independent agent or adviser can compare contracts across carriers, which matters because the same company may offer very different terms by state.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
| New York Life | Financial strength and income annuities | See website | No | Visit |
 MassMutual | Stable mutual company contracts | See website | No | Visit |
 Pacific Life | Wide annuity range direct to consumers | See website | No | Visit |
 Nationwide | Low minimum income options | See website | No | Visit |
 Allianz Life | Fixed and indexed options | See website | No | Visit |
 Athene | Large fixed annuity sales volume | See website | No | Visit |
 Lincoln Financial | Broad payout menus | See website | No | Visit |
 Prudential | Large insurer with varied annuities | See website | No | Visit |
 Guardian Life | Strong mutual company strength | See website | No | Visit |
The best fixed annuity companies
Fixed annuities appeal to savers who want predictable growth without market risk. The companies below are judged on financial strength, product range, and contract features that matter for a multi-year commitment, not on a single advertised rate.
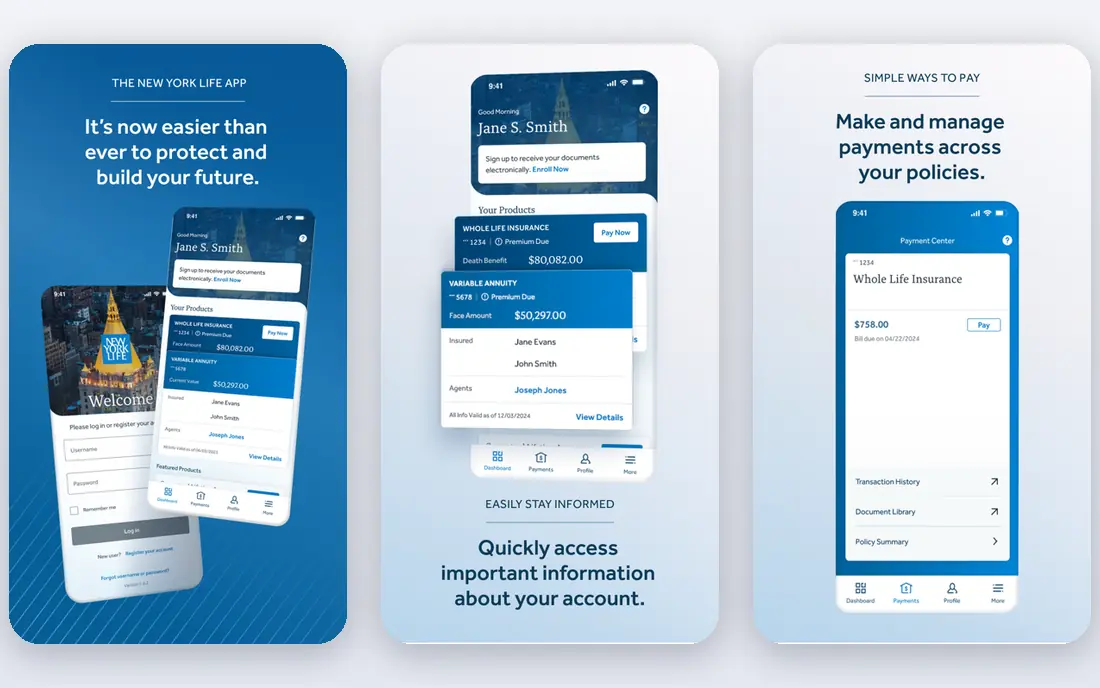
New York Life is the largest mutual life insurance company in the United States, and it holds the highest financial strength ratings currently awarded to a US life insurer from all four major agencies in some comparisons. That strength matters for a fixed annuity, since the promise lasts for years and depends on the insurer paying claims far into the future. The company offers fixed deferred, income, and variable annuities, and it publishes a weekly side-by-side rate comparison chart for popular products, which adds transparency many carriers lack.
The trade-off is that a top rating does not mean the highest rate on every term. New York Life often trades a slightly lower rate for stability, and contract terms vary by state. Buyers should request a current rate sheet for the exact term and state, and check surrender periods and free withdrawal terms before signing. For savers who prioritize insurer strength above a headline rate, New York Life is a natural first quote.
- A++ rating from AM Best in recent comparisons
- Wide range of fixed deferred, income, and variable annuities
- Weekly rate comparison chart for popular products
- Rates and terms vary by state and product
- Many purchases go through an agent rather than fully online
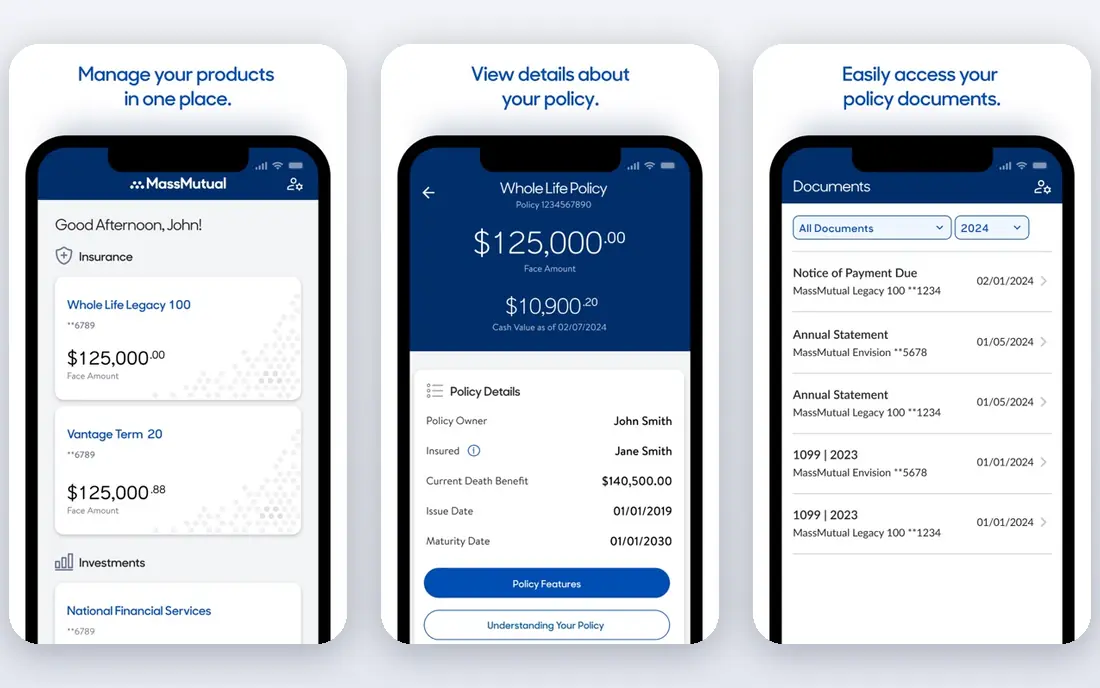
MassMutual is a policyholder-owned mutual company founded in 1851, with an A++ rating from AM Best in recent comparisons and a conservative investment approach. Its fixed annuities are described by advisers as among the most stable, ideal for clients who do not want surprises, though that stability can come with lower rates than carriers chasing market share. The company also offers income annuities with a wide menu of payout options, including period-certain terms in some products.
For a saver who wants a long-lived mutual insurer behind a multi-year guarantee, MassMutual is a strong fit. The main catch is process: expect an agent conversation to work through product choice, state variations, and payout options, rather than a quick online checkout. That conversation is worth having for a contract that may last five to ten years.
- A++ rating from AM Best in recent comparisons
- Policyholder-owned mutual structure
- Conservative investment approach
- Rates may trail less established carriers
- Product details often require an agent conversation
Pacific Life offers fixed, immediate, indexed, variable, and registered index-linked annuities directly to consumers by website or phone, which reduces reliance on an intermediary for some buyers. It holds an A+ rating from AM Best in recent comparisons, with a long history as a policyholder-owned insurer. Its income annuity products include optional annual inflation increases in some designs, which can matter for retirees worried about purchasing power over decades.
The catch is minimums. Fixed annuity minimum premiums at Pacific Life tend to be higher than most competitors, reported around $25,000 in some comparisons, so smaller savers may need another carrier. Product breadth is the draw here: a buyer who wants to compare fixed, indexed, and income options from one strong insurer will find Pacific Life useful.
- Fixed, immediate, indexed, variable, and registered index-linked annuities
- Direct purchase options
- Low complaint rates noted in comparisons
- Fixed annuity minimum premiums tend to be higher than many competitors
- Terms vary by product
Nationwide is a mutual company celebrating its centennial in 2026, with an A+ rating from AM Best in recent comparisons. Its income annuity products stand out for a low $10,000 minimum in some listings, plus cost-of-living adjustment options up to 5 percent and an emergency liquidity feature in one product. That low minimum opens income annuities to savers who cannot meet higher thresholds elsewhere.
The breadth of Nationwide products means a buyer must compare carefully. Fixed deferred, indexed, and income annuities have different surrender periods, withdrawal rules, and rider costs, and the best term for one saver may be a poor fit for another. For a saver who wants a lower entry point and flexible income options from a large mutual insurer, Nationwide deserves a quote.
- A+ rating from AM Best in recent comparisons
- Income annuity with low $10,000 minimum in some listings
- Cost-of-living options
- Product range is broad, so fixed terms need careful comparison
- Some features are rider-dependent
Allianz Life holds an A+ rating from AM Best in recent comparisons and offers both fixed annuities and fixed indexed annuities. Fixed indexed annuities link growth to a market index, such as the S and P 500, with caps, spreads, or participation rates shaping the return, while protecting principal from market loss in a negative year. That structure appeals to savers who want some upside without direct market risk.
The complexity is the catch. Caps and participation rates change the effective return in ways a headline index gain does not show, and surrender periods and rider fees add further terms to check. Allianz suits a saver who understands indexed mechanics and wants a large insurer behind the contract. Get the full index, cap, and surrender terms in writing before comparing Allianz with a plain fixed rate.
- A+ rating from AM Best in recent comparisons
- Fixed and fixed indexed annuities
- Strong indexed product range
- Indexed caps, spreads, and participation rates need careful reading
- Rates vary by state
Athene ranked first by 2025 fixed-rate deferred annuity sales in LIMRA-based rankings cited in recent guides, with $17.55 billion in sales, ahead of New York Life and MassMutual. It holds an A+ rating from AM Best in recent comparisons. That sales volume signals competitive fixed rates and broad distribution through agents and brokers, even if the Athene name is less familiar to retail buyers than older mutual brands.
The trade-off is channel variation. Rates, minimums, and surrender terms can differ by broker and state, so a single advertised rate does not tell the whole story. Athene suits a saver who is comparing fixed rates across carriers through an independent broker and who wants a high-volume fixed annuity issuer in the mix. Always confirm the issuing insurer and the exact contract terms for your state.
- Largest fixed-rate deferred annuity sales in 2025 in LIMRA-based rankings
- A+ rating from AM Best
- Broad fixed product range
- Rates and terms vary by distribution channel
- Brand is less familiar to some retail buyers than mutual giants
Lincoln Financial is a top-10 US annuity seller with a long history, and its income annuity products offer one of the broadest payout menus available in some comparisons. That flexibility helps retirees who want a specific payout shape, such as a period-certain term or a joint-life option, rather than a single standard income stream. Lincoln also offers fixed, indexed, and variable annuities for different risk preferences.
The rating is the watch point. AM Best rates Lincoln A in recent comparisons, following a downgrade that has since stabilized, which is still a strong rating but below the A++ tier. Some fixed products also carry market value adjustment clauses that affect early withdrawals. Lincoln suits a buyer who values payout flexibility and is comfortable weighing a strong but not top-tier rating against contract features.
- Top-10 US annuity seller
- Broad payout menus for income products
- Long history in annuities
- AM Best rating of A in recent comparisons, below A++ rivals
- Some products carry market value adjustment terms
Prudential Financial is one of the largest US life insurers by assets, with an A+ rating from AM Best in recent comparisons. It still issues a retail immediate income annuity, though its marketing today centers more on buffered and indexed products. That range suits a saver who wants to compare a plain fixed annuity with an indexed or buffered alternative from the same large insurer.
The catch is focus. A buyer seeking a simple multi-year guaranteed annuity should ask specifically for fixed deferred terms, surrender periods, and minimums, rather than assuming the most promoted product is the fixed one. Prudential is a solid quote to include when comparing large insurers, especially for buyers who already hold other Prudential products.
- A+ rating from AM Best in recent comparisons
- Very large insurer by assets
- Range of fixed, indexed, and buffered products
- Retail marketing now centers on buffered and indexed products
- Fixed terms need direct comparison
Guardian Life holds an A++ rating from AM Best in recent comparisons, placing it in the top financial strength tier alongside New York Life, MassMutual, and Northwestern Mutual. As a mutual company, it is owned by policyholders rather than shareholders, which aligns with the conservative approach many fixed annuity buyers prefer. Its annuity range sits alongside a strong whole life heritage, which matters for buyers planning across retirement and estate needs.
The limitation is scale in fixed annuities. Guardian fixed annuity sales are smaller than the largest fixed sellers, and distribution is often agent-led, so online comparison is thinner. For a saver who prioritizes top-tier strength and a mutual structure, Guardian is worth a quote, even if the headline fixed rate is not the highest in the market.
- A++ rating from AM Best in recent comparisons
- Mutual company structure
- Strong whole life and annuity heritage
- Fixed annuity sales volume is smaller than Athene or New York Life
- Distribution is often agent-led
How we picked these
We compared recent fixed annuity sales rankings, financial strength ratings from AM Best and other agencies, and official product ranges for major US insurers. We favored companies with strong ratings, current fixed annuity offerings, and a product range that covers fixed deferred and income needs. We used See website for pricing, since annuity rates vary by state, term, and date and are not promised in this guide. We did not claim hands-on testing, and we framed this guide as a comparison based on publicly reported factors, not a verified ranking.
What to check before you buy a fixed annuity
Start with the contract, not the rate. Confirm the guaranteed rate, the term length, the surrender period, and the surrender charges year by year. A multi-year guaranteed annuity that locks money for seven years is a different commitment from a three-year term, even if the longer term shows a higher rate. Also check free withdrawal terms, since many contracts allow a set percentage withdrawal each year without a charge.
Next, check the insurer and the issuing company. Ratings apply to a specific issuing insurer, not just a brand name, so confirm which company issues your contract and its current rating. Check state guaranty association coverage and limits for your state, since that coverage caps protection if an insurer fails. Then check tax treatment: fixed annuities grow tax-deferred, but withdrawals are generally taxed as income, and early withdrawals before age 59 and a half may face a tax penalty, so discuss tax with a qualified adviser.
Finally, compare at least three quotes for the same term and state, and ask each provider for a current rate sheet with an effective date. Rates move, and a rate quoted last month may not hold. Never buy on a single advertised rate without reading surrender, market value adjustment, and rider terms, and never assume a rate is guaranteed beyond the stated term.
Frequently asked questions
What is the best company for annuities?
There is no single best company for every saver. New York Life and MassMutual lead on financial strength ratings, Athene leads on recent fixed annuity sales volume, and Pacific Life, Nationwide, and Allianz Life offer strong product ranges. Compare the actual contract rate, term, and surrender terms for your state before choosing.
What is a fixed annuity?
A fixed annuity is a contract with an insurer that pays a guaranteed interest rate for a set term, with tax-deferred growth. Multi-year guaranteed annuities work much like CDs, but with insurer backing and different surrender rules. After the term ends, the rate may reset, and the contract may renew or allow withdrawal depending on its terms.
Are fixed annuity rates guaranteed?
The rate is guaranteed only for the stated term in the contract, such as three, five, or seven years. After that term, the insurer may set a new rate, subject to any minimum guaranteed rate in the contract. Always confirm the term, the renewal terms, and the minimum rate in writing, since advertised rates change with market conditions.
How do I check an annuity company's financial strength?
Check ratings from AM Best, S and P, Moody's, and Fitch for the specific issuing insurer, not just the brand. AM Best ratings from A++ to A- indicate strong ability to meet obligations, with A++ as the highest. Also check state guaranty association limits, since they cap protection if an insurer fails.
What is the minimum to buy a fixed annuity?
Minimums vary by company and product. Some income annuities start at $10,000, while some fixed deferred products start at $5,000 or $10,000, and Pacific Life fixed minimums tend to be higher, around $25,000 in some comparisons. Confirm the minimum for the exact product and state before applying.
Is a fixed annuity better than a CD?
A fixed annuity and a CD both offer a set rate for a set term, but they differ in backing, tax, and access. CDs are bank products with FDIC insurance up to limits, while annuities are insurer contracts with state guaranty coverage and tax-deferred growth. Annuities often carry longer surrender periods and different withdrawal rules, so compare term, rate, insurance, and tax together.
Sources
- https://www.annuityexpertadvice.com/best-annuities/
- https://myannuitystore.com/annuities/best-fixed-annuity-companies/
- https://www.insuredbetter.com/annuities/life-insurance-annuity/insurance-companies/
- https://www.newyorklife.com
- https://www.massmutual.com
- https://www.pacificlife.com
- https://www.nationwide.com
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 wpforms alternatives
Best WPForms Alternatives in 2026
We compare 9 wpforms alternatives for WordPress forms, with free and paid options, current pricing notes, and honest limits for small business sites in 2026.
Read → windows task scheduler alternatives
Best Windows Task Scheduler Alternatives in 2026
Looking for Windows Task Scheduler alternatives? We compare 9 schedulers for Windows and cross-platform work, from free tools to enterprise automation.
Read → which ai video service is best
Which AI Video Service Is Best in 2026
which ai video service is best? We compare 10 legitimate AI video services on price, avatars, editing and output quality to help you pick the right tool.
Read →