 ProMapRanker
Best Fiduciary Investment Companies in 2026

low-cost human advice · Pricing starts at: 0.30% per year
Key takeaways
- A fiduciary must act in your best interest, but the fee model still matters, so check whether you pay a percentage of assets, a flat fee, or a monthly subscription.
- Vanguard Personal Advisor and Schwab Intelligent Portfolios Premium are the cheapest routes to human advice for many investors, while Facet suits people who want a flat fee that does not rise with their balance.
- Betterment Premium and Fidelity Go work well for smaller balances, while Empower and Edelman Financial Engines fit larger, more complex portfolios.
- This is not financial advice. Fees, minimums, and terms vary, and investing carries risk, including possible loss of principal.
- Always confirm a firm's fiduciary status, fee schedule, and conflicts of interest in its disclosure brochure before you move money.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
| Vanguard Personal Advisor | low-cost human advice | 0.30% per year | No | Visit |
 Schwab Intelligent Portfolios Premium | flat-fee planning at scale | $30 per month | No | Visit |
 Facet | flat-fee planning with no asset minimum | $2,600 per year | No | Visit |
 Betterment Premium | automated investing plus advisor calls | 0.65% per year | No | Visit |
 Empower Personal Strategy | larger portfolios with dedicated advisors | 0.89% per year | No | Visit |
 Fidelity Go | low-cost coaching for smaller accounts | Free | Yes | Visit |
 Edelman Financial Engines | workplace and retirement planning | See website | No | Visit |
 Merrill Guided Investing | bank customers who want guided investing | 0.45% per year | No | Visit |
 Garrett Planning Network | hourly, as-needed advice | See website | No | Visit |
The best fiduciary investment companies
We compared fee models, minimums, advisor access, and planning scope, using official pricing pages, disclosure summaries, and public reviews. The firms below all offer fiduciary advice in their advisory programs, though the exact service, and the person you speak with, can differ by plan.
Vanguard Personal Advisor pairs automated portfolio management with access to human advisors, and its headline net advisory fee of about 0.30% per year for typical portfolios is hard to beat for this level of help. Clients get a financial plan, ongoing portfolio management, and advisor contact for questions about retirement, college saving, and other goals. The service is a strong fit for investors who already trust low-cost index funds and do not need a boutique planning experience.
The catch is the entry point. You need $50,000 to enroll in the main Personal Advisor service, and the portfolios are built from Vanguard funds, so you will not get a hand-picked mix of outside fund families. Vanguard does not prepare tax returns as part of this service. For a large balance, the tiered fee gets cheaper.
- Low advisory fee for human advice
- Access to advisors for planning questions
- Fees fall at higher balances
- $50,000 minimum for the main service
- Portfolios use Vanguard funds
- No tax filing service
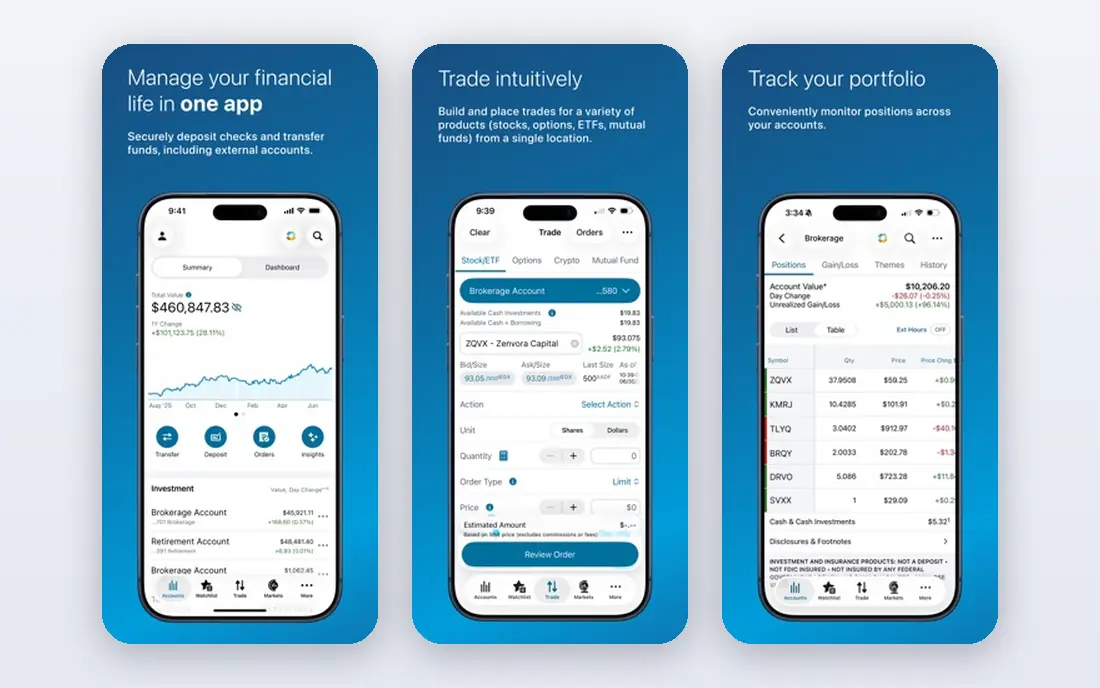
Schwab Intelligent Portfolios Premium adds a team of certified financial planners to Schwab's automated investing service, for a $300 one-time planning fee plus $30 per month. That flat structure is the main appeal. On a $25,000 account the fee is a large share of assets, but on a $250,000 account it is a small share, which makes Premium cheaper than percentage-based rivals as balances rise. Clients get a personalized financial plan, goal tracking, and ongoing portfolio management.
The trade-off to weigh is the cash allocation. Schwab portfolios hold a portion in cash in FDIC-insured deposit accounts, and Schwab Bank earns income on those deposits. Cash can lower returns in strong stock markets compared with a fully invested portfolio, and some cash alternatives outside the program pay a higher yield. Premium uses a team model rather than a single dedicated advisor for every client.
- Flat monthly fee after a one-time planning fee
- Unlimited access to certified financial planners
- Automated investing and rebalancing
- $25,000 minimum
- $300 initial planning fee
- Portfolios include a cash allocation that can drag on returns
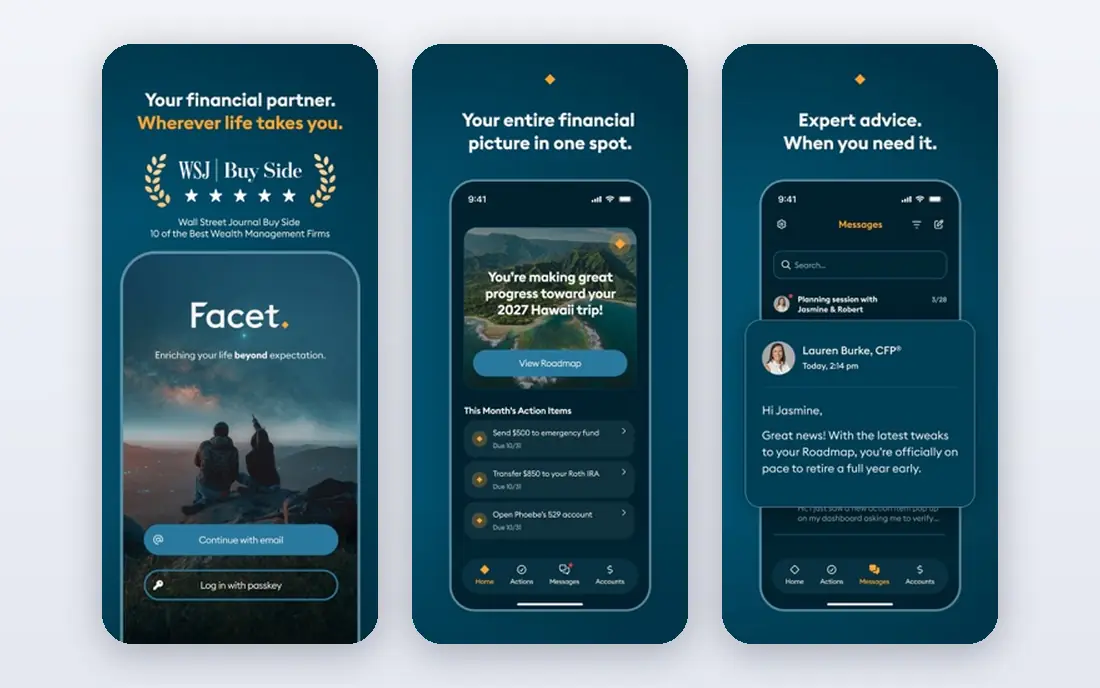
Facet charges a flat annual membership fee based on the complexity of your situation, starting at $2,600 per year for its Core tier in published 2026 pricing, with higher tiers for more complete planning and tax help. That model suits people whose balances are growing, because the fee does not climb just because the portfolio did. All of its planners are certified financial planner professionals, and Facet states that they act as fiduciaries for members.
The service is delivered entirely online by video and phone. Meeting counts vary by tier, so read the details before you sign up, especially if tax filing matters. Facet is best for professionals and couples who want ongoing planning and investment management in one subscription, without a percentage fee.
- Flat fee that does not rise with your balance
- Certified financial planners who act as fiduciaries
- Planning covers retirement, tax, insurance, and estate topics
- Fully virtual, with no in-person meetings
- Higher tiers are needed for tax filing help
- You are matched to a planner rather than choosing one yourself
Betterment Premium builds on Betterment's automated investing service by adding unlimited access to certified financial planners, at 0.65% per year on the first $1 million. The base automated service charges 0.25% per year, and Premium adds 0.40% for the human advice layer. Portfolios use low-cost exchange traded funds, and taxable accounts get tax-loss harvesting and tax-coordinated placement of assets across account types.
Premium makes sense if you like automation but want a real person to call when life changes, such as a job move, a home purchase, or a retirement decision. The $100,000 household minimum for Premium is the main barrier, and at very large balances the percentage fee becomes expensive compared with a flat fee from Schwab or Facet. Betterment has no branch network, so advisor conversations happen by phone or video.
- Unlimited calls with certified financial planners at the Premium tier
- Daily tax-loss harvesting on taxable accounts
- No separate planning fee
- $100,000 minimum for Premium
- Premium fee is higher than Vanguard and Schwab Premium at larger balances
- No in-person advice
Empower Personal Strategy, formerly Personal Capital's advisory service, combines automated investing with human advisors, starting at 0.89% per year for the first $1 million, with lower rates at higher balances. At higher tiers, clients get two dedicated advisors, individual stock holdings for more granular tax-loss harvesting, and specialist help for stock options, real estate, and other complex holdings. The free Empower dashboard for net worth tracking and fee analysis remains available to anyone, even without the managed service.
The fee is the obvious drawback. At 0.89%, Empower costs far more than Vanguard, Schwab Premium, or Betterment for a similar core portfolio, so the value has to come from the planning and tax work, not from the investments alone. The entry tier uses a team of advisors rather than dedicated advisors, so ask what you get at your balance. Empower fits best above $250,000, with tax or equity compensation questions.
- Dedicated advisors at higher tiers
- Individual stock portfolios for finer tax-loss harvesting
- Free dashboard tools for tracking net worth
- $100,000 minimum for managed portfolios
- Fee is high compared with robo-advisors
- Entry tier uses a team model rather than dedicated advisors
Fidelity Go is Fidelity's automated investing service, and it is free for balances under $25,000, then charges 0.35% per year at $25,000 and above. Once you reach $25,000, you also get unlimited 30-minute coaching calls, which makes Fidelity Go one of the cheapest ways to talk with a professional about your plan. The service builds diversified portfolios from Fidelity Flex funds, and it supports taxable accounts, IRAs, and health savings accounts.
Coaching is not a full planning relationship. Calls help with goals and portfolio questions, but not with a comprehensive ongoing plan. Fidelity Go also has no dedicated advisor, and the coaching model suits people who are comfortable managing most decisions themselves. For a first managed account, or a smaller IRA, the free entry point is genuinely useful.
- No advisory fee under $25,000
- Coaching calls at $25,000 and above
- Accounts include IRAs and health savings accounts
- Coaching is narrower than ongoing planning
- 0.35% fee applies at $25,000 and above
- No dedicated advisor relationship
Edelman Financial Engines
Great for: workplace and retirement planning
Edelman Financial Engines is one of the largest independent financial planning firms in the United States, and it is best known for retirement planning and for advice delivered through employer retirement plans. Clients can get a financial plan, investment management, and retirement income planning, with advisors who act as fiduciaries in the firm's advisory services. The scale of the firm means it can support clients through retirement transitions, Social Security decisions, and income planning in a structured way.
Pricing transparency is the main frustration. Edelman does not publish one simple starting price, and your fee can depend on a workplace plan or direct enrollment. Ask for a written fee schedule before enrolling. Edelman is a strong choice for people approaching retirement who want a well-established firm with deep retirement expertise.
- Large advisor network with retirement planning depth
- Workplace retirement plan advice for many employers
- Fiduciary advice in its advisory programs
- Pricing is not published as a single simple rate
- Service levels vary by employer plan and account type
- Minimums vary
Merrill Guided Investing offers automated portfolio management at 0.45% per year, with an advisor-led version for clients who want ongoing access to a Merrill advisor. The service suits Bank of America customers who want investing, banking, and planning in one place, and who value being able to speak with an advisor at a branch or by phone. Portfolios are built around investment themes and goals, with rebalancing handled for you.
The fee sits above Vanguard, Fidelity Go, and Betterment Digital, so the case for Merrill rests on convenience and advisor access. The advisor version also requires a higher minimum. If you already bank with Bank of America and want a single relationship, Merrill is convenient. If price is your main driver, the low-cost hybrid services above will usually win.
- Guided portfolios with advisor access at the higher tier
- Integration with Bank of America accounts
- Access to Merrill research and planning tools
- Higher fee than low-cost robo-advisors
- Advisor tier requires a higher minimum
- Fund expenses apply on top of the advisory fee
Garrett Planning Network is a network of fee-only financial planners who offer hourly or project-based advice, rather than a single managed service. That model is ideal if you want a second opinion, a retirement plan, or help with one decision, without handing over your portfolio or paying a yearly percentage fee. Members state that they act as fiduciaries, and you can search by specialty, such as small business owners, educators, or retirees.
You are buying advice, not ongoing management. If you want regular portfolio management, you will need repeat sessions or a different firm. Hourly rates vary by planner. For a one-time plan, or for annual check-ins without an asset-based fee, Garrett is one of the most flexible fiduciary routes available.
- Hourly and project-based advice with no asset minimum
- Members are fee-only fiduciary planners
- You can choose a planner by specialty and location
- You pay per session or project, so ongoing help adds up
- Investment management is not included by default
- Quality varies by individual planner
How we picked these
We started from the fee model, not the brand name. For each firm, we checked its fiduciary duty, charges, minimum, and advisor access, using official pricing pages, disclosure summaries, and public reviews. We favored firms with published fees and planning beyond portfolio picks, and we did not rank firms on past returns.
What to check before you hire a fiduciary advisor
A fiduciary label is a good starting point, but the details decide whether a firm fits you. Ask these questions before you sign anything, and get the answers in writing.
Fee model and total cost
A percentage fee grows with your balance, a flat fee stays steady, and a monthly subscription can be cheap at scale but expensive on a small account. Add fund expense ratios to the advisory fee, and ask whether the fee drops at higher balances.
Advisor access and planning scope
Some services offer a team of planners, some a dedicated advisor, and some short coaching calls. Decide how much contact you want, and whether you need help with taxes, estate planning, stock options, or retirement income.
Conflicts and custody
Ask how the firm is paid, whether it earns commissions from the funds it recommends, and where your assets are held. A custodian holding your accounts separately from the advisor's own money is a basic protection.
Frequently asked questions
Who is the best financial advisor company for most people?
There is no single winner, because the best choice depends on balance, fee sensitivity, and how much human help you want. Vanguard Personal Advisor is our pick for low-cost human advice at $50,000 and above, while Schwab Premium suits larger balances thanks to its flat fee. For smaller accounts, Fidelity Go offers a free start and coaching at $25,000.
Are the best financial advisors companies always fiduciaries?
No, and that is why the label matters. A fiduciary advisor must act in your best interest, while a broker working under a looser standard may recommend a suitable product that pays them more. Always ask whether the person advising you is acting as a fiduciary for your account, and read the firm's disclosure brochure for exceptions.
What is the difference between the best financial planner companies and the best money management companies?
Financial planning companies focus on goals, taxes, retirement, and estate topics, while money management companies focus mainly on building and managing a portfolio. Many firms on this list do both, but the balance differs. Facet and Garrett lean toward planning, while Betterment and Fidelity Go lean toward managed portfolios with planning support.
How much do the best financial management companies charge?
Fees range from free under $25,000 at Fidelity Go, to about 0.30% per year at Vanguard, to $30 per month at Schwab Premium, to 0.89% per year at Empower for smaller managed balances. Flat-fee firms such as Facet charge by complexity rather than assets. Compare the total cost, including fund expenses, at your actual balance.
Can I switch fiduciary advisors without selling everything?
Often yes, especially if you move accounts in kind to a new custodian, which transfers holdings without selling them. Some proprietary funds or managed portfolios cannot transfer directly, so ask both firms what transfers in kind and what would need to be sold. Selling in a taxable account can trigger capital gains tax, so plan the timing with care.
Do I need a financial advisor if I use index funds?
Not always. If your finances are simple, a diversified index portfolio and a clear savings habit may be enough. An advisor adds more value when taxes, stock options, business income, retirement withdrawals, or estate questions make decisions harder. An hourly planner from Garrett can be a cheaper way to get that help without an ongoing fee.
Sources
- https://www.vanguard.com
- https://www.schwab.com
- https://facet.com/faqs/
- https://www.betterment.com
- https://www.empower.com
- https://www.fidelity.com
- https://www.edelmanfinancialengines.com
- https://www.ml.com
- https://www.garrettplanningnetwork.com
- https://www.nerdwallet.com/financial-advisors/reviews/vanguard-personal-advisor-services
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 which software is best for pdf page removal
Which Software Is Best for PDF Page Removal in 2026
Find which software is best for pdf page removal, from free online tools to desktop editors, with page controls, privacy, safety, and pricing compared.
Read → when i work alternatives
Best When I Work Alternatives in 2026
Looking for when i work alternatives? We compare 8 scheduling apps for hourly teams, covering pricing, free plans, time clocks and the best fit for business.
Read → the best tool for keyword analysis
The Best Tool for Keyword Analysis in 2026
Find the best tool for keyword analysis with our 2026 comparison of 10 keyword analysis software tools on data depth, difficulty scores and price today.
Read →