 ProMapRanker
Best 401k Companies in 2026

Broad choice and support · Pricing starts at: See website
Key takeaways
- This is not financial advice; fees and employer plans vary, and the right provider depends on company size, payroll setup and investment choice.
- Fidelity, Vanguard and Charles Schwab suit many employers and solo savers, with broad fund ranges and low-cost index options.
- Guideline and Human Interest suit small businesses that want automated administration and clear monthly pricing.
- Empower and Principal suit larger employers that need planning tools, advice support and a wide service range.
- Always compare total cost, including recordkeeping, advisory and fund fees, not just the headline monthly charge.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
| Fidelity Investments | Broad choice and support | See website | No | Visit |
 Vanguard | Low-cost index funds | See website | No | Visit |
 Charles Schwab | Flexible brokerage plans | See website | No | Visit |
 Empower | Planning tools at scale | See website | No | Visit |
 Guideline | Automated small-business plans | See website | Free trial | Visit |
 Human Interest | Small-business automation | $80 per month | No | Visit |
 ADP Retirement Services | Payroll-linked plans | See website | No | Visit |
 Principal Financial Group | Larger employer plans | See website | No | Visit |
 T. Rowe Price | Active and target-date funds | See website | No | Visit |
The best 401k companies
These nine providers cover solo plans, small-business plans and larger employer plans, with different strengths on fees, funds and administration.
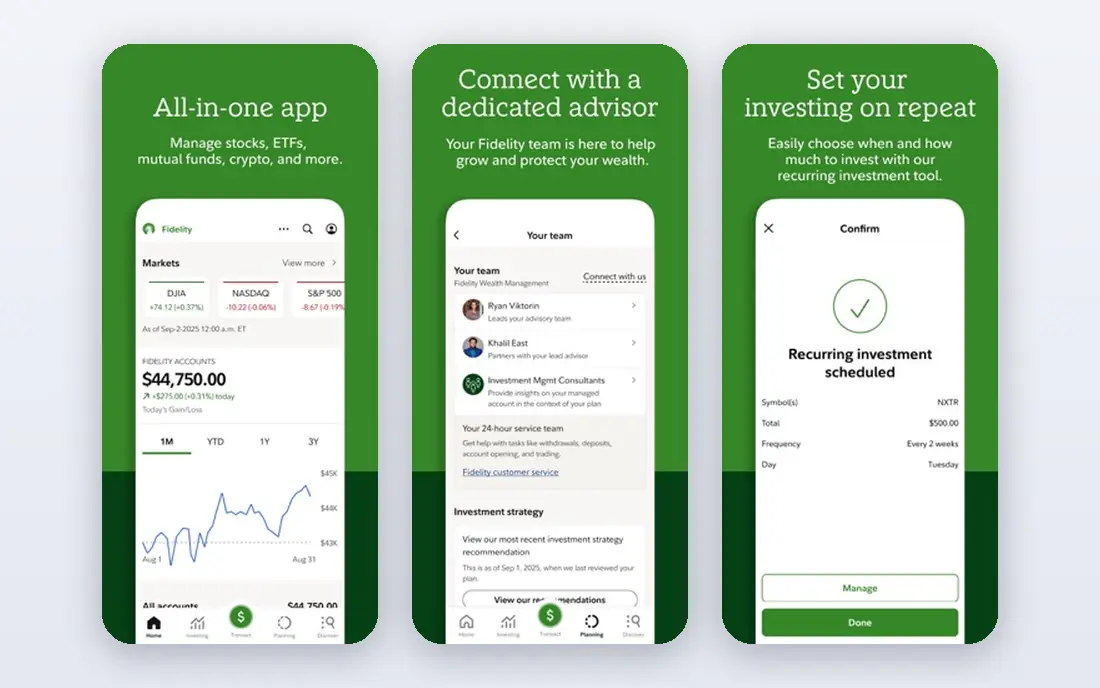
Fidelity is the largest 401k recordkeeper in the United States by assets under administration in recent comparisons, and that scale shows in its platform. Employers can offer index funds, target-date funds, actively managed funds and, in some plans, brokerage options. Employees get planning tools, educational material and support that covers many common questions without a separate adviser.
The main drawback for an employer is that total plan pricing is not a single public number. Recordkeeping, advisory and fund fees depend on plan size, design and services chosen, so you need a written quote. For a solo saver, Fidelity also offers solo 401k options with traditional and Roth contributions, although loan options are limited in its solo plan. Get the full fee schedule in writing before you sign.
- Very broad fund and brokerage choice
- Strong planning tools
- Wide support hours
- Employer plan pricing is quoted, not listed
- Fund menu varies by employer plan
Vanguard built its reputation on low-cost index funds, and that remains its clearest strength for retirement savers. Its target-date funds give employees a simple default choice, while its index funds keep ongoing fund costs low for people who prefer to build their own mix. For cost-focused savers, that combination is hard to ignore.
Employer plans need a closer look at administration. Vanguard works with partners for some small-business plan administration, so the service experience can differ from the retail investing experience. Ask who handles payroll links, compliance testing and employee support, and confirm fund fees for the exact funds in your plan menu. The investment case is strong; the administration case depends on the partner arrangement.
- Low-cost index fund heritage
- Clear target-date options
- Investor-owned structure
- Employer plan administration may run through partners
- Platform feels plain to some users
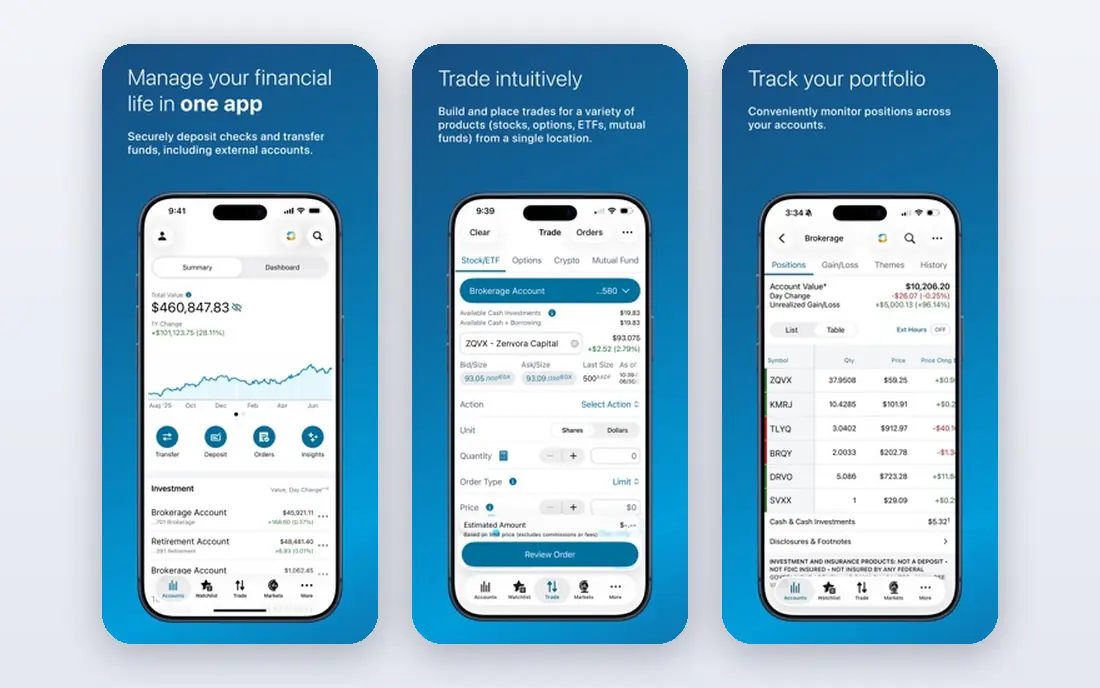
Charles Schwab suits employers and solo savers who want a brokerage platform behind the retirement plan. Employees can access a wide fund range, and the wider Schwab platform offers research, education and planning tools that many savers already know. Solo 401k plans have been listed with no setup or annual fee, which helps a self-employed saver keep costs down.
The solo plan trade-offs matter. Recent comparisons note no loan option and a more manual administration process than some digital-first rivals. Employer plans are quoted, so total cost depends on plan design. Schwab is a good fit if you value brokerage flexibility and a large, established platform, and a weaker fit if you want a fully automated small-business plan with loans.
- Broad brokerage access
- No setup or annual fee on solo plans in recent guides
- Good education
- Solo plan administration can feel paper-based
- No loan option in its solo plan in recent guides
Empower is one of the largest 401k recordkeepers, and its platform puts weight on employee engagement. Planning tools, retirement income projections and educational content aim to help employees understand what their savings might mean in retirement, not just what their balance is today. Larger employers also get a wide range of plan services and support structures.
Smaller employers should check whether that scale fits their budget and service needs. Pricing is quoted by plan, and the full service range may be more than a ten-person company needs. If your priority is employee engagement and you run a mid-size or large plan, Empower belongs on the shortlist. If you run a very small plan, compare its quote with Guideline and Human Interest first.
- Strong engagement and planning tools
- Large recordkeeper scale
- Wide plan range
- Pricing is quoted
- Smaller employers may find the platform larger than they need
Guideline is built for small businesses that want a 401k without hiring a benefits team to run it. Administration, compliance support and payroll links are central to the offer, and dashboards make participation and contributions easy to follow. That automation is the main reason small employers choose it over a large recordkeeper with a quoted, custom process.
The trade-off is investment breadth. Guideline plans use a curated fund menu rather than the open brokerage choice that Fidelity or Schwab can offer in some plans. For most employees, a curated menu with low-cost index and target-date options is enough, and it reduces decision overload. If your team wants wide brokerage access or alternative investments, Guideline may feel narrow.
- Automated administration and compliance support
- Clear dashboards
- Payroll links
- Investment menu is narrower than a full brokerage plan
- Pricing varies by tier
Human Interest lists its Essentials plan from $80 per month plus $5 per eligible employee, with a one-time setup fee that may apply, and asset-based recordkeeping and advisory fees described on its pricing page. That transparency helps a small employer model costs before a sales call. The company also lists many payroll integrations, which matters because payroll errors are a common source of plan admin pain.
Costs still need a full reading. The base fee is only part of the total, since per-employee charges and asset-based fees add to it, and higher tiers cost more for added administration and support. Human Interest suits a small business that wants a managed plan with payroll sync and clear starting prices. Larger employers should compare the per-employee maths with a quoted plan from a larger recordkeeper.
- Transparent starting price
- Many payroll integrations
- Full-service administration
- Per-employee fee adds up as headcount grows
- Setup fee may apply
ADP Retirement Services makes most sense for an employer that already runs payroll with ADP. Contributions, eligibility and payroll deductions can flow through one system, which reduces manual file transfers and the errors that come with them. ADP also brings large-employer experience and a wide HR and benefits service range for companies that want bundled services.
The drawback is opacity on price. Plans are quoted, and the right package depends on payroll setup, headcount and services chosen. A company that does not use ADP payroll loses the main integration advantage and should compare ADP with Guideline, Human Interest and Fidelity on equal terms. Ask for a total cost breakdown, including fund fees, before you compare quotes.
- Strong payroll integration for ADP users
- Large employer experience
- Bundled HR services
- Pricing is quoted
- Plan experience can vary by package and payroll setup
Principal is a long-established recordkeeper with a wide range of employer plans, investment options and advice services. Larger employers benefit from its scale, plan design support and employee education resources. It also appears in recent largest-administrator lists, which reflects the volume of retirement assets it handles.
Small employers may find the process heavier than a self-serve digital plan. Pricing is quoted, onboarding can involve more steps, and the service model assumes a benefits contact at the employer. If you run a larger plan and want a traditional recordkeeper with broad services, Principal is a solid candidate. If you run a five-person plan, a digital-first provider may start faster.
- Large recordkeeper experience
- Wide investment and advice options
- Strong employer services
- Quoted pricing
- Small employers may find onboarding heavier than digital-first rivals
T. Rowe Price is known for its target-date funds and actively managed funds, and it suits employers that want that fund range alongside retirement planning tools. Its Retirement Funds series gives employees a managed default option, while its broader fund menu covers savers who want to choose their own mix. Research and education support the fund story well.
Fees need care. Actively managed funds usually cost more than index funds, so an employer should compare the fund fees in the actual plan menu, not just the provider brand. Employer pricing is quoted, so total cost depends on plan size and services. T. Rowe Price fits best when a plan sponsor values its fund management and is willing to pay attention to fund-level fees.
- Strong target-date and active fund range
- Respected research
- Clear retirement tools
- Quoted employer pricing
- Active fund fees can exceed index fund fees
How we picked these
We compared large recordkeepers, small-business specialists and payroll-linked providers using official plan pages, recent administrator comparisons and public pricing pages. We favoured providers that are live today, serve US employers or solo savers, and publish clear information about plan types, payroll links and fund choice. Where a provider quotes rather than lists employer pricing, we say See website rather than invent a number. This article is general information only and is not financial advice.
How to compare 401k providers without getting lost in fees
Start with plan type. A solo 401k, a SIMPLE 401k, a safe harbor 401k and a traditional 401k have different rules, contribution limits and testing needs, so confirm which type fits your business before you compare brands. For 2026, recent guides list a $24,500 employee deferral limit and a $72,000 combined limit, with higher catch-up amounts for older savers, but confirm current IRS limits for your tax year before you rely on them.
Total cost, fund choice and support
Ask each provider for three numbers: the employer recordkeeping charge, any advisory charge, and the fund expense ratios in the proposed menu. A low monthly fee with high fund fees can cost employees more than a higher monthly fee with low-cost index funds. Also check payroll integration, compliance testing, Form 5500 support, loan and hardship rules, Roth availability and employee support hours. A short demo with your actual payroll setup will reveal integration gaps faster than a brochure.
Frequently asked questions
What is the best 401k company?
There is no single best 401k company for every employer. Fidelity, Vanguard and Schwab suit many savers on fund choice and cost, while Guideline and Human Interest suit small businesses that want automated administration. The best company for your firm is the one that fits your headcount, payroll system, fund preferences and total fee budget.
Which 401k company is best for small businesses?
Guideline and Human Interest are strong small-business options because they automate administration and publish clearer starting prices than quoted recordkeepers. Fidelity and Schwab also offer solo and small-business plans with broad investment choice. Compare total cost at your actual headcount, including per-employee and asset-based fees.
What is the best 401k company for a solo plan?
Fidelity, Schwab and E*TRADE are often cited for solo 401k plans because they offer traditional and Roth contributions with broad investment choice and, in recent guides, no setup or annual fee. Check loan rules, after-tax contribution rules and rollover support, because those features differ by provider and matter for some solo savers.
How much does a 401k plan cost an employer?
It varies widely. Human Interest lists Essentials from $80 per month plus $5 per eligible employee, plus asset-based fees and a possible setup fee, while larger recordkeepers quote by plan size and services. Always ask for recordkeeping, advisory and fund fees together, and check whether new-plan tax credits apply to your business.
Are 401k fees the same for every employee?
No. Some fees are paid by the employer, some are deducted from employee accounts, and fund fees depend on the funds each employee chooses. A plan menu with low-cost index funds can keep employee costs down even when the employer pays a modest recordkeeping fee. Ask for a fee disclosure that shows both employer and employee charges.
Can employees choose their own investments in a 401k?
Employees usually choose from the fund menu their employer sets, which often includes target-date funds, index funds and bond funds. Some plans add a brokerage window that allows wider choice. If wide choice matters to your team, confirm whether the provider offers it and what extra fees or rules apply.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 which software is best for pdf page removal
Which Software Is Best for PDF Page Removal in 2026
Find which software is best for pdf page removal, from free online tools to desktop editors, with page controls, privacy, safety, and pricing compared.
Read → when i work alternatives
Best When I Work Alternatives in 2026
Looking for when i work alternatives? We compare 8 scheduling apps for hourly teams, covering pricing, free plans, time clocks and the best fit for business.
Read → the best tool for keyword analysis
The Best Tool for Keyword Analysis in 2026
Find the best tool for keyword analysis with our 2026 comparison of 10 keyword analysis software tools on data depth, difficulty scores and price today.
Read →