 ProMapRanker
Best Afterpay Alternatives in 2026

Key takeaways
- Klarna suits shoppers who want several plan types in one app, while Affirm suits larger purchases with longer terms.
- Sezzle and Zip suit short pay in 4 plans, with Sezzle offering rescheduling features that help when income timing shifts.
- PayPal Pay Later suits shoppers who already use PayPal, and Splitit suits shoppers who prefer to use an existing credit card limit.
- Buy now pay later is credit, so missed payments can mean fees and harm to your credit record, and terms vary by provider and plan.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 Klarna | Flexible plan types | See website | No | Visit |
 Affirm | Longer financing | See website | No | Visit |
 Sezzle | Short pay in 4 plans | See website | No | Visit |
 Zip | Pay in 4 almost anywhere | See website | No | Visit |
 PayPal Pay Later | PayPal checkout | See website | No | Visit |
 Splitit | Existing card limit | See website | No | Visit |
 Shop Pay Installments | Shopify checkout | See website | No | Visit |
 Uplift | Travel financing | See website | No | Visit |
 Perpay | Paycheck based plans | See website | No | Visit |
The best afterpay alternatives
We compared official product pages for buy now pay later services that are live in the US in October 2026. Afterpay itself is not listed here, since this article covers alternatives to it. This is general information only, not financial advice. Buy now pay later is credit, and missed payments can mean fees and harm to your credit record, so check the terms for each plan before you confirm.
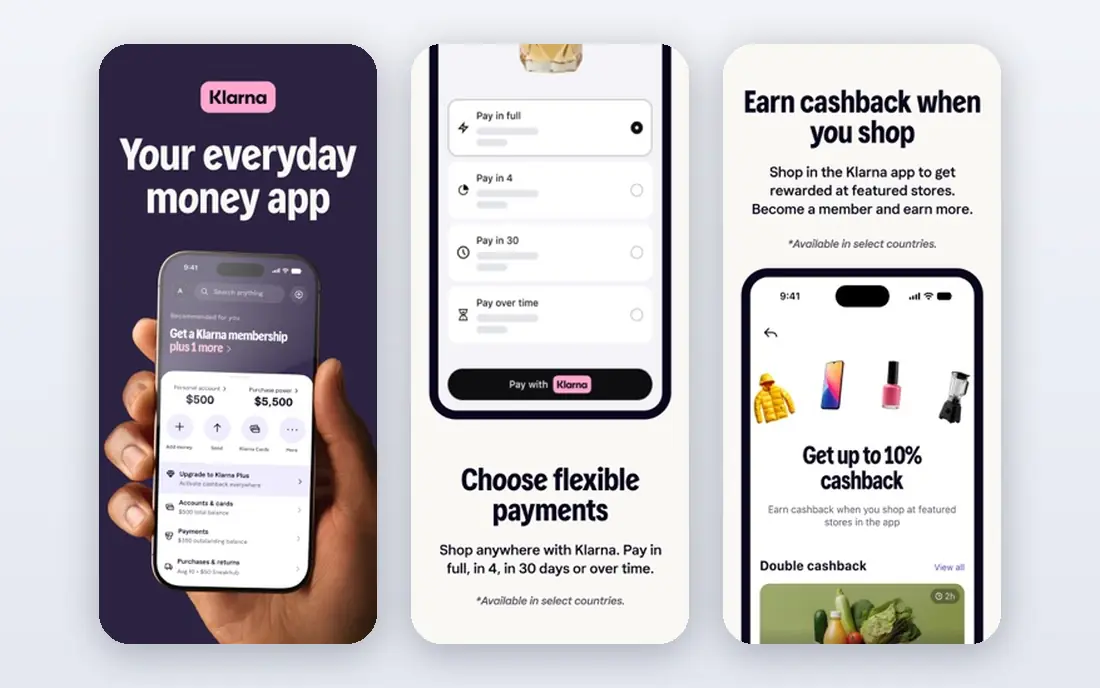
Klarna is the most flexible alternative in this list because it offers more than one way to pay later. Short pay in 4 plans suit everyday purchases, pay in 30 days suits shoppers who want a short delay without installments, and longer financing suits larger purchases that need more time. The shopping app and browser extension also let you use Klarna at merchants beyond its direct partners in some cases.
That flexibility needs care. Longer financing plans may carry interest, late fees can apply on some plans, and approval depends on the purchase and your history with Klarna. Klarna is best for shoppers who want choice and who will pay on schedule. If you only want a simple pay in 4 plan with no extra options, a simpler tool may be easier to manage.
- Pay in 4, pay in 30 days and longer financing
- Wide merchant network
- Shopping app and browser extension
- Late fees can apply
- Longer plans may carry interest
- Approval varies by purchase
Affirm suits larger purchases that do not fit a six week pay in 4 window. It offers pay in 4 plus longer monthly plans, with the APR and total cost shown before you confirm, so you can see whether a plan is interest free or interest bearing. Affirm states that it charges no late fees, which sets it apart from some rivals, although missed payments can still affect your credit record.
The trade-off is interest on longer plans, with APRs that can be high depending on the plan and your credit profile. A down payment may also be required if you do not qualify for full financing. Affirm is best for a planned large purchase where you have compared the total cost, not for stretching everyday spending across many open plans.
- Longer terms for larger purchases
- Clear APR shown before checkout
- No late fees stated by Affirm
- Interest can apply on longer plans
- May need a down payment
- Credit check varies by plan
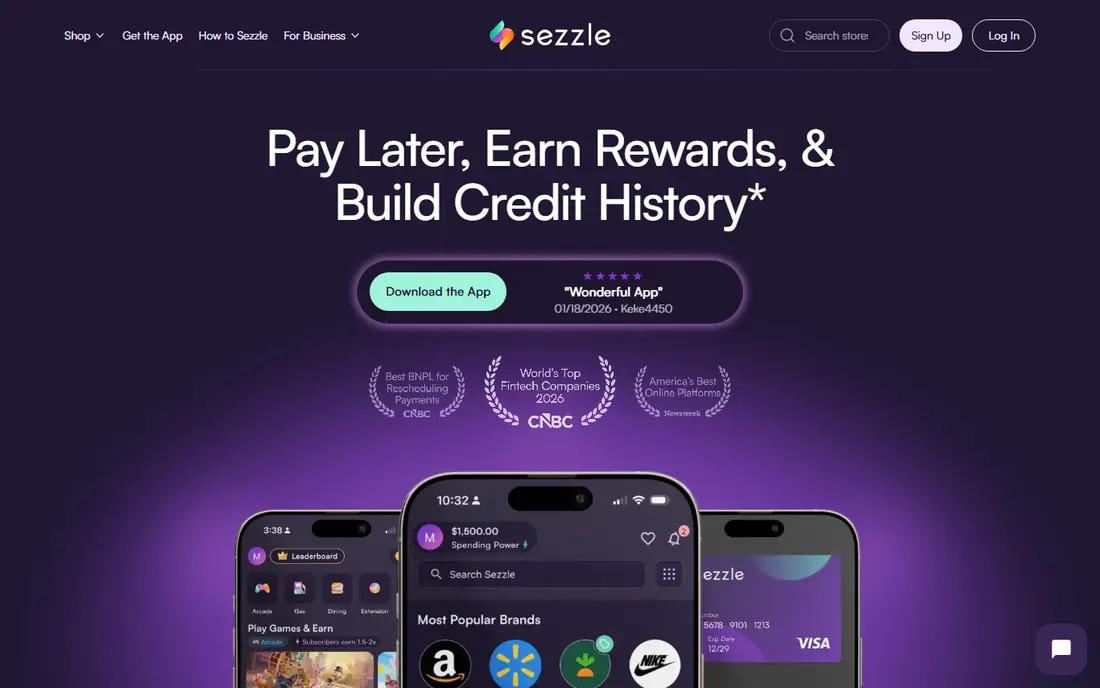
Sezzle focuses on short pay in 4 plans, with a first payment at checkout and the rest spread over about six weeks. Its rescheduling feature is the practical difference: if payday shifts, you can move a payment in the app, with one free reschedule on many plans and a small fee for later changes. That flexibility helps shoppers with irregular income avoid a missed payment.
Merchant coverage is smaller than Klarna or PayPal, so check whether your store offers Sezzle before relying on it. Sezzle also offers optional features that report payments to credit bureaus, which can help build a record when payments are on time, but missed payments can still harm credit. For simple pay in 4 use with a safety valve, Sezzle is a strong pick.
- Interest free pay in 4 on many plans
- Rescheduling features
- Optional credit reporting features
- Rescheduling beyond the free option may carry a fee
- Merchant coverage is smaller than Klarna
Zip, formerly Quadpay in the US, suits shoppers who want pay in 4 at a store that does not offer a BNPL button. Its virtual card can be used where Visa is accepted in supported cases, which widens the range of stores far beyond partner merchants. The app manages payments, reminders and the virtual card in one place.
The cost to watch is fees. Zip may charge a per order or per installment fee depending on plan and region, so a small purchase can carry a proportionally higher fee than a no-fee pay in 4 plan at a partner store. Compare the total cost for your order size. For flexibility across merchants, Zip wins. For a partner store with a no-fee plan, a direct checkout option may be cheaper.
- Virtual card works at many merchants
- Pay in 4 over six weeks
- App based management
- Per order or per installment fees can apply
- Merchant coverage varies by region
PayPal Pay Later is the easiest alternative for people who already use PayPal. Pay in 4 appears at checkout on many sites, and PayPal Credit offers a revolving credit line for larger purchases. Because the payment method is already set up, there is no new account to learn, and purchase protection rules for PayPal transactions still apply in eligible cases.
Availability is not universal. A merchant must offer PayPal, the purchase must meet eligibility rules, and longer credit plans may carry interest. PayPal Pay Later is best for occasional pay in 4 use at stores you already shop with PayPal. For a dedicated BNPL app with more plan types, Klarna or Affirm may offer more choice.
- Already present at many checkouts
- Pay in 4 with no interest on eligible plans
- No new app needed for PayPal users
- Availability depends on merchant and purchase
- Longer credit plans may carry interest
Splitit works differently from most BNPL tools. Instead of opening a new credit line, it splits a purchase into installments charged against the limit on a credit card you already hold. That means no new application in the usual sense, and Splitit itself does not charge interest on many plans, although your card issuer terms still apply if the card balance carries interest.
The limit is availability. You need enough unused card limit to cover the full purchase, and the merchant must offer Splitit at checkout. It also does not help shoppers without a credit card. Splitit is best for cardholders who want installments without a new credit account, and who will pay the card balance in a way that avoids card interest.
- Uses your existing credit card limit
- No new credit application in the usual sense
- Installments without interest from Splitit in many cases
- Needs an available card limit
- Merchant must offer Splitit
- Card interest may still apply under card terms
Shop Pay Installments suits shoppers who buy often from Shopify stores. It appears directly at checkout, offers pay in 4 and monthly installment options, and Shop Pay users can check out quickly with saved details. That integration removes the need for a separate app for many online purchases.
The obvious limit is scope. It only works at Shopify stores, so it cannot cover every merchant. Terms, including interest on monthly plans, depend on the purchase and the plan shown at checkout. For Shopify shoppers, it is a convenient alternative. For general shopping, pair it with Klarna, Zip or PayPal Pay Later for wider coverage.
- Built into Shopify checkout
- Pay in 4 and monthly plans
- Fast checkout for Shop Pay users
- Only at Shopify stores
- Terms depend on plan and purchase amount
Uplift is built for travel, not general retail. It offers monthly installment plans for flights, hotels and vacation packages sold through airlines, cruise lines and travel operators. That focus suits a large trip that needs to be spread over months rather than squeezed into a six week pay in 4 plan, and the monthly payment is shown before booking.
Uplift is not a general shopping tool, and interest can apply depending on the plan. It also only works where a travel partner offers it. For a planned trip with a clear total cost and a repayment plan you can afford, Uplift is a useful specialist option. For everyday purchases, choose a general BNPL tool instead.
- Travel focused installment plans
- Monthly payments for flights and trips
- Sold through travel partners
- Limited to travel purchases
- Interest can apply
- Approval depends on trip cost and credit profile
Perpay takes a different approach by tying payments to paycheck timing and offering shopping through its own marketplace. That structure suits workers who want predictable deductions aligned with paydays, and on-time payments may help build a credit record under Perpay terms. The marketplace includes electronics, home goods and other categories that suit larger planned purchases.
The limit is scope. Perpay shopping is centered on its marketplace, so it does not work at every store. Approval also depends on employment and income information, which is a different underwriting basis from a standard credit check. For a planned marketplace purchase with paycheck aligned payments, Perpay is worth a look. For general retail, a wider BNPL tool will fit better.
- Payments tied to paycheck timing
- Marketplace shopping
- Credit building features for on-time payments
- Limited to Perpay marketplace in many cases
- Approval based on employment and income details
How we picked these
We compared official product pages for BNPL services live in the US in October 2026, and favored services with distinct plan types, wide merchant coverage or a specialist use case. We did not claim hands-on testing, and fees, interest and credit reporting vary by plan, purchase and state, so all prices are shown as See website. Always read the plan terms shown at checkout before confirming.
How to use buy now pay later without falling behind
Count open plans, not only monthly payments. Four small plans can add up to a large monthly total, and a missed payment on one plan can trigger fees and credit harm even if other plans are current. Keep a simple list of each plan, its payment dates and its total remaining balance, and set reminders a few days before each due date.
Choose the shortest plan you can afford
A pay in 4 plan over six weeks is easier to track than a long interest bearing plan, and it usually costs less if the short plan is interest free. For a large purchase, compare the total cost of a longer plan, including interest, against saving for a shorter plan or buying a lower cost option. If you need a long plan to afford a purchase, that is a sign to reconsider the purchase itself. This is general information only, not financial advice.
Frequently asked questions
What is the best alternative to Afterpay?
Klarna is the best all round alternative for plan flexibility, Affirm is best for larger purchases, and Sezzle is best for simple pay in 4 with rescheduling. PayPal Pay Later is best if you already use PayPal. The right pick depends on where you shop and how long you need to repay.
Do Afterpay alternatives charge interest?
Some plans are interest free, especially pay in 4 plans, while longer financing plans may carry interest. Klarna longer plans, Affirm monthly plans and Uplift travel plans can all carry interest depending on terms. Always check the APR and total cost shown at checkout.
Do buy now pay later plans affect credit?
They can. Some providers report payments, some report only missed payments, and longer loans may involve a different credit check. Missed payments can mean fees and harm to your credit record, so treat every plan as credit and pay on schedule.
Which alternative is best for a large purchase?
Affirm suits larger purchases with longer monthly terms and a clear APR shown before checkout. Uplift suits large travel purchases. For a large retail purchase, compare Affirm monthly cost against Klarna longer financing and against saving for a shorter plan.
Can I use BNPL at any store?
No. Most BNPL tools work at partner merchants, although Zip virtual cards and Klarna one-time cards widen coverage in supported cases. Shop Pay Installments works only at Shopify stores, and Uplift works only through travel partners. Check coverage before you plan a purchase around a specific tool.
Is buy now pay later a good idea for everyday spending?
It can help spread a planned purchase, but it can also make spending feel smaller than it is. Use it for purchases you would buy anyway, keep the number of open plans low, and avoid using BNPL to cover regular bills you cannot otherwise afford. This is general information only, not financial advice.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 wpforms alternatives
Best WPForms Alternatives in 2026
We compare 9 wpforms alternatives for WordPress forms, with free and paid options, current pricing notes, and honest limits for small business sites in 2026.
Read → windows task scheduler alternatives
Best Windows Task Scheduler Alternatives in 2026
Looking for Windows Task Scheduler alternatives? We compare 9 schedulers for Windows and cross-platform work, from free tools to enterprise automation.
Read → which ai video service is best
Which AI Video Service Is Best in 2026
which ai video service is best? We compare 10 legitimate AI video services on price, avatars, editing and output quality to help you pick the right tool.
Read →