 ProMapRanker
Best Pay Later Apps in 2026: 8 Apps Compared

Key takeaways
- Pay in 4 plans are usually interest-free when paid on time, but longer monthly plans can carry interest up to about 36 percent APR.
- Affirm and PayPal Pay in 4 stand out for no late fees, while Klarna and Afterpay cap late fees at a share of the order in many cases.
- The best pay later app depends on the store, the purchase size and how strict the payment dates are, not on one overall winner.
- This is not financial advice. Read the plan terms at checkout, because fees, interest and credit reporting vary by plan and by state.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 Klarna | Flexible short and longer plans | Free | Yes | Visit |
 Affirm | Larger purchases and longer terms | Free | Yes | Visit |
 Afterpay | Simple Pay in 4 shopping | Free | Yes | Visit |
 PayPal Pay in 4 | Existing PayPal shoppers | Free | Yes | Visit |
 Sezzle | Budget shoppers and rescheduling | Free | Yes | Visit |
 Zip | Shopping almost anywhere with a virtual card | Free | Yes | Visit |
 Shop Pay Installments | Shopify store shoppers | Free | Yes | Visit |
 Splitit | Using an existing credit card | Free | Yes | Visit |
The best pay later apps
We compared official plan descriptions, fee pages and checkout terms for the best pay later apps, and focused on what shoppers actually pay: interest, late fees and plan length. The apps below are free to download, but the cost of a plan depends on the terms you accept, so read each offer before you confirm.
Klarna is our pick for shoppers who want more than one way to pay. Its Pay in 4 plan splits a purchase into four interest-free payments over about six weeks when paid on time. A Pay in 30 option delays the full payment, and monthly financing can stretch larger purchases over a longer term, with interest depending on credit and the merchant.
The catch is that flexibility needs discipline. Monthly plans can carry APR up to about 25 percent in published comparisons, and a late fee of up to $7 can apply in some terms, capped at a share of the order. Klarna works best when the short plan is paid on time and longer financing is used only after checking the total interest cost.
- Pay in 4, Pay in 30 and monthly financing
- Wide store coverage
- App and virtual card options
- Monthly financing can carry interest
- Late fees can apply on missed payments
Affirm suits larger purchases where four payments would be too tight. Shoppers see the interest cost and payment schedule before they commit, which makes it easier to compare a monthly plan with saving up or using another payment method. Its Pay in 4 option is interest-free at participating stores, while longer plans range from 0 percent to 36 percent APR.
Affirm states that it charges no late fees, which is a real advantage if a payment date slips. A missed payment can still affect credit reporting on some plans, and a longer term means paying more interest overall. Use Affirm for a planned purchase with a payment that fits comfortably in the budget, not for stretching a purchase that is already tight.
- No late fees
- Clear total cost shown before checkout
- Terms up to 60 months at some stores
- Monthly plans can carry APR up to 36 percent
- Approval and terms vary by purchase
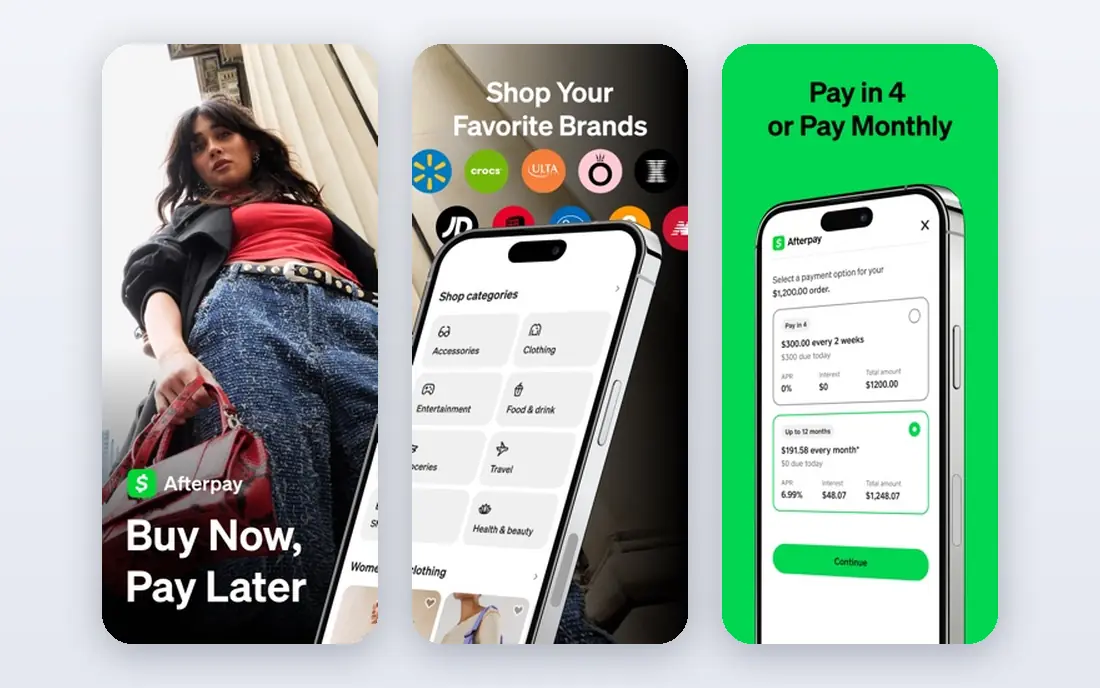
Afterpay keeps the model simple: split a purchase into four equal payments, usually every two weeks, with no interest when paid on time. That clarity makes it easy to plan, and it is widely accepted in fashion, beauty and lifestyle stores. Shoppers can also use an in-app card for in-store purchases at participating retailers.
Late fees are the main risk. Published terms describe a fee of up to $8 per missed payment, capped at 25 percent of the order in many cases. Afterpay is a good fit for a single, affordable purchase with payment dates that line up with paydays, but several open plans at once can quickly add up.
- Simple four-payment structure
- No interest on Pay in 4
- Strong fashion and beauty store coverage
- Late fees up to $8 per missed payment in many terms
- Spending limits vary
PayPal Pay in 4 is a strong choice for people who already use PayPal, because checkout is familiar and no new account routine is needed. The plan splits an eligible purchase into four interest-free payments, and PayPal states that it charges no late fees on Pay in 4. That makes the short plan easy to understand.
The limit is scope. Pay in 4 is aimed at smaller purchases, with published comparisons putting the range lower than Affirm or Klarna monthly financing. PayPal also offers monthly plans at some merchants, and those can carry interest. Check the plan type at checkout, because Pay in 4 and monthly financing are not the same offer.
- No late fees on Pay in 4
- Familiar checkout
- Works at many PayPal merchants
- Pay in 4 purchase limits are lower than some rivals
- Longer plans can carry interest
Sezzle appeals to shoppers who want a little room if a payday moves. Its Pay in 4 plan is interest-free when paid on time, and it offers rescheduling for some orders, which can help avoid a missed payment. An optional Sezzle Up feature can report on-time payments to credit bureaus for users who want to build credit history.
Fees are the detail to check. Published comparisons note service fees on some plans and late fees that vary, with caps in many cases. Sezzle is best for shoppers who read the checkout terms and use rescheduling early, rather than waiting until a payment has already failed.
- Pay in 4 with no interest when paid on time
- Payment rescheduling options
- Optional credit building
- Some fees can apply depending on plan and payment method
- Limits vary by merchant
Zip, formerly Quadpay, stands out for where it works. A virtual card lets shoppers use Pay in 4 at merchants that do not list Zip at checkout, which widens the choice beyond partner stores. The basic structure is familiar: four payments over about six weeks, with no interest on the standard plan when paid on time.
The cost detail is the per-installment fee that can apply on some plans, plus late fees for missed payments. Those small charges add up on a larger order, so compare the total cost, not just the first payment. Zip fits shoppers who value merchant freedom and who will pay each installment on schedule.
- Virtual card works at many online and in-store merchants
- Simple Pay in 4 structure
- Per-installment fees can apply
- Late fees can apply on missed payments
Shop Pay Installments is the natural pick inside Shopify stores, where it appears at checkout without a separate app routine. The four-payment option is interest-free when paid on time, and monthly plans are available for larger purchases at some stores, with APR varying by plan and credit.
The limit is obvious: it does not help at stores outside Shopify. Monthly plans also need the same care as any financing offer, because interest over a longer term raises the total cost. For a Shopify purchase that fits a four-payment schedule, though, it is one of the simplest pay later options to use.
- Smooth checkout inside Shopify stores
- Interest-free four-payment option
- Monthly plans for larger orders
- Only at participating Shopify stores
- Monthly plans can carry APR up to about 36 percent
Splitit takes a different route. Instead of opening a new credit line, it splits a purchase across installments on a card the shopper already holds. That can suit people who prefer to keep borrowing in one place and who already have enough available credit. Standard plans do not add interest from Splitit itself, though the underlying card terms still apply.
The trade-off is that the card hold reduces available credit until installments are paid, and fewer stores offer Splitit than the largest pay later apps. It is best for a planned purchase on a card with room to spare, where the shopper wants installments without a new account.
- Uses an existing credit card rather than new credit
- No interest from Splitit on standard plans
- Needs available credit on the card
- Store coverage is narrower than Klarna or Affirm
How we picked these
We compared official plan pages and published fee summaries for active pay later apps in the United States, and kept only apps that offer a clear split-payment plan at real merchants. We weighed plan variety, fee transparency, late payment terms and store coverage, and we left out cash advance apps and general credit cards, because they are not the same product. Prices and fees change, so we treated vendor terms as the source of truth and noted where terms vary by plan.
We did not claim hands-on testing that did not happen. Our comparison rests on published plan terms and fee pages, plus the practical risks that matter to shoppers, such as stacked plans, missed payments and interest on longer terms. Where a fee could not be verified, we pointed readers to checkout terms rather than guessing.
How to use pay later apps without trouble
Match the plan to a payday
Count the payments, not just the first one. A Pay in 4 plan takes four payments over about six weeks, so check that each date lands after money arrives. If a date falls before payday, reschedule early where the app allows it, or choose a smaller purchase.
Check the total cost before confirming
Short plans are usually interest-free when paid on time, but monthly plans can add significant interest. Read the APR, the number of payments and any fees shown at checkout, and compare that total with the cash price. If the total is hard to find, that is a reason to pause.
Keep the number of open plans low
Several small plans feel cheap one by one, but their payment dates can cluster in one week. We suggest keeping a simple list of open plans, amounts and dates, and avoiding a new plan while another is already tight. Missed payments can bring fees, account limits and, in some cases, credit reporting or collection action.
Frequently asked questions
What are the best pay later apps for Pay in 4?
Klarna, Afterpay, PayPal Pay in 4, Sezzle and Zip all offer Pay in 4 plans that are usually interest-free when paid on time. The best choice depends on the store and on late fee terms, since those differ. Affirm also offers Pay in 4 at some stores, plus longer monthly plans.
What are the best pay over time apps for larger purchases?
Affirm and Klarna monthly financing suit larger purchases, because terms can stretch well beyond six weeks. Monthly plans can carry interest, so compare the APR and total cost before choosing. A longer term lowers each payment but usually raises the total paid.
What are the best shop now pay later apps with no late fees?
Affirm states that it charges no late fees, and PayPal Pay in 4 also states no late fees on that plan. That does not remove all risk, because missed payments can still affect account standing or credit reporting on some plans. Always check the specific plan terms at checkout.
What are the best split payment apps for stores that do not list them?
Zip stands out here, because its virtual card can be used at many merchants beyond its partner list. Klarna also offers a virtual card option in some cases. Check whether the card works online, in store or both before relying on it for a purchase.
Do the best 4 payment apps affect credit scores?
Most short plans start with a soft credit check that does not affect a score by itself. Longer financing plans may involve a harder check, and missed payments or balances sent to collections can harm credit. Some apps offer optional reporting of on-time payments, but that varies by app and plan.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 top custom software development company
Top Custom Software Development Company in 2026
Looking for a top custom software development company? We compare 9 firms for web, mobile, and enterprise software, covering strengths and fit for 2026.
Read → tableau alternatives
Tableau Alternatives in 2026
Compare the best Tableau alternatives for 2026, from Power BI to Metabase, with prices, hosting options, and picks for small teams and enterprises today.
Read → microsoft teams alternatives
Best Microsoft Teams Alternatives in 2026
Looking for microsoft teams alternatives? We compare 9 chat and video tools for 2026, covering free plans, pricing, meetings, and integrations for teams.
Read →