 ProMapRanker
Best Instant Cash Apps in 2026

Key takeaways
- EarnIn and MoneyLion stand out for no mandatory monthly fee on their core advance options, while Brigit and Cleo charge a subscription.
- Instant delivery almost always costs extra, so standard delivery is the cheaper choice when a few days of waiting is possible.
- Advance limits start small for new users and grow with steady income and repayment history, so first advances are often modest.
- Cash advance fees and transfer fees vary, check terms before borrowing or sending, this is not financial advice, and we prefer apps with clear fee disclosure.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 EarnIn | No mandatory fee advances | Free | Yes | Visit |
 Dave | Budgeting plus small advances | See website | No | Visit |
 Brigit | Overdraft alerts and advances | $8.99 per month | No | Visit |
 MoneyLion | Fee-free core advances | Free | Yes | Visit |
 Albert | Banking plus larger advances over time | See website | No | Visit |
 Klover | No-subscription advances | Free | Yes | Visit |
 Cleo | Budget chat plus advances | $5.99 per month | No | Visit |
 Varo | Bank account with cash advances | See website | Yes | Visit |
The best instant cash apps
We compared cash advance apps on fees, speed, limits and how clearly each app explains its costs. A short plain disclaimer applies to the whole list: cash advance fees and transfer fees vary, check terms before borrowing or sending, this is not financial advice. Prefer apps with clear fee disclosure, and treat any advance as a short bridge, not a regular income source.
EarnIn lets workers access pay they have already earned before payday, rather than taking a traditional loan. That model suits people with a regular direct deposit who face a short gap between paydays. The app checks earnings and pay schedule, then sets a limit based on that history. Standard transfers take one to three business days, which keeps the cost at zero apart from any optional tip.
The catch is speed. Lightning Speed can move money within minutes for eligible users, but the fee for that service adds up if it is used every pay cycle. EarnIn also needs a steady direct deposit pattern, so gig workers with irregular pay may find limits lower or eligibility harder. For a one-off gap, the free standard option is the strongest reason to try it first.
- No mandatory monthly fee for core Cash Out
- Works with an existing bank account
- Fast Lightning Speed option for eligible users
- Instant delivery carries a fee
- New users often qualify for smaller daily amounts
Dave pairs small ExtraCash advances with budgeting features that track spending and upcoming bills. That combination helps people who want a warning before an account runs low, not just money after it happens. Advances are repaid automatically on the next payday, which keeps the process simple. The app also offers a checking account, so money can arrive faster inside Dave than at an outside bank.
Fees are the trade-off. Dave charges a monthly membership and a fee on each advance, plus an optional express fee for fast delivery to an external card. Those costs are small on one advance but noticeable when advances become weekly. Readers who only need an occasional advance should weigh the monthly charge against how often they will actually use it.
- ExtraCash advances alongside budgeting tools
- Banking account option
- Clear in-app repayment date
- Membership and advance fees apply
- Express delivery to an external debit card costs extra
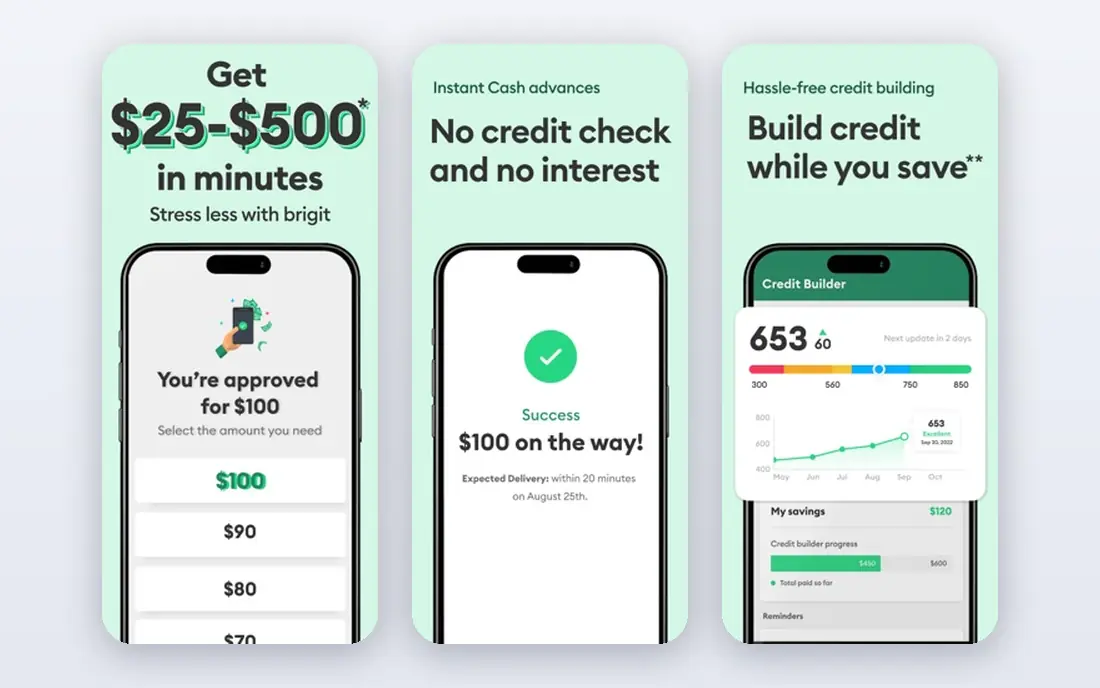
Brigit monitors a linked bank account and warns when a balance looks likely to drop below zero. That early warning is useful for people whose main problem is timing, such as a bill landing a day before payday. When an advance is needed, Brigit offers instant delivery for a small express fee, with free standard delivery taking up to three business days. There is no tipping step, which makes the total cost easier to predict.
The main drawback is the subscription. Plus starts at 8.99 dollars per month, and Premium costs more, and the charge applies even in a month with no advance. That makes Brigit a better fit for people who will use the alerts and budgeting tools all month, not for someone who needs one advance and then plans to cancel. Check the plan details before signing up, since limits and features differ by tier.
- Predicts overdrafts and sends alerts
- Advances with no tipping
- Credit builder option on higher plans
- Subscription required for advances
- Subscription continues in months with no advance
MoneyLion Instacash gives eligible users an advance with no mandatory fee when standard delivery is chosen. That free core option is the main reason it ranks high here, and it works without forcing a paid subscription. Users who route recurring direct deposits to a MoneyLion account can qualify for larger amounts over time. The app also bundles banking, investing and credit monitoring, which suits people who want several money tools in one place.
Speed again costs money. Turbo delivery can arrive within minutes, but the fee depends on the amount and the delivery method, so the price should be checked on each advance screen. Standard delivery can take one to five business days, which is too slow for a same-day emergency. Used with planning, MoneyLion is a low-cost option, but it is not the best pick for urgent cash every time.
- Instacash core advances with no mandatory fee
- Standard delivery is free
- Banking and investing tools in the same app
- Optional Turbo delivery fee varies
- Higher limits need qualifying direct deposits
Albert combines a bank account with cash advances, automatic saving and investing tools. That broad setup appeals to people who want an advance and a fuller money app, rather than a single-purpose tool. Limits start small and can rise as the account history grows, which rewards steady use and on-time repayment. The app also offers guidance from financial experts on its paid tiers, a feature most rivals do not include.
Cost is the honest weakness. Paid plans carry a monthly charge, and instant transfers add another fee, so the total for a fast advance can be higher than a free standard advance elsewhere. People who only need occasional advances may not get value from the wider bundle. Albert fits best when the banking and saving tools will be used every week, not just on payday.
- Advances can grow to larger amounts over time
- Banking, saving and investing in one app
- Human financial guidance on paid plans
- Paid plans add monthly cost
- Instant transfer fee applies
- New users start with small amounts
Klover offers advances without a monthly subscription, which sets it apart from Brigit and Cleo. Users earn points through surveys, receipts and other in-app activity, and those points can raise the advance limit. Standard delivery is free but takes a few business days, while instant delivery carries a fee that varies with the amount. For people who dislike subscriptions, that model is easy to understand.
The points system is also the catch. Reaching a higher limit takes activity, and instant fees on larger advances can be steep compared with a flat subscription elsewhere. Klover suits patient users who can plan ahead and use standard delivery. Anyone who needs instant cash often should compare the per-advance instant fee with a subscription app before choosing.
- No subscription required for core advances
- Points system can raise limits
- Standard delivery is free
- Instant delivery fees can be high on larger amounts
- Limit growth depends on points and activity
Cleo is a budgeting assistant first and a cash advance app second. Its chat format breaks spending into simple categories and answers money questions in plain language. That style suits people who find traditional budgeting apps dull and want a nudge to check spending. Advances are available on the paid plan, with no tipping step, and the fee structure is limited to the subscription plus an optional express fee.
The slow free delivery is the main limit. Standard transfers take three to four days, which is the longest wait in this list, so Cleo is a poor fit for a same-day bill. The subscription also runs every month, so occasional users pay for months they do not borrow. Cleo works best for people who will use the budgeting chat regularly and can plan advances ahead.
- Chat-based budgeting and spending breakdowns
- No tip prompts on advances
- Works with an existing bank account
- Subscription required
- Free standard delivery takes three to four days
Varo is a digital bank, so its cash advance sits inside a normal checking account rather than a standalone app. That setup suits people who want to move their main banking to one app and keep advances in the same place. Eligible users can receive advances quickly, and the account includes saving features that round up purchases or set money aside automatically. There is no monthly fee for the core bank account, which keeps the base cost low.
Advance fees vary by amount, so the price of each advance should be checked before confirming. New users also start with lower limits, and limits grow with qualifying activity over time. Varo is a strong choice for someone already planning to open a new bank account, and a weaker choice for someone who only wants a one-off advance from an outside bank.
- Full bank account with no monthly fee on the core account
- Advances arrive quickly for eligible account holders
- Saving tools built in
- Advance fees depend on the amount
- New users start with lower limits
- Best value needs a Varo account
How we picked these
We compared official feature pages, pricing pages, app store listings, privacy policies and public reviews for cash advance apps available in the United States in October 2026. We kept only apps that offer advances today, state their fees in the app or on their site, and work with a normal bank account or their own account. We left out apps with unclear pricing, apps that had closed, and general loan lenders that do not offer small instant advances. Where a price changed across sources or could not be confirmed on the vendor site, we wrote See website rather than guessing.
What to check before you take an advance
Start with the total cost, not the headline limit. Add the monthly fee, the per-advance fee and the instant delivery fee, then divide that total by the amount borrowed to see what each advance really costs. A free standard advance beats a fast paid advance in most cases, unless a bill is due the same day. Set a repayment date that matches payday, and check that the automatic debit will not push the account below zero.
Next, check eligibility and state rules. Some apps are not available in every state, and some limits are lower in certain states. Read the advance screen in full before confirming, since fees and delivery times can differ by amount and bank. If advances are needed every pay cycle, that pattern points to a budget gap rather than a cash flow gap, and a credit union small-dollar loan or a local assistance programme may cost less over time. Keep a small buffer in the account after repayment, so the next cycle does not start in the same position.
Frequently asked questions
What are the best apps to send money to Mexico?
Dedicated transfer services such as Wise and Remitly are built for sending money to Mexico, with exchange rates and delivery options shown before payment. Cash advance apps in this list are designed for advances to a US bank account, not for cross-border transfers. For a transfer to Mexico, compare the exchange rate, the transfer fee and the delivery speed across transfer services, since the cheapest fee can hide a weaker exchange rate.
What is the best app for instant cash?
EarnIn is our pick for most people who need a no-mandatory-fee advance and can wait for standard delivery. MoneyLion is a close second for the same reason, with a free core advance option. If speed matters more than cost, check the instant fee on the advance screen first, since it varies by app and amount. No app is best for every case, because limits depend on income, bank history and state rules.
What are the best apps for instant cash with no subscription?
EarnIn, MoneyLion and Klover offer core advances without a monthly subscription, though instant delivery still carries a fee. Varo also avoids a monthly fee on its core bank account, with advance fees that depend on the amount. Subscription apps such as Brigit and Cleo can still be cheaper for frequent users, because their instant fees are often lower than pay-per-advance instant fees elsewhere.
Do cash advance apps check credit?
Most apps in this list do not run a hard credit check for an advance, and instead review bank activity, income and repayment history. That makes them easier to access than a traditional loan, but it also means limits start small. Repayment is usually automatic on payday, so a missed deposit or a changed pay date can cause problems. Keep the linked account funded on the repayment date to avoid bank fees.
How fast is instant delivery really?
Instant delivery often means minutes to a linked debit card, while standard delivery takes one to five business days depending on the app and bank. Weekends and bank holidays can add time, and some banks post transfers slower than others. If money is needed the same day, confirm the delivery method and fee before accepting, and have a backup plan in case the transfer is delayed.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 best subscription manager app
Best Subscription Manager App in 2026
Find the best subscription manager app for your budget with our 2026 comparison of 8 apps, covering automatic detection, renewal alerts and free plans.
Read → best stock picking service
Best Stock Picking Service in 2026
Compare the best stock picking service options for 2026, with 8 stock recommendation services for long-term, dividend, quant, growth and income investors.
Read → best software wallet
Best Software Wallet in 2026
Compare the best software wallet options for 2026, with 8 crypto wallets for desktop and mobile, covering self-custody, supported chains, fees and security.
Read →