 ProMapRanker
Best Home Equity Investment Companies in 2026

Key takeaways
- Point and Hometap offer the largest headline amounts, up to $600,000, while Unison offers the widest state availability in this list.
- A home equity agreement has no monthly payments and no interest, but the provider shares in future appreciation, which can cost more than a loan.
- Term length matters: Point, Unison, and Splitero offer up to 30 years, while Hometap, Unlock, Nada, and EquityChoice offer 10-year terms.
- This article is general information only, not financial advice, and terms vary by home, state, and offer, so get each offer in writing before you sign.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 Point | Longest term and broad property types | See website | No | Visit |
 Hometap | Large amounts | See website | No | Visit |
 Unison | Widest state availability | See website | No | Visit |
 Unlock Technologies | Flexible buyout and early repayment | See website | No | Visit |
 Splitero | Flexible 10 to 30 year terms | See website | No | Visit |
 Nada | Transparent published fees | See website | No | Visit |
 EquityChoice | Predictable structure | See website | No | Visit |
The best home equity investment companies
We compared firms that offer home equity agreements, where a homeowner receives a lump sum now and the firm receives a share of the home's value at settlement, with no monthly payments.
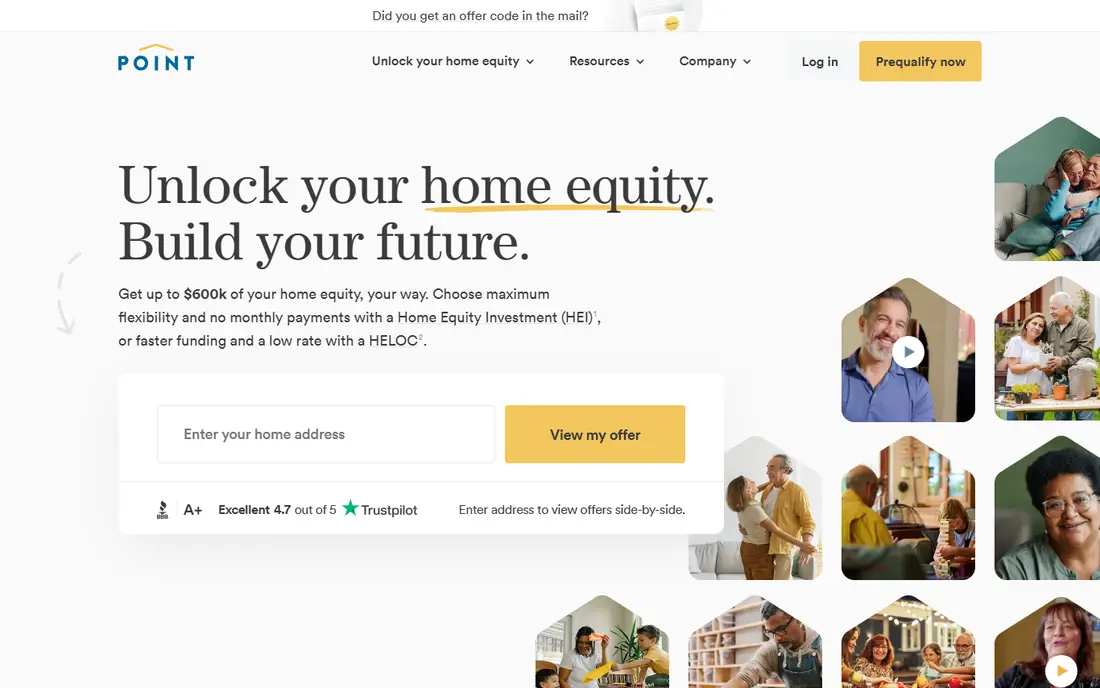
Point is our first pick for homeowners who want time. Its term runs up to 30 years, which gives far more room to sell, refinance, or buy out the agreement than a 10-year term, and its headline amount reaches up to $600,000. Point also accepts single-family homes, condos, townhomes, small multifamily properties, second homes, and investment properties, which covers more situations than firms that only serve owner-occupied homes.
The cost is not a simple interest rate. Point charges a fee deducted from funding, and it receives an agreed share of the home's value at settlement, so a strongly rising market raises the total cost. Get the fee, the starting value, the share, and any cap in writing, and compare that total against a HELOC or home equity loan for your expected time horizon. This is general information only, not financial advice.
- Term up to 30 years
- Amounts up to $600,000
- Accepts a wide range of property types including investment properties
- Fee and appreciation share vary by offer
- Not available in every state
- Settlement requires a lump-sum exit plan
Hometap suits homeowners who need a large lump sum and can plan an exit within 10 years. Its headline amount also reaches up to $600,000, tied with Point for the largest in this list, and its online process gives an estimate based on your home value and equity. Funding can arrive within weeks of signing in many cases, though timelines vary by appraisal and paperwork.
The 10-year term is the main limit. You must sell, refinance, or buy out the agreement by the end of that term, so Hometap works best when you already have a plausible exit, such as a planned move or a future refinance. Hometap charges a fee deducted from funding, and its share of appreciation is set in the offer, so read the settlement math carefully before you accept.
- Amounts up to $600,000
- Clear online estimate process
- No monthly payments
- Term is 10 years, shorter than Point or Unison
- Not available in every state
Unison is the availability pick, because it operates in more states than most firms in this category, which matters when a homeowner's state rules out other options. Its term runs up to 30 years, and its headline amount reaches up to $500,000, which gives a long runway for homeowners who plan to stay put. Unison also offers a home equity investment for buyers in some programs, though this article focuses on existing homeowners.
Unison's minimum credit expectations are higher than firms that accept scores from 500, so check eligibility before you spend time on an application. As with every firm here, the fee is deducted from funding and the appreciation share is the real long-term cost. Compare Unison's offer on the same home, same amount, and same horizon as any rival offer, since headline terms alone do not show total cost.
- Available in more than 30 states
- Term up to 30 years
- Amounts up to $500,000
- Higher minimum credit expectations than some rivals
- Fee and share vary by offer
Unlock Technologies, often listed simply as Unlock, suits homeowners who want flexibility to exit early. Its agreements allow early buyout in many offers without a prepayment penalty, which helps if your plans change, you sell sooner than expected, or you want to refinance on your own timeline. Headline amounts reach up to $500,000, and the firm accepts lower credit scores than some rivals.
The term is 10 years, so an early exit option does not remove the need for an exit plan by the end of that period. Unlock charges a fee deducted from funding, and its share of appreciation is set in the individual offer. For a homeowner who values the freedom to settle early, Unlock is worth comparing, but only after you see the full settlement math in writing.
- Amounts up to $500,000
- Early buyout without a prepayment penalty in many offers
- No monthly payments
- Term is 10 years
- Availability is narrower than Unison
- Fee and share vary by offer
Splitero suits homeowners who want to choose a term that matches their plans, rather than accepting a single 10-year or 30-year default. Its terms range from 10 to 30 years, and its headline amount reaches up to $500,000, with no monthly payments during the term. That flexibility helps a homeowner who plans to stay for 15 or 20 years and does not want to rush a sale or refinance to meet a shorter deadline.
The cost structure needs careful reading, because Splitero uses a cap on annualized cost in many offers, and the effective cost rises with home appreciation. A longer term can also mean a larger appreciation share at settlement, so a 30-year term is not automatically cheaper than a 10-year term. Get the cap, fee, and share in writing, and model settlement at several home values before you sign.
- Terms from 10 to 30 years
- Amounts up to $500,000
- No repayment required before the end of the term
- Cost can be higher under its cap structure
- Availability is narrower than Unison
- Fee and share vary by offer
Nada stands out for fee transparency, because it publishes ranges for title, inspection, valuation, notary, recording, underwriting, processing, and origination costs, with total closing costs often in the range of 4 to 7 percent of the agreement amount. That detail helps a homeowner see why the cash received is less than the headline amount, and it makes it easier to compare Nada with a rival that publishes less detail. Nada also allows settlement at any time during its 10-year term, with no early settlement fee in many offers.
The term is 10 years, and Nada serves a smaller set of states than Unison, though it covers states that some larger firms do not. Homes must meet a minimum appraised value to qualify, so check that threshold early. For a homeowner who values clear fee disclosure, Nada is a strong comparison point, even if another firm wins on term or amount.
- Publishes detailed closing cost ranges
- No monthly payments
- No early settlement fee in many offers
- Term is 10 years
- Availability is narrower than larger rivals
- Home must meet a minimum value threshold
EquityChoice suits homeowners who want a straightforward 10-year agreement with a clear settlement path. Its headline amount reaches up to $500,000, and its structure emphasizes predictability in fees and settlement terms, which helps a homeowner who dislikes surprises at closing. Like other firms here, it charges a fee deducted from funding and receives a share of the home's value at settlement.
EquityChoice expects higher credit scores than firms that accept scores from 500, so eligibility is a first check. Availability is also narrower than Unison, so confirm that your state is covered before you apply. For a homeowner with stronger credit who wants a clean 10-year agreement, EquityChoice is worth including in a three-way comparison with Hometap and Nada.
- Amounts up to $500,000
- 10-year term with a clear settlement path
- No monthly payments
- Higher minimum credit expectations than some rivals
- Availability is narrower than Unison
How we picked these
We compared official company pages, fee disclosures, and public comparisons, and we favored firms that are actively offering home equity agreements in October 2026 with published amounts, terms, and state availability. We included long-term and short-term options, and firms with different credit expectations, since that mix covers most homeowners. We did not claim hands-on testing, and we left prices as See website because the true cost depends on the individual offer, home value, fee, and appreciation share, not on a subscription price.
How to compare offers without getting misled
Start with the same numbers for every firm: the cash you will actually receive after fees, the starting home value, the share the firm receives at settlement, and any cap on total cost. Ask each firm to show settlement at three home values: flat, modest growth, and strong growth, over your expected time horizon. A firm that looks cheapest at flat growth can become the most expensive at strong growth, so a single headline fee tells you very little.
Next, check term, exit, and lien terms in writing. Confirm how long you have before settlement is due, whether you can buy out early without a penalty, what happens if you refinance, and how the lien affects a future sale. A 30-year term gives more time, but it also gives appreciation more years to grow, so weigh time against total cost for your own plans.
Finally, compare a home equity agreement against a HELOC and a home equity loan on the same amount and horizon. A loan has monthly payments and interest, but it does not share in appreciation, so it can be cheaper if your home rises strongly and you can manage payments. If you cannot manage payments, or if your credit or income blocks a loan, an agreement may still be the right tool, but only after you see the full settlement math. This is general information only, not financial advice, and terms vary by state, home, and offer.
Frequently asked questions
What are the best home equity agreement companies?
Point, Hometap, and Unison are the strongest starting points, with Point for long terms, Hometap for large amounts, and Unison for wide availability. Compare at least three offers on the same home before you choose, since settlement math varies widely.
What is the best home equity investment company for a long term?
Point, Unison, and Splitero offer terms up to 30 years, which suit homeowners who plan to stay long term. A longer term gives more time to exit, but it can also increase the appreciation share at settlement, so model both effects.
Do home equity investment companies charge monthly payments?
No, home equity agreements have no monthly payments and no interest. The firm charges a fee deducted from funding and receives a share of the home's value when you sell, refinance, or buy out the agreement.
How much cash can I get from a home equity agreement?
Headline amounts reach up to $600,000 at Point and Hometap, and up to $500,000 at Unison, Unlock, Splitero, Nada, and EquityChoice, subject to home value, equity, state, and credit. The cash you receive is less than the headline amount after fees and closing costs.
Is a home equity agreement better than a HELOC?
It depends on your home's growth, your time horizon, and whether you can manage monthly payments. A HELOC can be cheaper if your home rises strongly, while an agreement can suit homeowners who need cash without monthly payments or who cannot qualify for a loan.
Sources
- https://www.point.com
- https://www.hometap.com
- https://www.unison.com
- https://www.unlock.com
- https://www.splitero.com
- https://www.nada.co
- https://www.equitychoice.com
- https://themortgagereports.com/122275/top-home-equity-investment-companies-in-current_year
- https://money.com/best-home-equity-sharing-companies/
- https://www.finder.com/home-equity/what-is-a-home-equity-agreement
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 best tour operator software
Best Tour Operator Software in 2026
Compare the best tour operator software for bookings, channel management, waivers and payments, with pricing models for day tours and multi-day trips.
Read → best time clock app for small business
Best Time Clock App for Small Business in 2026
We compare the best time clock app for small business options, with free plans, GPS clock ins, scheduling and payroll links for hourly teams and payroll help.
Read → best test automation tools
Best Test Automation Tools in 2026
Compare the best test automation tools, from Playwright and Selenium to Cypress, Katalon and BrowserStack, with prices, languages and best uses explained.
Read →