 ProMapRanker
Best Credit Repair Software in 2026

Clear tiers and a written guarantee · Pricing starts at: $79.99 per month
Key takeaways
- Done-for-you services suit people who want disputes handled for them, while DIY tools suit people who want to send their own letters at a lower monthly cost.
- Starting prices in this list run from about $35 per month for a DIY tool to about $99 per month for a full service, before any first-work or setup fee.
- No service can legally remove accurate, current negative items, and no service should promise a specific score increase.
- A money-back guarantee helps, but the terms matter, so read the refund window and the conditions before you sign up.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
| Credit Saint | Clear tiers and a written guarantee | $79.99 per month | No | Visit |
 Sky Blue Credit | Simple pricing and pausing | $79 per month | No | Visit |
 The Credit People | A flat-rate option | $99 per month | No | Visit |
 The Credit Pros | Monitoring plus disputes | $119 per month | No | Visit |
 Ovation Credit | A dedicated case advisor | $79 per month | No | Visit |
 Credit Glory | Inquiry-heavy reports | $99 per month | No | Visit |
 Dovly | A lower-cost managed option | $39.99 per month | No | Visit |
 DisputeBee | DIY disputes across three bureaus | $35 per month | No | Visit |
The best credit repair software
We compared done-for-you services and DIY tools on price, what each plan actually includes, refund terms, and how much control you keep. This is not financial or legal advice, and results vary from person to person.
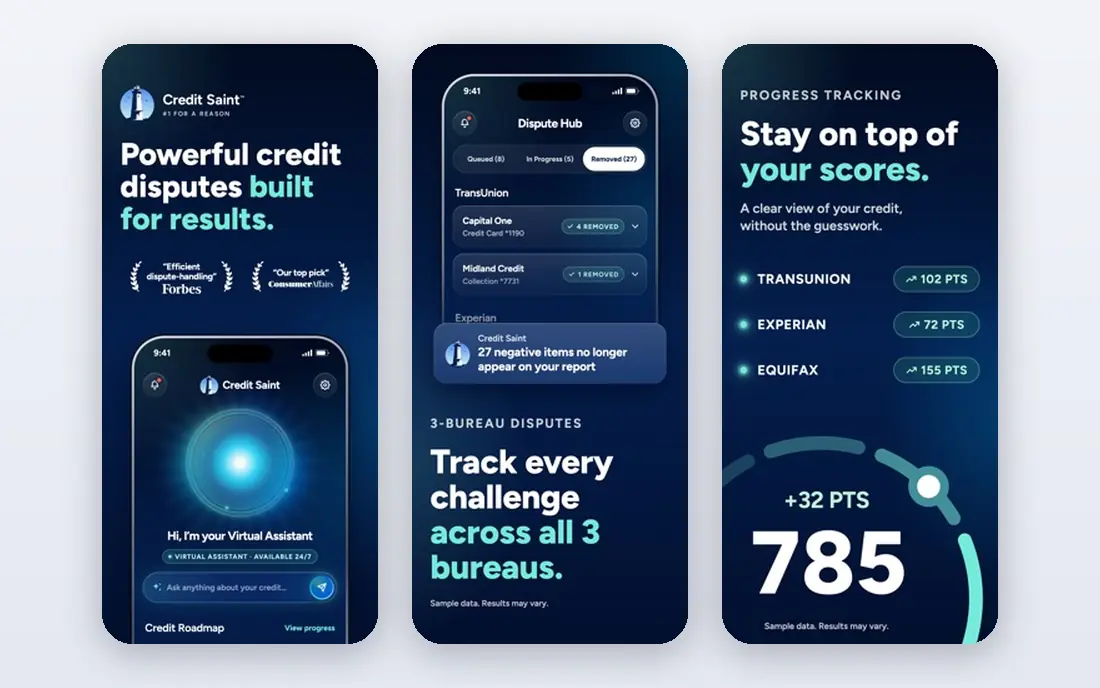
Credit Saint is the most straightforward starting point in this list for a reader who wants a managed service with published tiers. The plans scale by the level of dispute work, so you can see what changes when you pay more instead of guessing from a sales call. Consultations and access to credit reports and scores are part of the offer, which helps if you are still learning what is on your reports.
The catch is the total first-month cost, because a first-work fee applies in addition to the monthly charge. Check the fee for the tier you choose and confirm availability in your state before you commit. The 90-day money-back guarantee is a real comfort, but read its conditions, since guarantees in this industry are rarely unconditional.
- Three clear tiers
- 90-day money-back guarantee
- One-on-one consultations included
- First-work fee on top of the monthly price
- Not available in every state
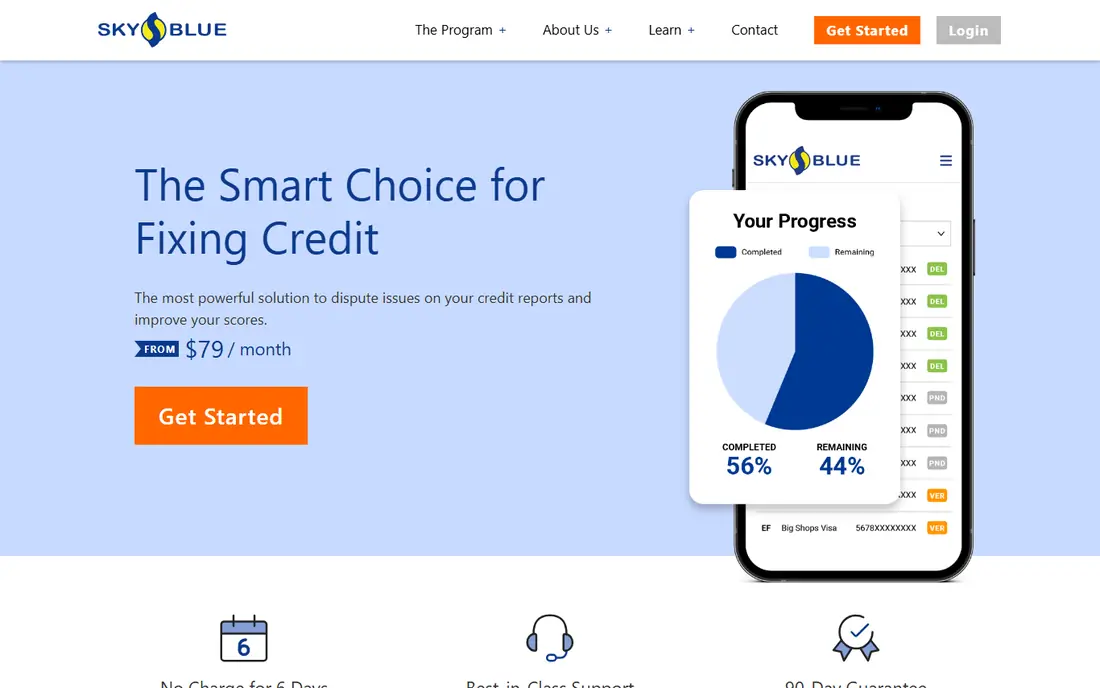
Sky Blue Credit appeals to people who dislike tier puzzles and upsell pressure. One main monthly price keeps the decision simple, and the option to pause is useful if money gets tight for a month or you want to wait for bureau responses. A couples discount is also available, which can lower the cost for two people working on reports at the same time.
The trade-off is a lighter-touch service than the most expensive managed plans. If you want a dedicated advisor walking you through every item, another option on this list may fit better. For a reader with a short list of errors and a preference for plain pricing, that simplicity is a strength rather than a gap.
- Simple monthly pricing
- Pause option
- Couples discount available
- Less hand-holding than some premium tiers
- No free plan
The Credit People stand out because of the flat-rate choice alongside monthly plans. Paying a fixed amount for six months caps the total cost, which helps if you worry about a monthly bill running on while disputes drag out. Monthly plans are also available for people who prefer to pay as they go and stop sooner.
That flexibility comes at a mid-range price, so it is not the cheapest route here. Ask exactly what the satisfaction guarantee covers and how it is claimed, since the headline promise is less useful than the written terms. For a reader who wants cost certainty above all, the flat-rate plan is the reason to shortlist this one.
- Flat-rate six-month option
- Clear monthly plans
- Satisfaction guarantee terms published on request
- Monthly cost sits above the cheapest options
- Guarantee conditions need checking
The Credit Pros work best for a reader who wants monitoring and dispute help in one place. Higher tiers bundle monitoring with dispute work, so you can watch for new items while older ones are challenged. Bilingual support is a practical plus for households that prefer to discuss credit in Spanish.
Be careful with the entry tier, because the cheapest plan is focused on money management rather than full dispute work. The dispute plans cost more, and setup fees can apply, so compare the total price for the plan that actually includes disputes. If monitoring matters as much as disputes, this bundle makes sense.
- Tiered plans
- Bilingual support
- Credit monitoring bundled in higher tiers
- Real dispute work starts above the cheapest tier
- Setup fees apply on some plans
Ovation Credit is built around a personal case advisor, which is the main reason to pick it over a cheaper, more automated service. Having one person who knows your file can make follow-up calls and questions less frustrating. The option to send custom dispute letters also helps when a standard template does not fit your situation.
The downside is the setup fee and the absence of a money-back guarantee in the published offer. That means you should be surer about the fit before you pay, and you should ask what happens if disputes stall. For a reader who values a named contact over the lowest price, Ovation is a fair choice.
- Dedicated case advisor
- Custom dispute letters available
- Backed by LendingTree
- Setup fee applies
- No money-back guarantee advertised
Credit Glory is worth a look when unauthorized hard inquiries or unverifiable collections dominate your reports. That focus gives it a clearer job than a general service that treats every item the same way. Onboarding is quick, with a call early in the process to review your reports and set priorities.
The setup fee is high, so the first month costs far more than the monthly price alone suggests. Some reviewers also describe the sales approach as pushy, which is a reason to take notes, ask for terms in writing, and avoid signing on the first call. If inquiries are your main problem, the specialty may justify the cost.
- Focus on unauthorized inquiries and unverifiable collections
- Fast onboarding call
- Steep setup fee
- Sales calls reported as aggressive by some reviewers
Dovly sits between DIY software and full-price managed services. The monthly cost is well below the other managed options here, and the process leans on automation to prepare and track disputes. That makes it a good fit for a reader who wants help but cannot justify close to $100 per month.
Automation is also the limit. You get less one-on-one guidance than with an advisor-led service, so complex cases with mixed documentation may need more of your own input. If your reports have a few clear errors and you want a managed process at a lower price, Dovly is a sensible middle ground.
- Lower monthly price than most managed services
- Automated dispute process
- Simple sign-up
- Less personal service than advisor-led options
- No free plan
DisputeBee is the true DIY pick in this list. It helps you generate dispute letters for Equifax, Experian, and TransUnion, track responses, and stay organized, while you remain in charge of sending and following up. With no setup fee and the lowest starting price here, it is the cheapest way to get structure without paying for a managed service.
The obvious catch is effort. You must read bureau replies, decide next steps, and keep records yourself, which takes time and care. If you are comfortable with paperwork and want to save money, that control is a plus. If you want someone else to chase replies, pick a managed service instead.
- DIY dispute letters for all three bureaus
- No setup fee
- You keep full control
- You do the follow-up work
- No advisor handling your case
How we picked these
We compared official pricing pages, plan descriptions, and public reviews for managed services and DIY tools that are still operating in October 2026. We kept only options that clearly offer credit repair or dispute help, and we left out services with unclear status or closed operations. Prices are starting prices for the dispute plan where a service offers more than one tier, and fees on top of the monthly price are noted in the write-up.
What to check before you pay
Start by pulling your own reports for free and marking each negative item as accurate, inaccurate, or unverifiable. That list tells you whether you need a full service, a specialty service for inquiries, or a DIY tool. Next, add up the first three months of cost, including any first-work or setup fee, because the monthly price alone understates the bill.
Read the guarantee and the cancellation terms
Ask how to cancel, whether cancellation stops future billing at once, and what proof a guarantee claim needs. Get the answers in writing before you pay, and keep copies of every letter and bureau reply. A service that is vague about cancellation is a warning sign, even if the monthly price looks good.
Do the free work first
You can dispute errors yourself directly with each bureau at no cost, and nonprofit credit counselors can review your budget and debts without selling you a repair plan. Paid help makes sense when you lack time or the case is tangled, not as a first step for one simple error. Keep that order in mind, and a paid service becomes a tool rather than a crutch.
Frequently asked questions
What is the best credit repair app?
The best credit repair app depends on how much work you want to do yourself. DisputeBee fits DIY users who want letter help at a low monthly cost, while Credit Saint and Sky Blue Credit fit readers who want a managed service. Start with your error list, then match it to the plan that covers those items.
What is the best credit repair software for business?
Business credit repair is a different job from personal repair, and most tools here are built for personal reports. A business owner should ask a provider directly whether it handles business credit files, what it charges, and what documents it needs. Do not assume a personal plan covers a company file.
Is there a best free credit repair app?
There is no full free managed service in this list, and any tool that promises free full repair deserves a close look at its terms. You can dispute errors yourself for free with each bureau, which is the real free route. Free trials and free report access exist, but ongoing dispute help here is paid.
Can credit repair software remove accurate negative items?
No, and any company that promises to remove accurate, current items should be avoided. Legitimate repair challenges inaccurate, unverifiable, or outdated items and helps you document the case. Accurate items generally stay until they age off your reports under the law.
How long does credit repair take?
Timing varies with the number of items, how bureaus respond, and whether creditors verify the debts. Some readers see changes in a few months, while complex cases take longer. A service that promises a fixed timeline or a fixed score gain is overselling what it can control.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 github alternatives
Best GitHub Alternatives in 2026
Explore the best GitHub alternatives in 2026, from GitLab and Bitbucket to self-hosted Gitea and Forgejo, with prices and trade-offs for developers for readers.
Read → cineby alternatives
Cineby Alternatives in 2026
We compared legal cineby alternatives for licensed streaming, including Netflix, Hulu, Disney Plus, and free options, so you can watch without piracy sites.
Read → best visibility analysis software
Best Visibility Analysis Software in 2026
Compare the best visibility analysis software for search and AI answers. We review 8 tools that track brand mentions, citations, and rankings Updated for 2026.
Read →