 ProMapRanker
Best Credit Builder Apps in 2026

Key takeaways
- The best credit builder app depends on whether you need a revolving account, an installment loan, or bill reporting, because each builds a different part of your file.
- Chime and Kikoff are the cheapest starting points, while Self and Credit Strong suit people who want a structured loan plus savings at the end.
- Reporting to all three bureaus matters, because an account that reaches only one bureau leaves the other two files thin.
- Fees and credit outcomes vary, and no app can guarantee a score increase or a specific number of points.
- Pay on time, keep utilization low, and check your reports regularly, because those habits matter more than the app you pick.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 Chime Card | Free secured card for Chime users | Free | Yes | Visit |
 Kikoff | Cheapest revolving starter account | $5 per month | No | Visit |
 Self | Builder loan plus savings | $25 per month | No | Visit |
 Kovo | Subscription reporting without debt | $10 per month | No | Visit |
 Grow Credit | Building credit from subscriptions | Free | Yes | Visit |
 Experian Boost | Free boost from bills to Experian | Free | Yes | Visit |
 MoneyLion | Builder loan plus financial tools | $19.99 per month | No | Visit |
 Credit Strong | Flexible builder loan terms | $15 per month | No | Visit |
 StellarFi | Bill reporting as tradelines | $9.99 per month | No | Visit |
The best credit builder apps
Credit builder apps work by creating an account that reports your payments to the credit bureaus, so on-time activity builds a history where none existed. They differ in account type, cost, and bureau coverage, and the right one depends on your starting point and your budget.
Please note: fees, interest, and credit outcomes vary by product and by person, and this article is not financial advice. A builder app can help when used steadily, but it cannot guarantee a score change, and missed payments can hurt the file you are trying to build.
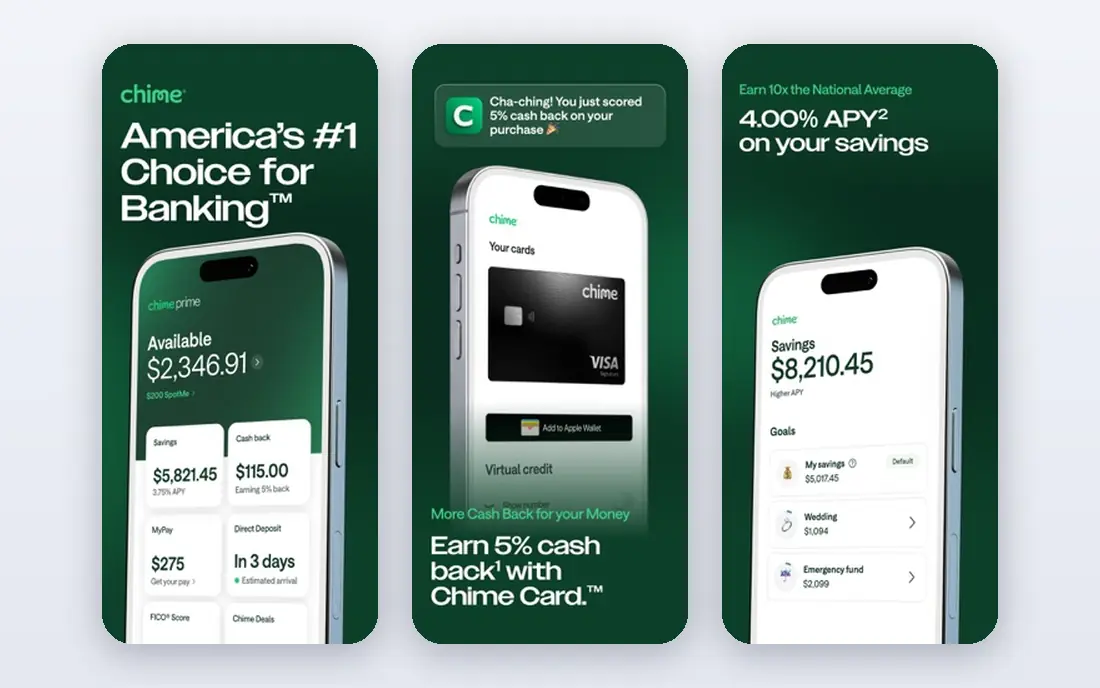
Chime Card, formerly known as Chime Credit Builder, is the best free starting point for people who already bank with Chime. You move money from your Chime checking account to the card, spend against that balance, and Chime reports your activity to Equifax, Experian, and TransUnion. There is no interest and no annual fee, which removes the two costs that make many secured cards painful.
The eligibility rule is the catch: you need an active Chime checking account and at least one qualifying direct deposit, usually from an employer, payroll provider, gig platform, or benefits agency, rather than a peer transfer. If you meet that rule, Chime is hard to beat on price. If you do not bank with Chime, Kikoff or Grow Credit will get you started faster.
- No annual fee, no interest, and no minimum security deposit
- Reports to all three bureaus
- Card cannot carry a revolving balance in the usual way
- Requires a Chime checking account with qualifying direct deposit
- Naming has changed to Chime Card for new applicants
- No rewards on the basic builder setup
Kikoff is our pick for the cheapest structured start, because its revolving account costs from $5 per month and reports to all three bureaus. That revolving tradeline matters for a thin file, because it shows a different kind of credit behavior than an installment loan, and Kikoff requires no hard credit check to sign up, so applying does not mark your new file. Plans run for twelve months, and rent reporting is included on plans, with an option to add prior rent history for a fee.
The limit is small by design, and Kikoff is not a card you use for everyday spending in the usual sense. It is a builder account, built to create a payment record. For someone who also needs a spending card, pair Kikoff with a secured card rather than expecting one product to do both jobs.
- Small revolving account from $5 per month
- No hard credit check to sign up
- Reports to all three bureaus
- Rent reporting included on plans
- Low credit limit by design
- Rent history add-ons cost extra
- Not a full bank account or a general spending card
Self is the best-known credit builder loan, and its structure suits people who want forced savings alongside credit building. You pick a monthly payment, Self reports those payments to all three bureaus as an installment loan, and at the end of the term you receive the saved amount minus interest and fees. A common plan costs $25 per month for 24 months, with about $520 returned at the end, though the exact return depends on the plan and fees.
The trade is liquidity: your money sits locked until the term ends, and you pay interest and fees for the privilege. An optional Self Visa secured card becomes available once you have saved $100, which adds a revolving account to the installment history. If you can commit to a monthly payment and like ending with savings, it is a strong, well-understood option.
- Installment loan reported to all three bureaus
- Savings returned at the end of the term
- Optional secured card once savings build
- Monthly payments plus interest and fees
- Money is locked until the term ends
- Larger plans cost more per month
Kovo takes a different route: for $10 per month over 24 months, it reports a set of subscription services as an installment tradeline to all three bureaus, plus Innovis, a fourth bureau some lenders check. There is no interest and no hard credit pull, which makes it gentler than a loan for people who dislike debt products.
The honest question is whether those bundled services fit your life. If they do, Kovo is a clean, low-cost builder. If they do not, you are paying for services you would not choose alone. Check the current bundle before you sign up, and compare it with Kikoff if you want a revolving account instead of an installment tradeline.
- Reports to all three bureaus plus Innovis
- No interest and no hard credit pull
- Simple $10 per month structure
- Value depends on the bundled subscription services
- 24-month term is a commitment
- Not a spending card
Grow Credit is the most passive builder on this list, because it reports payments you already make for streaming and other subscriptions. You link eligible subscriptions, Grow Credit issues a virtual Mastercard for those payments, and it reports the activity to all three bureaus. The free tier covers a basic allowance, which means some people can start building credit without a new monthly bill, beyond the subscriptions they already pay for.
Paid plans raise the allowance and add features, so check whether the free tier covers your subscriptions before you upgrade. Grow Credit will not replace a revolving card for large purchases, and only eligible subscriptions count.
- Free tier available
- Reports subscription payments you already make
- Reports to all three bureaus
- No hard check on the free tier in its model
- Paid plans add cost for higher limits
- Subscription payments must be eligible
- Not a general-purpose credit card
Experian Boost is a free add-on rather than a standalone builder, and it belongs on this list because it costs nothing and helps many people quickly. You connect a bank account, Experian scans for eligible utility, phone, and streaming payments, and it adds those payments to your Experian credit file. Lenders that use Experian data may then see a fuller payment history than they would from traditional accounts alone.
The limit is scope: Boost reports to Experian only, so Equifax and TransUnion files stay unchanged, and any score change depends on your existing file and the lender's model. It is best used alongside a builder that reports to all three bureaus, not instead of one.
- Free to use
- Adds eligible utility, telecom, and streaming payments to your Experian file
- No new monthly bill
- Reports to Experian only
- Boost size varies and is not guaranteed
- Requires linking a bank account
MoneyLion Credit Builder Plus bundles a small builder loan with a wider financial app, for $19.99 per month in membership. The loan reports to all three bureaus, building installment history, while the app adds budgeting tools and access to cash advance features under its Instacash model. For someone who wants building, budgeting, and short-term cash help in one place, that bundle has real appeal.
The price is the drawback for pure building: at nearly $20 per month, it costs four times Kikoff for a similar reporting outcome, even if the extra tools justify it for some users. Cash advance features also need discipline, because borrowing against future income can become a habit.
- Builder loan reported to all three bureaus
- Budgeting and financial tools in the same app
- Cash advance access in its membership model
- $19.99 per month membership is higher than Kikoff or Kovo
- Advance features need careful use
- Not the cheapest pure builder
Credit Strong suits people who want to tailor a builder loan rather than take a fixed plan. Monthly payments start at $15 per month, with loan sizes and terms ranging from short to very long, so you can match the payment to your budget and the savings goal to your timeline. Payments report to all three bureaus, building installment history in the same way as Self, with more choice over size and length.
Flexibility has a cost: interest and fees apply, and closing early can reduce what you receive back, so a long term should only be chosen if you plan to see it through. Read the plan terms for the exact loan size, monthly payment, and return before you sign. For a borrower who wants control over the loan shape, Credit Strong offers more dials than most rivals.
- Wide range of loan sizes and terms from 12 to 120 months
- Reports to all three bureaus
- Lets you tailor monthly payment to budget
- Monthly payments plus interest and fees
- Early closure can reduce the interest return
- Larger loans cost more per month
StellarFi reports your regular bills as tradelines, turning payments you already make into credit history without a loan or a card. That model suits people with steady bills but no traditional credit accounts, and higher tiers report to all three bureaus, which matters for a complete file. The tiered pricing lets you start at $9.99 per month and move up if you want broader reporting.
Lower tiers report to fewer bureaus, so check which bureaus your tier covers before you pay, because a bill reported to only two bureaus is less useful than one reported to three. StellarFi also charges a monthly fee for reporting bills you could otherwise pay directly, so the value depends on how much those tradelines help your file. For bill-heavy households without other accounts, it is a useful addition alongside a revolving builder.
- Reports bills as tradelines to bureaus, with all three on higher tiers
- Tiered plans for different budgets
- No new debt product required
- Lower tiers report to fewer bureaus
- Monthly fee adds up over a year
- Bill eligibility and reporting details need checking
How we picked these
We compared official product pages, pricing pages, and public comparisons for apps still offered in October 2026. We favored products with clear bureau reporting, published pricing, and an official homepage we could verify, and we included revolving accounts, installment loans, and bill reporting so readers can match the account type to their file. We left out apps with unclear reporting or discontinued products.
We did not claim hands-on testing of credit outcomes, and we did not invent score gains, because results vary by file, lender, and payment behavior. Our method rests on published account types, bureau coverage, and costs, and we recommend checking your free credit reports regularly to confirm that an account actually appears as described.
How to use a credit builder app well
Start with one account, not five. A single revolving account or a single installment loan, paid on time every month, builds a cleaner history than several new accounts opened at once.
Keep utilization low on any revolving account. That means using a small share of the limit and paying the balance in full where the product allows, rather than carrying a balance to "show activity." On-time payments are the foundation, and a missed payment on a builder account hurts the same file you are trying to improve, so set autopay where the product supports it and keep a buffer for the monthly fee.
Check your reports after two or three months to confirm the account appears on each bureau the product promises. If an account is missing, contact the provider with the details from your report. Finally, remember that a builder app is a step, not a destination: after a year of steady payments, a secured card or a mainstream card with responsible use usually becomes the next step toward a thicker file.
Frequently asked questions
What is the best app to build credit from scratch?
Kikoff is the cheapest structured start from scratch, at $5 per month with reporting to all three bureaus and no hard check. Chime Card is the best free option if you already bank with Chime and meet its direct deposit rule, while Grow Credit suits people who already pay eligible subscriptions.
What is the best app to improve a credit score quickly?
No app can guarantee a fast score increase, and anyone promising one should be treated with caution. Experian Boost can add bill payments to an Experian file quickly and for free, while a builder account paid on time over several months builds a steadier history. The fastest honest path is on-time payments, low utilization, and fixing errors on your reports.
Do credit builder apps report to all three bureaus?
Many do, including Chime, Kikoff, Self, Kovo, Grow Credit, MoneyLion, and Credit Strong. Some products report to fewer bureaus, including Experian Boost, which reports to Experian only, and lower tiers of StellarFi. Check bureau coverage for your exact plan before you pay, because coverage decides how complete your file becomes.
Is Self worth it for building credit?
Self is worth it if you want an installment loan plus forced savings and can commit to monthly payments for the full term. The $25 per month plan is a common choice, with savings returned minus interest and fees at the end. If you need the money back soon or dislike locked savings, Kikoff or Grow Credit may fit better.
What is the best credit building app with no fees?
Chime Card has no annual fee and no interest for eligible Chime users, and Experian Boost and the free tier of Grow Credit cost nothing to start. Free options still require eligible accounts or subscriptions, so check the rules for each product before you count on a zero-cost start.
Can a credit builder app hurt my credit?
Yes, if payments are missed or fees go unpaid, because the same reporting that builds history when you pay on time can record late payments too. Opening many accounts at once can also lower your average account age. Use one account steadily, set autopay where possible, and check your reports to catch problems early.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 top custom software development company
Top Custom Software Development Company in 2026
Looking for a top custom software development company? We compare 9 firms for web, mobile, and enterprise software, covering strengths and fit for 2026.
Read → tableau alternatives
Tableau Alternatives in 2026
Compare the best Tableau alternatives for 2026, from Power BI to Metabase, with prices, hosting options, and picks for small teams and enterprises today.
Read → microsoft teams alternatives
Best Microsoft Teams Alternatives in 2026
Looking for microsoft teams alternatives? We compare 9 chat and video tools for 2026, covering free plans, pricing, meetings, and integrations for teams.
Read →