 ProMapRanker
Best Klarna Alternatives in 2026

Key takeaways
- Affirm suits larger purchases, with longer monthly plans and no late fees on its plans.
- Afterpay and PayPal Pay in 4 suit short, interest-free splits, with different late fee rules.
- Sezzle suits shoppers who want credit building options, with optional paid features for reporting.
- Zip and Splitit suit shopping outside a single partner store, through virtual cards or existing credit cards.
- Always check APR, late fees, and credit reporting for the exact plan you choose, because terms vary by purchase.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 Affirm | Larger purchases, no late fees | Free | Yes | Visit |
 Afterpay | Short retail splits | Free | Yes | Visit |
 PayPal Pay Later | PayPal shoppers | Free | Yes | Visit |
 Sezzle | Credit building options | Free | Yes | Visit |
 Zip | Shopping anywhere Visa is accepted | Free | Yes | Visit |
 Splitit | Using your existing credit card | Free | Yes | Visit |
 Shop Pay Installments | Shopify checkout | Free | Yes | Visit |
 Uplift | Travel and larger purchases | Free | Yes | Visit |
The best Klarna alternatives
Buy now, pay later is credit. Missed payments can mean fees and credit harm. This is general information only, not financial advice. The services below split purchases into installments, but their fees, APR ranges, and credit reporting differ, so read the terms for each plan before you use one.
Affirm is the strongest pick for larger purchases, because it offers Pay in 4 at 0% APR plus longer monthly plans for higher-ticket items. Loan amounts can reach high limits for qualified shoppers, and terms can extend for many months, which helps spread a large purchase. Affirm also charges no late fees, which sets it apart from several rivals.
No late fees do not mean no risk. Monthly plans can carry APR up to 36%, depending on credit and the merchant, and Affirm reports loans to credit bureaus, so missed payments can harm credit. Check the APR shown at checkout for your exact purchase, not only the headline Pay in 4 rate. For a planned large purchase with a clear repayment plan, Affirm is a solid choice.
- No late fees
- Pay in 4 at 0% APR
- Longer monthly plans for larger buys
- Monthly plan APR can reach 36%
- Missed payments can still harm credit
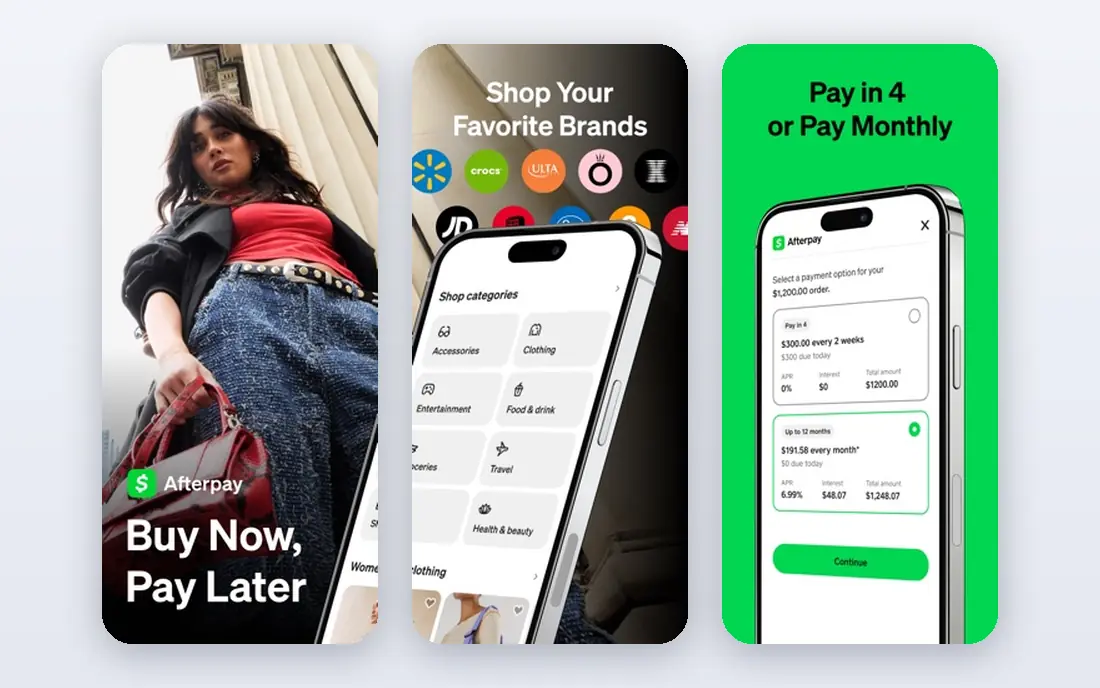
Afterpay is built around a simple model: split a purchase into four payments over six weeks, with the first payment often due at checkout. It is widely available at fashion, beauty, and retail stores, and it works in-store through a virtual card in many cases. That simplicity makes it easy to understand, especially for smaller retail buys.
Late fees are the main risk. Afterpay late fees can add up to 25% of the order value in some cases, which turns a small purchase into a larger cost quickly. Afterpay also does not report on-time payments to build credit by default in the same way as some rivals. Use it only for purchases you can repay on schedule, and avoid stacking several Afterpay orders at once.
- Simple Pay in 4 model
- Widely available at retail stores
- In-store virtual card options
- Late fees can reach 25% of the order
- No credit building by default
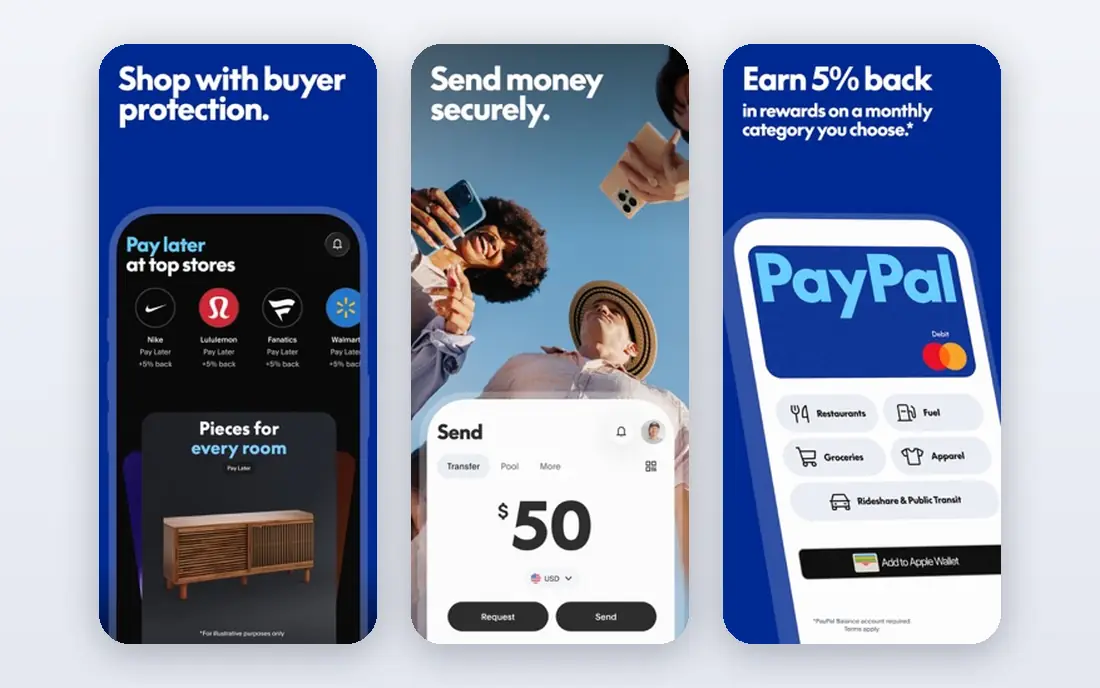
PayPal Pay Later suits shoppers who already use PayPal, because it appears at checkout where PayPal is accepted. Pay in 4 splits a purchase into four interest-free payments, with no late fees in many cases, while Pay Monthly offers longer terms for larger purchases. That range covers both small retail buys and larger planned spending.
Monthly plans can carry APR up to 35.99%, and limits differ between Pay in 4 and Monthly plans, so check the plan shown at checkout. PayPal may also report Monthly plan activity, which means missed payments can affect credit. For PayPal users who want a familiar checkout and a clear short split, PayPal Pay Later is a practical pick.
- Pay in 4 with no late fees in many cases
- Monthly plans for larger buys
- Works where PayPal is accepted
- Monthly plan APR can reach 35.99%
- Limits vary by plan
Sezzle offers Pay in 2, Pay in 4, and longer Monthly plans, which gives more flexibility than a single four-payment model. Shoppers who join Sezzle Up can have on-time payments reported, which may help build credit over time. A virtual card also lets you shop at many merchants, not only at direct Sezzle partners, subject to current merchant coverage.
Fees need attention. Sezzle service fees can apply on some plans, and late fees apply after a grace period, with caps tied to order value in some cases. Monthly plan APR can also reach high levels, so check the exact plan terms. Sezzle suits shoppers who want flexible splits and an optional credit building path, with a clear repayment plan.
- Pay in 2, Pay in 4, and Monthly options
- Optional credit building with Sezzle Up
- Virtual card for wider shopping
- Service fees may apply on some plans
- Late fees apply after a grace period
Zip, formerly Quadpay, uses a virtual Visa card, which lets you split purchases at many stores that accept Visa, not only at partner merchants. That breadth is its main advantage, especially for shopping at smaller stores or in-store through a mobile wallet. Plans include short splits and longer options, depending on the purchase and your account.
Per-order fees may apply, and late fees can apply if payments are missed, so the total cost can exceed a no-fee Pay in 4 at a partner store. Check the fee shown before you confirm a purchase, and compare it with a direct partner option where one exists. For flexible shopping outside partner stores, Zip is a strong alternative.
- Virtual Visa card for broad shopping
- Pay in 4 and longer options
- In-store use via mobile wallet
- Per-order fees may apply
- Late fees apply in some cases
Splitit works differently from most BNPL apps, because it splits a purchase across your existing credit card, rather than opening a new loan. Your card is charged in installments, and Splitit charges no interest or fees to consumers on standard plans, subject to your card terms. That model suits shoppers who already have a card with enough available limit and want to avoid a new credit account.
The limit is card capacity and merchant coverage. You need enough available credit for the full purchase amount, and not every store offers Splitit at checkout. Your card issuer's interest and fees still apply if you do not pay the card bill in full, so Splitit is not free money. For cardholders who want a simple split without a new account, it is a clean option.
- No new loan account
- Uses your existing credit card
- No interest from Splitit on standard plans
- Needs an available credit card limit
- Merchant coverage is narrower than major BNPL apps
Shop Pay Installments appears at checkout on Shopify stores that offer it, powered by Affirm in the United States. Shoppers can choose Pay in 4 or longer Monthly plans, depending on the purchase amount and eligibility. The checkout flow is familiar to Shopify shoppers, and Shop Pay can save payment details for future orders.
Coverage is the limit. Shop Pay Installments only works where a Shopify merchant offers it, so it is not a general shopping card like Zip. Monthly plan APR varies, and credit reporting follows Affirm's rules for those plans. For regular Shopify shoppers, it is a convenient alternative that avoids a separate app.
- Built into Shopify checkout
- Pay in 4 and Monthly options
- Familiar checkout flow
- Only where Shopify merchants offer it
- Monthly APR varies by purchase
Uplift focuses on larger purchases, especially travel, with monthly installment plans shown at checkout. Instead of squeezing a holiday or a large purchase into four payments over six weeks, Uplift spreads it over months, which can make a big purchase more manageable. Partners include travel brands and other large purchase merchants.
Interest may apply, depending on credit and the plan, so the total cost can exceed the purchase price. Uplift is not the best tool for small everyday splits, where a no-interest Pay in 4 is cheaper. For a planned travel purchase with a clear budget and a repayment plan, Uplift is a useful alternative to consider.
- Monthly plans for travel and larger buys
- Available at travel and retail partners
- Clear monthly payment shown at checkout
- Interest may apply
- Not suited to small everyday splits
How we picked these
We compared official pages and recent BNPL comparisons for services that are live in the United States in October 2026. We kept only services that offer a clear installment model, published fee or APR information, and a real checkout or card option. We included short splits, longer monthly plans, card-based splits, and travel plans, so readers can match the tool to purchase size and store coverage. Terms vary by purchase and credit, so we flagged APR, fees, and reporting as checks for every plan.
How to use buy now, pay later safely
Only split a purchase you could afford without the split, or a planned large purchase with a fixed repayment date. Add every installment to your budget, including the dates, and avoid opening several BNPL plans at once, because overlapping payments are easy to miss. Set payment reminders or autopay where it is safe to do so, and keep a buffer for the next payment date.
Before you confirm, read the plan terms at checkout. Check whether the plan is interest-free, what APR applies to longer plans, what late fees apply, and whether activity is reported to credit bureaus. If the APR or fee is unclear, or if the purchase is not essential, wait or choose a cheaper option. Buy now, pay later is credit, and missed payments can mean fees and credit harm.
Frequently asked questions
What is the best Klarna alternative for no late fees?
Affirm charges no late fees on its plans, and PayPal Pay in 4 has no late fees in many cases. No late fees do not remove credit risk, because missed payments can still be reported and can harm credit. Always check the exact plan terms, because fees and reporting vary by plan and purchase.
Is Afterpay better than Klarna for small purchases?
Afterpay suits small retail purchases with a simple Pay in 4 model, but late fees can reach 25% of the order value. Klarna offers Pay in 4, Pay in 30, and Monthly plans, with different fee and reporting rules. For small purchases you can repay on time, either can work, but Afterpay's late fee cap deserves attention.
Do Klarna alternatives check credit?
Most BNPL services run a soft credit check for short plans, which does not usually affect your score in the same way as a hard check. Longer monthly plans may involve a harder check or reporting, depending on the provider and purchase. Check the provider's terms at checkout, because the check type varies by plan.
Can I build credit with buy now, pay later?
Some services report on-time payments, such as Affirm for its loans and Sezzle Up for eligible users, while others do not report by default. Reporting can help if you pay on time, and can harm if you miss payments. Do not rely on BNPL as a primary credit building tool without checking the provider's reporting policy.
What happens if I miss a buy now, pay later payment?
Missed payments can trigger late fees, account restrictions, and, for reported plans, credit harm or collections. Fee amounts and grace periods vary by provider, so check the plan terms before you buy. Contact the provider early if you cannot pay on time, because some providers offer payment help or rescheduling.
Is Splitit really interest-free?
Splitit charges no interest or fees to consumers on standard plans, but it uses your existing credit card, so your card issuer's interest applies if you do not pay the card bill in full. You also need enough available credit for the full purchase. Splitit is interest-free from Splitit, not free from your card terms.
Sources
- https://www.moneylion.com/learn/personal-loans/buy-now-pay-later/best-buy-now-pay-later-apps
- https://www.moneylion.com/learn/personal-loans/buy-now-pay-later/alternative-apps-like-klarna
- https://www.affirm.com
- https://www.afterpay.com
- https://www.paypal.com
- https://sezzle.com
- https://zip.co
- https://www.splitit.com
- https://shop.app
- https://www.uplift.com
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 zoro.to alternatives
Best Zoro.to Alternatives in 2026
We compare the best zoro.to alternatives in 2026, listing only legal licensed anime streaming services, from Crunchyroll to free options for fans today.
Read → zip alternatives
Best Zip Alternatives in 2026
We compare the best zip alternatives for buy now, pay later in 2026, covering pay-in-4 plans, fees, spending limits, and credit reporting options today.
Read → yesware alternatives
Best Yesware Alternatives in 2026
Compare the best yesware alternatives for sales email tracking, templates, and sequences, with current pricing and honest tradeoffs for small sales teams.
Read →