 ProMapRanker
Best Chime Alternatives in 2026

Key takeaways
- SoFi is our pick for most people who want banking, savings, investing and lending in one app with no monthly fee.
- Varo Bank is the closest chartered neobank match, with its own bank charter and a mobile-first account.
- Current suits families and younger users who want spending controls, cashback and early direct deposit.
- Ally Bank and Capital One 360 suit people who want a full online bank with joint accounts, savings tools and broader products.
- Rates and fees change often, so check the current terms, FDIC status and fee schedule before opening any account. This is general information only, not financial advice.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 SoFi | All-in-one banking | Free | Yes | Visit |
 Varo Bank | Chartered mobile banking | Free | Yes | Visit |
 Current | Family and everyday banking | Free | Yes | Visit |
 Ally Bank | Full online banking | Free | Yes | Visit |
 Capital One 360 | Broad online banking | Free | Yes | Visit |
 Discover Bank | Cashback debit and savings | Free | Yes | Visit |
 Cash App | Simple money and payments | Free | Yes | Visit |
 MoneyLion | Banking plus credit tools | Free | Yes | Visit |
 Dave | Cash advances and budgeting | See website | No | Visit |
The best Chime alternatives
This article covers Chime banking and fintech app alternatives for US users who want everyday checking, savings and early direct deposit without branch banking. Chime itself is a fintech company that offers banking services through partner banks, rather than a chartered bank on its own. The options below include both chartered banks and fintech apps, and we note that difference where it matters. This is general information only, not financial advice, and rates, fees and eligibility can change.
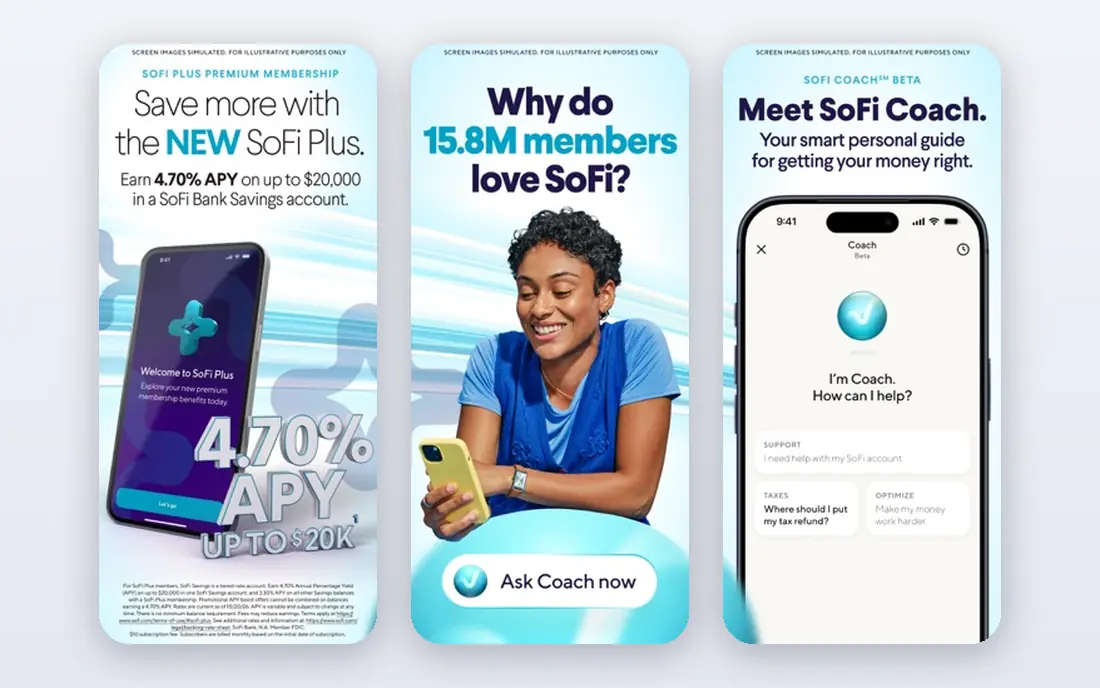
SoFi is a chartered bank that has grown into a full financial app, which makes it a strong Chime alternative for people who want more than a checking account. You can hold checking and savings, set up direct deposit, invest and explore lending from the same login, without a monthly account fee. Early direct deposit and savings tools are central to its pitch.
The catch is that headline savings rates often depend on direct deposit or other conditions, so read the current terms before you expect a top rate. Investing is also separate from insured deposits, and it carries risk. If you want one app for everyday banking plus wider financial products, SoFi is our pick for most people.
- No monthly fee on checking and savings
- Early direct deposit
- Banking plus investing and lending in one app
- Best savings rates often need direct deposit
- Product range can feel complex
- Investing carries risk and is not banking
Varo Bank is notable because it holds its own national bank charter, unlike many fintech apps that rely on partner banks. That makes it the closest structural match to a traditional bank among mobile-first options, while still offering a no monthly fee account, early direct deposit and in-app savings tools. For users who care about charter status, that difference matters.
Varo has no branches, so cash deposits and in-person help are limited, and its best savings rates often come with conditions. It also offers fewer products than SoFi or Ally. If you want a mobile-first bank with its own charter and a simple fee structure, Varo is a strong choice.
- Own national bank charter
- No monthly fee
- Early direct deposit and savings tools
- No branches
- Savings rate tiers and conditions apply
- Product range is narrower than large online banks
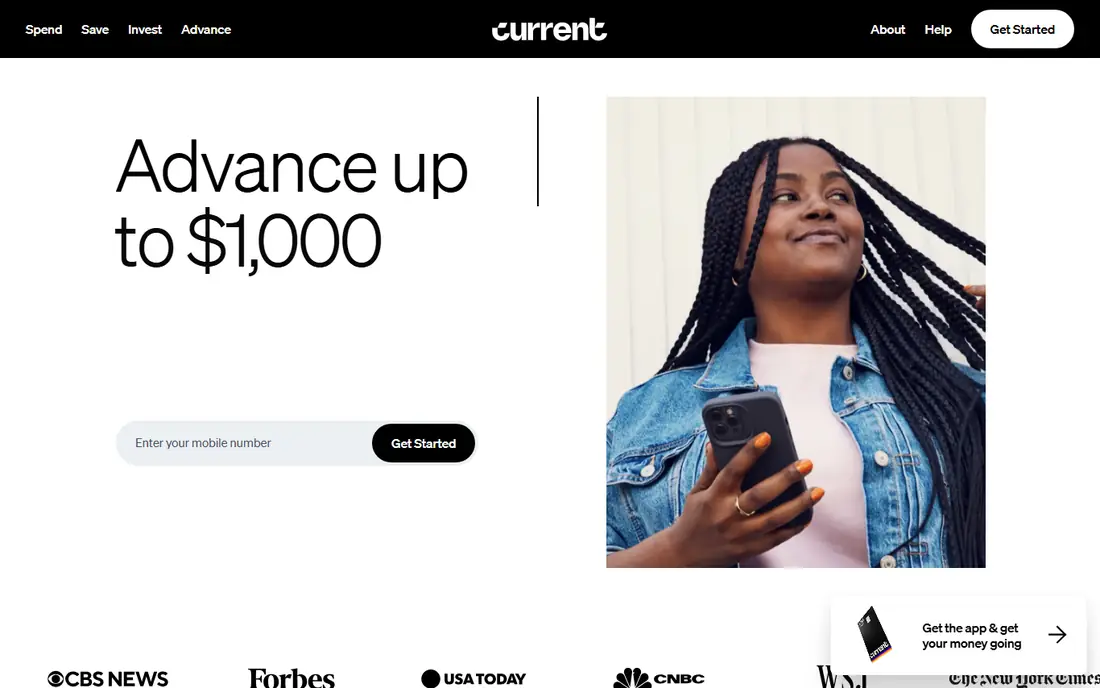
Current is built for everyday spending, families and younger users who want clear controls and instant alerts. It offers early direct deposit, cashback on eligible debit purchases and account options for teens with parental controls. That family focus sets it apart from more general online banks.
Current is a fintech app that provides banking services through partner banks, so check the current partner and FDIC pass-through terms on its site. Some premium features sit behind a paid plan, and savings rates come with conditions. If family banking, spending controls and cashback matter most, Current is worth a close look.
- Early direct deposit
- Cashback on debit spending
- Teen and family account options
- Banking services run through partner banks
- Some features need a paid plan
- Savings conditions apply
Ally Bank is a full online bank with a long track record, and it suits people who want Chime style fees with a broader product range. Checking and savings carry no monthly fee, joint accounts are available, and savings buckets and budgeting tools help separate money for goals. That breadth makes Ally a good main bank, not just a second account.
There are no branches, so you will handle cash and complex issues online or by phone. Early direct deposit timing also depends on when your payer sends the payment file, so the exact timing can vary. If you want a proven online bank with joint accounts and savings tools, Ally is a safe, practical pick.
- No monthly fee on checking and savings
- Joint accounts available
- Strong savings and budgeting tools
- No branches
- Early direct deposit timing depends on payer
- Rates change with the market
Capital One 360 gives online banking with the backing of a large bank, plus access to a wide ATM network and some physical locations for help. Checking carries no monthly fee, joint accounts are available, and savings products cover a range of goals. That mix suits people who want online convenience without giving up all in-person options.
Rates differ across products, so compare the specific savings or checking product you plan to open, not a headline rate for a different account. Early direct deposit also depends on payer timing. If you want a large bank feel with online pricing, Capital One 360 is a strong alternative.
- No monthly fee on 360 checking
- Joint accounts
- Wide ATM network and some physical locations
- Savings rates vary by product
- App experience varies by account type
- Early deposit timing depends on payer
Discover Bank appeals to people who want a reward for everyday debit spending. Its checking account offers cashback on eligible purchases, with no monthly fee, and its online savings products are competitive for a simple setup. That combination suits users who spend mainly by debit and want a return without a credit card.
Cashback rules, categories and caps matter, so read the current terms before you count on a return. There are no branches, and the product range is narrower than a full service bank. If debit cashback and simple online banking are your priorities, Discover is a clear Chime alternative.
- Cashback on eligible debit purchases
- No monthly fee
- Solid online savings options
- No branches
- Cashback categories and caps apply
- Product range is narrower than some large banks
Cash App is best known for peer payments, but it also offers a debit card and banking style features for everyday money. It suits people who mainly want to send money to friends, split bills and spend from a balance, with a very simple app. For a secondary spending account, that simplicity is appealing.
It is not a full bank replacement for most people. Banking services run through partner banks, savings and joint account options are limited, and instant transfers can carry a fee. Use Cash App as a payments and spending tool, and keep a full bank account for savings, bills and direct deposit if you need those features.
- Very simple peer payments
- Debit card for spending
- Easy money movement between friends
- Not a full bank replacement
- Banking services run through partner banks
- Fees apply to some instant transfers
MoneyLion combines banking with credit building and cash advance features, which appeals to users who want help with short term cash flow and credit history. Eligible users can access advances, track spending and use credit builder products from one app. That bundle is different from a plain checking account.
Advances are not free money: limits, eligibility and repayment timing matter, and some features need a paid membership. Credit builder products also need careful use, because missed payments can harm credit. If you want banking plus credit tools in one place, MoneyLion is worth comparing, but read the advance and membership terms closely.
- Banking plus credit building tools in one app
- Cash advances for eligible users
- Budgeting and rewards features
- Advance limits and eligibility rules apply
- Some features need a paid membership
- Credit tools need careful use
Dave is built around short term cash advances and budgeting, rather than full banking. Eligible users can get a modest advance to bridge a gap before payday, track spending and set goals in a simple app. That focus suits gig workers and others with irregular income who need a small buffer.
The limits are modest, a membership fee applies on some plans, and Dave is not a substitute for a full checking and savings bank. Advances should be used sparingly, because repeated advances can mask a budget gap rather than fix it. If a small advance plus budgeting help is your main need, Dave is a focused option, but check the current membership and advance terms first.
- Cash advances for eligible users
- Budgeting tools
- Simple app for short term cash needs
- Membership fee applies to some plans
- Advance limits are modest
- Not a full bank account replacement
How we picked these
We compared official bank and app pages, fee schedules and public feature notes for US everyday banking options that are live in October 2026. We kept only accounts that offer a clear Chime alternative in checking, savings, early direct deposit or cash flow help, and we noted where a service is a fintech app using partner banks rather than a chartered bank. We used Free where a no monthly fee account is published, and See website where pricing depends on membership or plan.
We did not claim hands-on testing and we did not give personal financial advice. Rates, fees and eligibility change often, and FDIC coverage depends on the bank or partner bank named in the current terms. Check the official fee schedule and deposit terms before opening any account.
How to choose a Chime alternative without surprise fees
Start with how you actually use money. If you need joint accounts, a full bank such as Ally or Capital One 360 will serve you better than a fintech app. If you need family controls or debit cashback, Current or Discover may fit better. If you want banking plus investing or credit tools, SoFi or MoneyLion may be worth the extra complexity.
Next, check four items in the current terms: monthly fee, early direct deposit conditions, savings rate conditions, and how cash deposits and ATM access work. A no fee account that charges for ATM use or instant transfers can still cost money. Also confirm FDIC insurance and which bank holds deposits, especially for fintech apps. Opening a second account alongside your current bank for a month is a low risk way to test the app before moving direct deposit.
Frequently asked questions
Is Chime a bank?
No, Chime is a financial technology company, not a bank. It offers banking services through partner banks that are FDIC insured members, so deposits are covered through those partners up to the legal limit. Alternatives such as SoFi, Varo, Ally and Capital One 360 hold bank charters, while Current, Cash App and others use partner banks.
Which Chime alternative offers early direct deposit?
SoFi, Varo, Current, Ally, Capital One 360 and several others offer early direct deposit, usually up to two days early. Timing depends on when your employer or payer sends the payment file, so it is not guaranteed for every paycheck. Check the current terms for each account before relying on early access.
Which Chime alternative has the highest savings rate?
Rates change frequently and often depend on direct deposit, balance tiers or other conditions, so there is no stable winner. Varo, Current, SoFi and Ally have all offered competitive savings rates in 2026, but the best rate on the day you open an account may differ. Compare the current rate and its conditions, not a headline from an older article.
Do Chime alternatives offer joint accounts?
Some do, and some do not. Ally, Capital One 360, SoFi and Discover offer joint account options for many products, while some fintech apps focus on individual accounts. If you share bills or savings with a partner, confirm joint account support for the exact product before you apply.
Are online banks and neobanks safe?
Accounts at FDIC insured banks, or through FDIC insured partner banks, are covered up to $250,000 per depositor, per bank, per ownership category, under current FDIC rules. Safety also depends on app security, fraud controls and how you protect your login. Check the FDIC status named in the current terms, use strong authentication, and keep an eye on transactions.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 zoro.to alternatives
Best Zoro.to Alternatives in 2026
We compare the best zoro.to alternatives in 2026, listing only legal licensed anime streaming services, from Crunchyroll to free options for fans today.
Read → zip alternatives
Best Zip Alternatives in 2026
We compare the best zip alternatives for buy now, pay later in 2026, covering pay-in-4 plans, fees, spending limits, and credit reporting options today.
Read → yesware alternatives
Best Yesware Alternatives in 2026
Compare the best yesware alternatives for sales email tracking, templates, and sequences, with current pricing and honest tradeoffs for small sales teams.
Read →