 ProMapRanker
Best Student Loan Consolidation Companies in 2026

Key takeaways
- SoFi is our pick for most borrowers who want a broad refinance lender with member benefits and flexible terms.
- Earnest suits borrowers who want to customize payment amounts and dates around their income.
- Laurel Road suits healthcare professionals, while Splash Financial suits borrowers who want to compare multiple lenders at once.
- Refinancing federal loans into a private loan removes federal protections, so check that trade-off before you apply.
- Rates and terms vary by credit, income and loan balance, so compare personalized offers, not headline rates alone.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 SoFi | Broad refinance choice | See website | No | Visit |
 Earnest | Flexible payments | See website | No | Visit |
 Laurel Road | Healthcare professionals | See website | No | Visit |
 Splash Financial | Comparing lenders | See website | No | Visit |
 ELFI | Personal service | See website | No | Visit |
 College Ave | Fast application | See website | No | Visit |
 Citizens Bank | Bank customers | See website | No | Visit |
 Credible | Rate marketplace | See website | No | Visit |
The best student loan consolidation companies
This is not financial advice, and rates and terms vary by credit, income and loan balance. Federal Direct Consolidation and private refinancing are different tools. Federal consolidation combines federal loans into one federal loan and keeps federal protections, while private refinancing replaces loans with a new private loan that may offer a lower rate but removes federal benefits. We compared official lender pages and public guides, and we focused on eligibility, term choices, fees, borrower protections and ease of comparison.
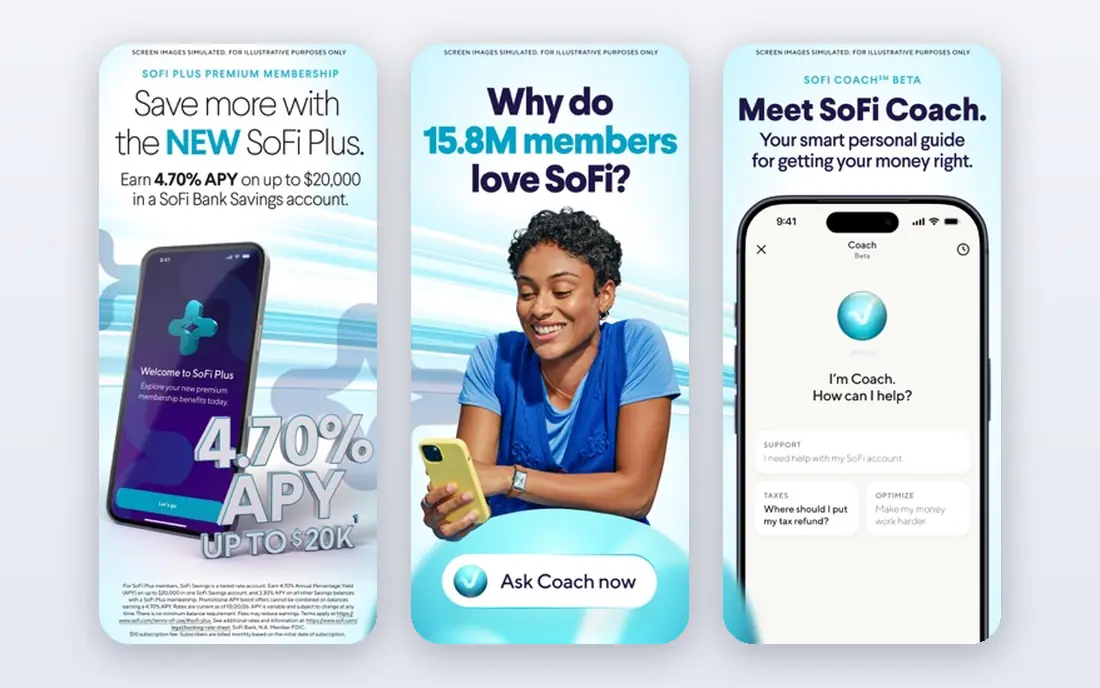
SoFi is a common first stop for student loan refinancing because it covers a wide range of borrowers and loan balances. Borrowers can choose from several repayment terms, and SoFi does not charge origination or prepayment fees on many refinance loans. Member benefits, including career coaching and financial planning resources, add value beyond the loan itself.
The catch is qualification. The lowest advertised rates go to borrowers with strong credit and stable income, and other borrowers will see higher offers. SoFi also cannot preserve federal protections such as income-driven repayment or federal forgiveness programs, so federal borrowers should weigh that loss carefully before refinancing.
- Wide term choices and no-fee refinancing in many cases
- Member benefits such as career support
- Large, established lender
- Best rates need strong credit and income
- Refinancing federal loans removes federal protections
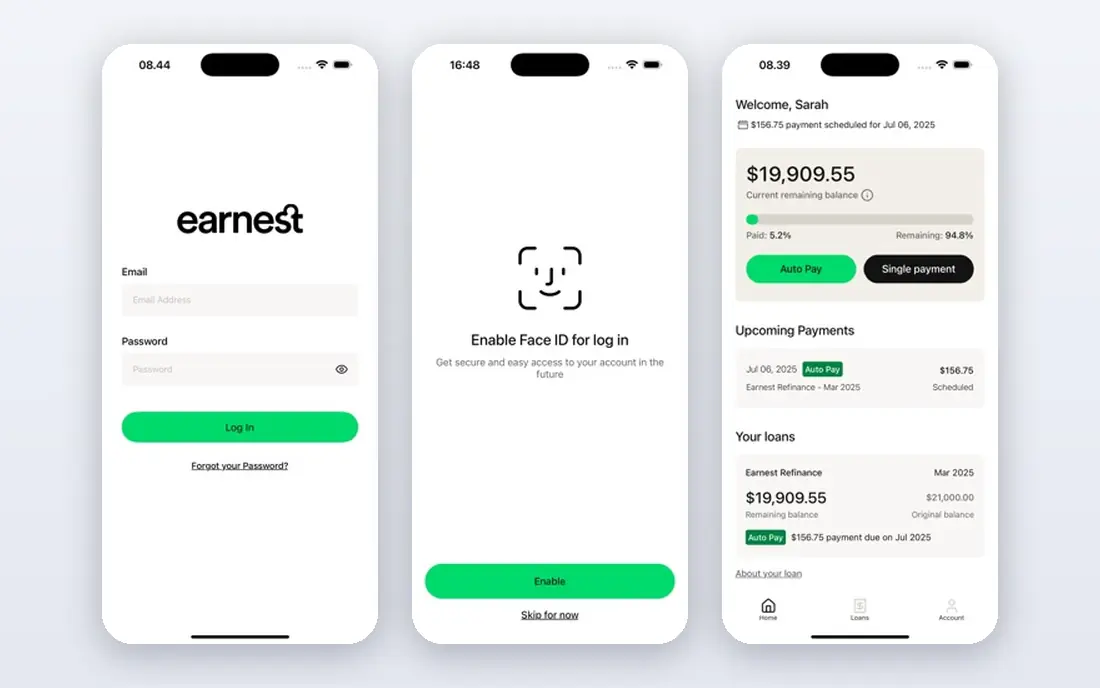
Earnest stands out for payment flexibility. Borrowers can often choose a monthly payment that fits their budget and pick a payment date, rather than accepting a fixed schedule. That control helps borrowers with variable income or tight cash flow in the early years after graduation.
Earnest still underwrites on credit and income, so not every applicant will qualify for its lowest rates. It also suits borrowers who are comfortable managing a loan online. If you want in-person banking or a long branch relationship, a bank lender such as Citizens may feel more familiar.
- Custom payment amounts and dates
- Ability to adjust payments within set limits
- Clear online application
- Best rates need strong credit
- Fewer branch options than a traditional bank
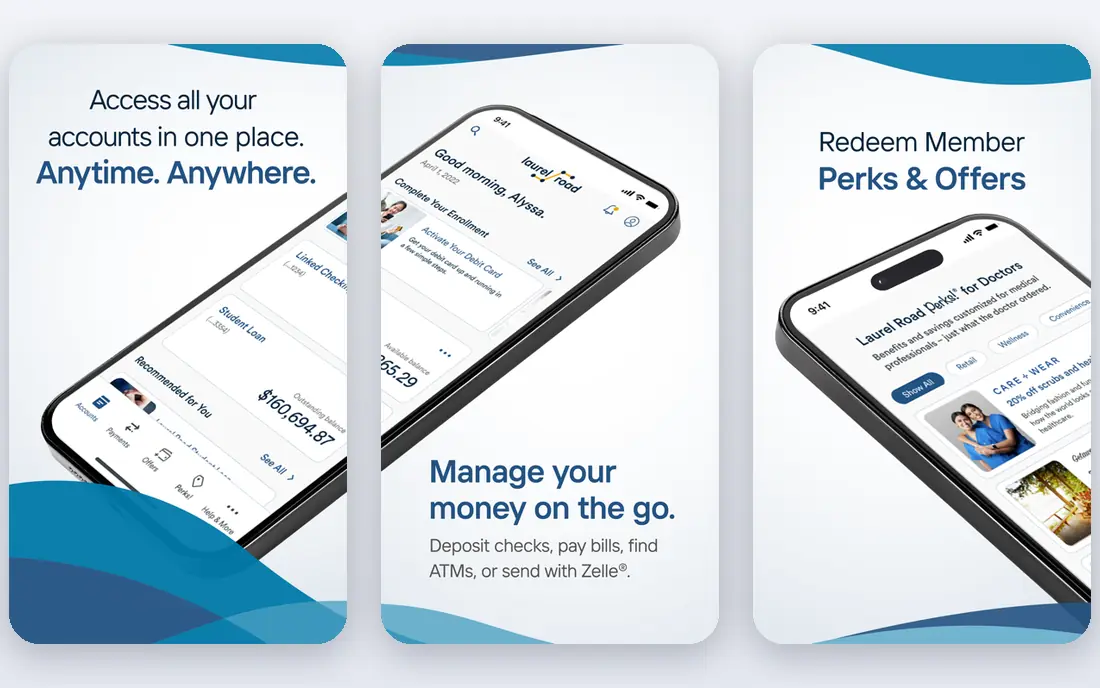
Laurel Road, part of KeyBank, has built a strong name with healthcare professionals, including doctors and dentists with large loan balances. Its refinance options often reflect the income path of medical careers, with terms that suit high balances and residency transitions. That focus makes it worth a quote for healthcare borrowers even if they already have offers elsewhere.
Non-healthcare borrowers can still apply, but they may not get the same specialist value. As with other lenders, check the full offer, including term length, fixed versus variable rate, and any autopay discount, rather than judging by a headline rate.
- Specialist options for doctors, dentists and other healthcare workers
- Flexible terms for high-balance borrowers
- Established bank-backed lender
- Specialist benefits may not help non-healthcare borrowers
- Rates vary by credit and loan type
Splash Financial is a marketplace rather than a single lender. You submit one application, and Splash shows offers from partner lenders, which saves time compared with applying to each lender separately. That comparison view helps borrowers see how term length and rate type change the monthly payment.
The limit is that Splash does not set the final loan terms. The partner lender makes the credit decision, services the loan or assigns servicing, and sets its own borrower protections. Read the partner terms carefully, and do not assume that a marketplace offer includes the same forbearance options as a direct lender.
- Marketplace that compares offers from multiple lenders
- One application can surface several rates
- Useful for rate shopping
- Final loan terms come from the partner lender, not Splash itself
- Not every lender appears in the marketplace
ELFI, or Education Loan Finance, focuses on student loan refinancing and offers personal support through loan advisors. That human help suits borrowers who want to talk through term choices, cosigner options and rate types before they sign. ELFI also handles larger balances, which matters for graduate and professional borrowers.
ELFI is less well known than the largest lenders, so some borrowers may prefer a bigger brand. That should not rule it out. Compare its personalized offer, term choices and borrower protections with at least two other lenders, and judge it on the final loan terms.
- Personal loan advisors for many borrowers
- Options for large balances
- Clear focus on student loan refinancing
- Smaller brand presence than SoFi or Earnest
- Rates vary by credit and term
College Ave is known for a fast, online-first application process. Borrowers can check rates, choose a term and complete much of the process without paper forms or branch visits. That speed helps when you want to compare offers quickly and move before a rate offer expires.
The trade-off is term range. College Ave refinance terms are narrower than the widest ranges offered by some rivals, so borrowers who want a very long term to lower payments may need another lender. Check the monthly payment and total interest cost for each term, not only the lowest payment.
- Streamlined online application
- Term choices for refinance borrowers
- Good for borrowers who want a quick decision
- Term range is narrower than some rivals
- Rates vary by credit and income
Citizens Bank suits borrowers who already bank with Citizens or prefer a traditional bank relationship. Existing customers may qualify for loyalty discounts, and the bank offers both online and branch support. That familiarity can help borrowers who want to manage student loans alongside checking, savings and other accounts.
Online-only lenders may offer a faster application and a wider term range. Citizens also underwrites on credit and income, so its best rates still need strong qualifications. Compare its final offer with online lenders, and check whether any loyalty discount requires keeping other accounts open.
- Bank relationship and loyalty discounts for some customers
- In-person and online servicing
- Established bank lender
- Rates vary by credit and relationship
- Application may feel slower than online-only lenders
Credible is another marketplace that lets borrowers compare personalized refinance rates from partner lenders in one place. That side-by-side view makes it easier to see how a fixed rate, a variable rate and different terms affect the monthly payment and total cost. It is free to use for comparison, and it can save time during rate shopping.
As with Splash, Credible does not lend the money itself. The partner lender sets the final rate, term and borrower protections, and servicing may move to another company after closing. Compare the final loan documents, not only the marketplace preview, before you accept an offer.
- Compares personalized rates from multiple lenders
- Useful side-by-side view of terms
- Free to use for rate comparison
- Final terms come from the partner lender
- Not every lender participates
How we picked these
We compared official lender pages, marketplace pages and public guides for student loan consolidation and refinancing in October 2026. We kept lenders and marketplaces that are current, serve US borrowers and offer refinancing or consolidation for federal or private loans. We did not claim hands-on testing, and we did not publish specific rates, because rates change often and depend on credit, income and loan balance. We judged each company on eligibility, term choices, fees, borrower protections and ease of comparison, and we marked pricing as See website where rates must be checked on the lender page.
How to choose a student loan consolidation company
First, separate federal consolidation from private refinancing. If you need income-driven repayment, federal forgiveness programs or federal forbearance, keep your federal loans federal and consider a federal Direct Consolidation Loan through the official federal loan site. If you have private loans, strong credit and stable income, and you do not need federal protections, private refinancing may lower your rate or simplify payments.
Next, compare at least three personalized offers. Check the fixed and variable rate, the term length, the monthly payment, the total interest cost and any autopay discount. A longer term lowers the monthly payment but usually raises total interest, while a variable rate may start lower and rise later. Also check fees, cosigner release options and forbearance terms, because those matter if your income changes.
Finally, read the final loan documents before you sign. Confirm the rate type, the term, the payment date, the servicer and what happens if you miss a payment. Keep copies of your old loan payoff letters, and confirm that each old loan is actually paid off after refinancing. A lower rate only helps if the new loan is correct and the old loans are closed.
Frequently asked questions
What is the best company to consolidate student loans?
There is no single best company for every borrower. SoFi suits many borrowers for breadth and benefits, Earnest suits flexible payments, Laurel Road suits healthcare professionals, and Splash or Credible suit borrowers who want to compare multiple lenders. Compare personalized offers from at least three sources, and check federal protections before you refinance federal loans.
What are the best companies to refinance student loans?
SoFi, Earnest, Laurel Road, ELFI, College Ave and Citizens Bank are among the most cited refinance lenders, while Splash Financial and Credible are marketplaces that compare partner lenders. The best offer depends on your credit, income, loan balance and preferred term. Rates and terms vary, so a personalized quote matters more than a headline rate.
Is it better to consolidate or refinance student loans?
Federal consolidation combines federal loans into one federal loan and keeps federal protections, but it does not usually lower your rate. Private refinancing can lower your rate and simplify payments, but it removes federal protections such as income-driven repayment and federal forgiveness. Choose federal consolidation if you need those protections, and consider refinancing only if you understand that trade-off.
Can I consolidate federal and private student loans together?
Private refinancing can combine federal and private loans into one new private loan, but that move removes federal protections from the federal portion. Federal Direct Consolidation only combines federal loans. If you hold both types, consider keeping federal loans separate unless you are certain you do not need federal benefits.
Do student loan consolidation companies charge fees?
Many refinance lenders do not charge origination or prepayment fees, but terms vary by lender and loan. Check the final loan documents for origination fees, late fees and any other charges before you sign. This is not financial advice, and rates and terms vary, so confirm current terms on each lender website.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 who is the best seo company
Who Is the Best SEO Company in 2026
Compare who is the best SEO company in the USA, from full service agencies to SEO only specialists, with fit and service notes Compare features, pricing,.
Read → top bi software
Top BI Software in 2026: 9 Tools Compared
Compare the top BI software in 2026, with dashboards, reporting, data links, sharing, pricing and free plans for small teams, analysts and large companies.
Read → spyfu alternatives
SpyFu Alternatives in 2026: 9 Tools Compared
Compare the best spyfu alternatives in 2026, from Semrush and Ahrefs to SE Ranking, Moz, and Mangools, for competitor and keyword research work. for teams
Read →