 ProMapRanker
Best Software for Mortgage Document Automation in 2026

Key takeaways
- Most mortgage document tools in this list use quoted pricing, because cost depends on loan volume, integrations and services.
- DocMagic and First American Docutech focus on compliant document generation and eClosing, while Blend focuses on the borrower facing workflow.
- Ocrolus and Instabase suit lenders that need AI extraction from bank statements, pay stubs and other unstructured documents.
- Floify, SimpleNexus and Maxwell help smaller lenders collect documents through a borrower portal without a full enterprise platform.
- This is not financial advice, and lenders should confirm compliance, investor rules and state eNotary rules before choosing a tool.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 Blend | Digital borrower workflow | See website | No | Visit |
 DocMagic | Compliant closing documents | See website | No | Visit |
 First American Docutech | Document generation and eSign | See website | No | Visit |
 Floify | Borrower document collection | See website | No | Visit |
 SimpleNexus | Mobile borrower portal | See website | No | Visit |
 LendingPad | Cloud LOS with documents | See website | No | Visit |
 MeridianLink Mortgage | LOS and document workflow | See website | No | Visit |
 Ocrolus | AI document extraction | See website | No | Visit |
 Maxwell | Small lender document workflow | See website | No | Visit |
The best software for mortgage document automation
These tools generate, collect, verify, sign and store mortgage documents, from initial disclosures to closing packages. We compared them on document generation, eSign, extraction, borrower experience, integrations and fit for lender size.
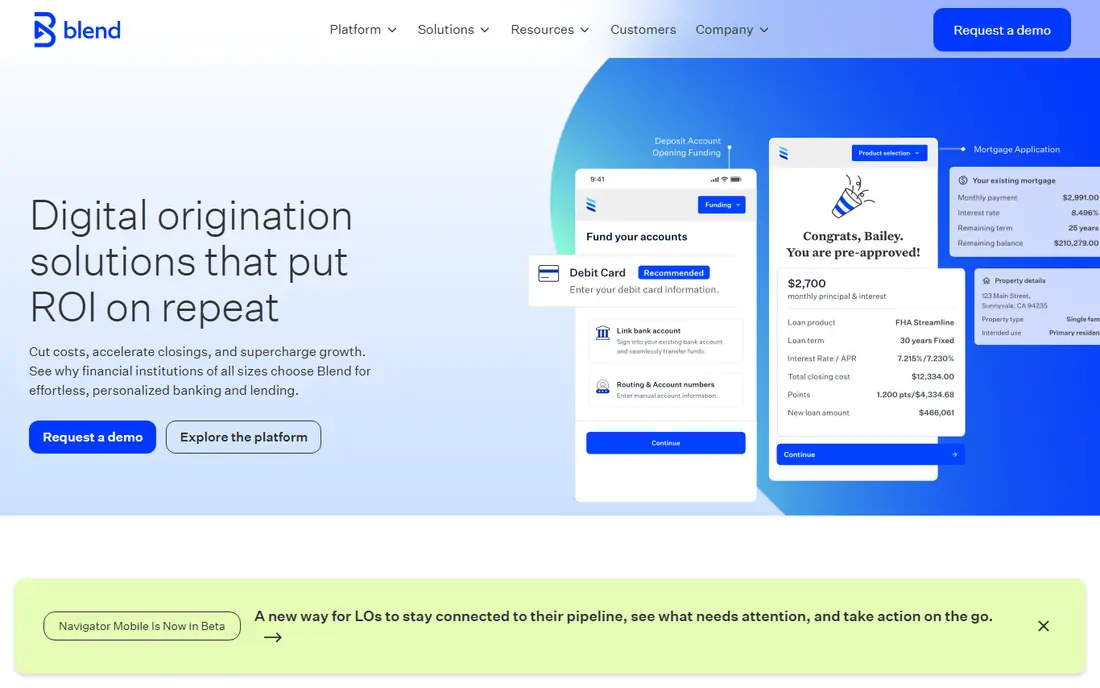
Blend is a digital lending platform with document automation built into mortgage origination. Borrowers upload documents through a portal, the system helps verify data and flags missing items, and the workflow connects with major loan origination systems. That borrower facing design can reduce back and forth emails and speed up the early stages of a loan.
The trade-off is scope. Blend is a full lending platform, not a standalone extraction tool, so a lender that only needs document extraction may pay for breadth it does not use. Pricing is quoted, and the right comparison is the total workflow value, not a single document feature.
- Borrower friendly portal for uploads
- Document verification in the workflow
- LOS integrations
- Quote only pricing
- Document extraction is part of a wider platform
- Smaller lenders may need only part of it

DocMagic has served lenders, settlement providers, investors and borrowers since 1987, with a focus on compliant document generation, eSign, eClosing and audit trails. It generates closing packages, supports electronic notarization where allowed, and integrates with loan origination systems, point of sale tools and settlement platforms. That compliance focus matters when a document error can delay a closing.
The drawback is that DocMagic is an enterprise tool with quoted pricing and a setup that benefits from experienced staff. A small broker that only needs simple eSign may find a lighter tool faster, while a lender that needs compliant, investor ready documents at volume will value DocMagic depth.
- Long record in mortgage documents
- Compliant document generation
- EClosing and eNotary support
- Quote only pricing
- Enterprise setup
- Interface reflects its long history

First American Docutech, now part of First American, provides document generation, eSign and eClosing tools for mortgage lenders. It helps a lender produce compliant loan documents, collect signatures electronically and move toward a digital closing, with integrations for common origination systems. The First American backing also links it to title and settlement services that many lenders already use.
Pricing is quoted, and the sales process can feel formal compared with a self serve tool. A lender should ask for a scoped quote by loan volume and document types, and check which eClosing and remote online notarization options apply in the states where it lends.
- Document generation for mortgage
- ESign and eClosing tools
- Integrations with LOS platforms
- Quote only pricing
- Part of a larger company, so sales can be formal
- Setup needs planning
Floify helps lenders collect mortgage documents through a borrower portal with checklists, secure uploads and automated reminders. Loan officers can see what is missing, message the borrower in the same system and push data to a loan origination system. Integrations include DocMagic and other mortgage tools, which helps a small lender build a coherent stack.
Floify is not a full loan origination system, so a lender that needs underwriting, pricing and secondary market tools will still need an LOS. Pricing is not published as a simple per user rate, so a buyer should request a quote by user count and loan volume.
- Clear borrower portal
- Document checklists and reminders
- LOS and DocMagic integrations
- Pricing is not published simply
- It is a point of sale and collection tool, not a full LOS
- Larger lenders may need more
SimpleNexus, now part of nCino, is a mobile first borrower portal for mortgage lenders. Borrowers can apply, upload documents, sign disclosures and message their loan team from a phone, which suits borrowers who do most of their paperwork on mobile. The platform connects with loan origination systems, pricing engines and other mortgage tools.
The main caution is change after acquisition. A lender should confirm the current contract terms, support path and integration list under nCino ownership. Pricing is quoted, and a small lender should ask about minimums and onboarding before assuming SimpleNexus fits a low volume shop.
- Mobile first borrower experience
- Document upload and eSign
- Integrations with LOS and pricing tools
- Quote only pricing
- Now part of nCino, so contracts may change
- Smaller lenders should check minimums
LendingPad is a cloud loan origination system with document management built into the loan workflow. It covers application, processing, underwriting support and closing documents, with integrations for credit, pricing, DocMagic and other mortgage services. Third party comparisons have reported broker seat pricing near $59 per month, with lender pricing by quote, so a buyer should confirm the current rate for their user type.
The interface is functional rather than polished, and a new team will need training to use the full workflow well. For a broker or small lender that wants one cloud system for origination and documents, rather than stitching together several tools, LendingPad is a practical option.
- Cloud loan origination system
- Document management in the workflow
- Broker friendly pricing reports
- Pricing varies by user type
- Interface is functional rather than polished
- Setup needs training
MeridianLink Mortgage is an established loan origination and document workflow platform used by banks, credit unions and mortgage lenders. It supports application intake, processing, document generation and compliance checks in a single system, with integrations for credit, verification and closing services. That breadth helps a larger lender keep documents, tasks and compliance in one audit trail.
MeridianLink is an enterprise purchase with quoted pricing and an implementation that needs planning. A small broker may find it heavy compared with Floify plus a light LOS, while a credit union or bank that needs a governed, auditable workflow will value its depth.
- Established mortgage LOS
- Document and compliance workflow
- Broad lender and credit union use
- Quote only pricing
- Enterprise implementation
- Smaller brokers may find it heavy
Ocrolus is an AI document automation tool that extracts and verifies data from mortgage documents such as bank statements, pay stubs, tax forms and W-2s. It can flag tampering signals and return structured data that a lender system can use for underwriting checks, which reduces manual data entry and review time. An API lets a lender plug Ocrolus into an existing LOS or workflow.
Ocrolus is not a loan origination system or a closing document generator, so a lender will still need those tools. Pricing is quoted by volume, and integration needs technical time. For a lender with high document volume and a real data entry bottleneck, Ocrolus can be the most direct fix in this list.
- AI extraction from bank statements and pay stubs
- Fraud signals
- API for lender workflows
- Quote only pricing
- It is an extraction layer, not a full LOS
- Needs developer or integration work
Maxwell is built for small and mid-sized lenders that need a borrower portal, document collection and diligence tools without a full enterprise platform. Borrowers can upload documents, track loan status and communicate with the loan team, while staff get checklists and workflow views for each file. That focus makes Maxwell easier to adopt than a large LOS for a lean team.
The limit is scope. Maxwell does not replace a full loan origination system for a large lender, and its vendor size is smaller than Blend or MeridianLink. A small lender should check integrations, support hours and data export options, and confirm that Maxwell fits its LOS before buying.
- Borrower portal and document collection
- Built for small and mid-sized lenders
- Diligence tools
- Quote only pricing
- Smaller vendor than Blend or MeridianLink
- Full LOS features are limited
How we picked these
We compared official product pages, documentation and current mortgage software guides, and we kept only tools that exist and work in October 2026 and truly fit mortgage document automation. We looked for document generation, collection, extraction, eSign, compliance and borrower experience, with a mix of enterprise and small lender options. Where pricing was quoted, we used See website rather than inventing a number.
What to check before you buy
Start with your document bottleneck. If borrowers are slow to upload, a portal such as Floify, SimpleNexus or Maxwell may help most. If closing documents have errors, DocMagic or Docutech may help most. If staff spend hours typing data from statements, Ocrolus may help most. Buying the wrong fix will not speed up the loan, even if the tool is good.
Next, check compliance and investor fit. Ask how documents stay current with investor and regulatory changes, how audit trails work, which states support remote online notarization, and how data is stored and secured. Finally, test integrations with your LOS, credit, verification and closing vendors on a real loan file, not just a demo file.
Questions to ask a vendor
Ask who updates document templates, how quickly a change reaches production, what happens when a document fails a compliance check, and how you export a complete loan file if you leave. Those answers matter more than a feature list, because mortgage documents must be right every time.
Frequently asked questions
What is the best software for mortgage document automation?
Blend suits a digital borrower workflow, DocMagic and Docutech suit compliant closing documents, and Ocrolus suits AI extraction. The best mortgage document automation software depends on whether your bottleneck is collection, generation or data entry.
What is the best mortgage document automation platform for a small lender?
Floify, SimpleNexus and Maxwell are the most practical small lender picks. They offer borrower portals and document collection without the full weight of an enterprise LOS.
What are the best mortgage document automation tools for eClosing?
DocMagic and First American Docutech are the strongest eClosing picks here, with document generation, eSign and eNotary support where state law allows it. Check state rules and investor acceptance before promising a fully digital closing.
How much does mortgage document automation software cost?
Most tools in this list use quoted pricing based on loan volume, users and integrations. Ask for a written quote that separates platform fees, per loan fees, implementation and support, because those items can change the total sharply.
Can AI extract data from bank statements and pay stubs?
Yes. Tools such as Ocrolus and Instabase style platforms extract structured data from statements, pay stubs and tax forms, and can flag tampering signals. A human should still review any document that affects an underwriting decision.
Is this article financial advice?
No. This is not financial advice, and it is not legal or compliance advice. Lenders should confirm investor rules, state law and compliance requirements with qualified advisers before changing document systems.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 zscaler alternatives
Best Zscaler Alternatives in 2026
Looking for zscaler alternatives? We compare 9 SASE and zero trust platforms on architecture, data protection, pricing, and fit for your network and team.
Read → zapier alternatives free
Best Zapier Alternatives Free in 2026
Nine automation tools for zapier alternatives free in 2026, all with genuinely free tiers, plus free plan limits, starting prices and upgrade paths explained.
Read → which platform is best for online reputation
Which Platform Is Best for Online Reputation in 2026
Wondering which platform is best for online reputation? We compare 8 review, listing, and response tools for small and multi-location businesses and agencies.
Read →