 ProMapRanker
Best Mobile Banking App in 2026

Key takeaways
- Chase, Bank of America, and Wells Fargo suit readers who want branches as well as an app.
- Ally, Chime, and Discover suit readers who want low fees and simple online banking.
- Capital One and SoFi suit readers who also want credit tools or investing in the same app.
- Check fee waiver conditions, ATM access, and FDIC insurance before choosing, because headline features hide real costs.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 Chase | full-service banking with branches | Free | Yes | Visit |
 Capital One | banking plus credit tools | Free | Yes | Visit |
 Ally Bank | online savings and budgeting tools | Free | Yes | Visit |
 Chime | no-fee daily banking | Free | Yes | Visit |
 SoFi | banking plus investing and loans | Free | Yes | Visit |
 Bank of America | large bank with assistant tools | Free | Yes | Visit |
 Wells Fargo | branch banking with alerts | Free | Yes | Visit |
 Discover | cashback debit and simple banking | Free | Yes | Visit |
The best mobile banking apps
Disclaimer: This is not financial advice. Banking terms, rates, and fees change, and the right account depends on income, spending, and access needs. Check FDIC insurance, fee terms, and the current rate on the bank site before opening an account. The apps below cover branch banks and online banks, so readers can compare access, fees, and safety tools side by side.
For readers who want full-service banking with branches, Chase is a natural place to start. Chase suits readers who want branches, a full app, and many account types in one place. Its clearest strength is a large branch network joined to a broad app. That focus helps a reader decide quickly, instead of comparing long feature lists with no clear winner.
In daily use, Chase is best judged by how it handles the work it claims to do well. The pros point to large branch and atm network; broad app features; zelle transfers. Check the current plan page before paying, because plan names and limits change, and the free tier may cover less than an older review suggests.
The honest catch is some accounts need conditions to avoid fees. Some accounts need conditions to avoid fees; app depth can feel busy Before committing, try the free plan or trial on one real project, invite the people who will actually use it, and confirm that exports, mobile access, and support meet the need. If any of those fail, move to the next option on this list.
- Large branch and ATM network
- Broad app features
- Zelle transfers
- Some accounts need conditions to avoid fees
- App depth can feel busy
If banking plus credit tools is the main goal, Capital One deserves a close look. Capital One combines mobile banking with credit cards and credit monitoring in one app. Its clearest strength is no-fee checking options joined to credit tools. That focus helps a reader decide quickly, instead of comparing long feature lists with no clear winner.
In daily use, Capital One is best judged by how it handles the work it claims to do well. The pros point to no-fee checking options; virtual cards; credit monitoring tools. Check the current plan page before paying, because plan names and limits change, and the free tier may cover less than an older review suggests.
The honest catch is branch access is limited compared with large branch banks. Branch access is limited compared with large branch banks; rates change Before committing, try the free plan or trial on one real project, invite the people who will actually use it, and confirm that exports, mobile access, and support meet the need. If any of those fail, move to the next option on this list.
- No-fee checking options
- Virtual cards
- Credit monitoring tools
- Branch access is limited compared with large branch banks
- Rates change
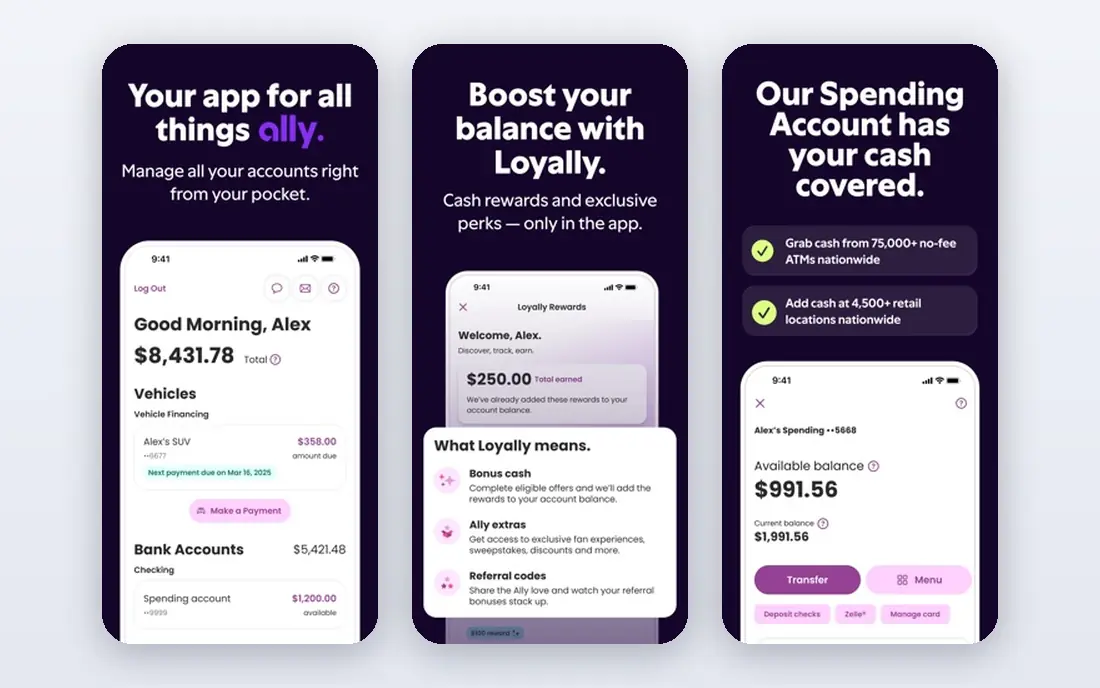
Start with Ally Bank when online savings and budgeting tools matters more than having every extra feature. Ally Bank is an online bank known for savings tools, buckets, and clear fee terms. Its clearest strength is online banking with savings buckets and no branch overhead. That focus helps a reader decide quickly, instead of comparing long feature lists with no clear winner.
In daily use, Ally Bank is best judged by how it handles the work it claims to do well. The pros point to no monthly maintenance fees on many accounts; savings buckets; strong app tools. Check the current plan page before paying, because plan names and limits change, and the free tier may cover less than an older review suggests.
The honest catch is there are no branches, and cash deposits need care. No branches; cash deposits need care Before committing, try the free plan or trial on one real project, invite the people who will actually use it, and confirm that exports, mobile access, and support meet the need. If any of those fail, move to the next option on this list.
- No monthly maintenance fees on many accounts
- Savings buckets
- Strong app tools
- No branches
- Cash deposits need care
We place Chime here for people focused on no-fee daily banking. Chime suits readers who want simple, no-fee daily banking and early access to direct deposit. Its clearest strength is no-fee daily banking with early direct deposit. That focus helps a reader decide quickly, instead of comparing long feature lists with no clear winner.
In daily use, Chime is best judged by how it handles the work it claims to do well. The pros point to no monthly fees; early direct deposit; simple app design. Check the current plan page before paying, because plan names and limits change, and the free tier may cover less than an older review suggests.
The honest catch is support is app-based, and banking services come through partner banks. Chime is a financial technology company, not a bank, and banking services come through partner banks; support is app-based Before committing, try the free plan or trial on one real project, invite the people who will actually use it, and confirm that exports, mobile access, and support meet the need. If any of those fail, move to the next option on this list.
- No monthly fees
- Early direct deposit
- Simple app design
- Chime is a financial technology company, not a bank, and banking services come through partner banks
- Support is app-based
Consider SoFi first if banking plus investing and loans is at the top of the list. SoFi brings banking, investing, and loan products together for readers who want one finance app. Its clearest strength is banking joined to investing and loan products. That focus helps a reader decide quickly, instead of comparing long feature lists with no clear winner.
In daily use, SoFi is best judged by how it handles the work it claims to do well. The pros point to banking, investing, and loans in one app; automated savings. Check the current plan page before paying, because plan names and limits change, and the free tier may cover less than an older review suggests.
The honest catch is breadth can distract, and terms vary by product. Breadth can distract from basic banking; terms vary by product Before committing, try the free plan or trial on one real project, invite the people who will actually use it, and confirm that exports, mobile access, and support meet the need. If any of those fail, move to the next option on this list.
- Banking, investing, and loans in one app
- Automated savings
- Breadth can distract from basic banking
- Terms vary by product
Bank of America stands out for readers who need large bank with assistant tools. Bank of America suits readers who want branches, a virtual assistant, and investing links in one app. Its clearest strength is a large branch network with assistant tools. That focus helps a reader decide quickly, instead of comparing long feature lists with no clear winner.
In daily use, Bank of America is best judged by how it handles the work it claims to do well. The pros point to large branch network; erica assistant; merrill investing link. Check the current plan page before paying, because plan names and limits change, and the free tier may cover less than an older review suggests.
The honest catch is some accounts need conditions to avoid fees. Some accounts need conditions to avoid fees; app has many menus Before committing, try the free plan or trial on one real project, invite the people who will actually use it, and confirm that exports, mobile access, and support meet the need. If any of those fail, move to the next option on this list.
- Large branch network
- Erica assistant
- Merrill investing link
- Some accounts need conditions to avoid fees
- App has many menus
For a direct answer to branch banking with alerts, Wells Fargo is a strong candidate. Wells Fargo offers branch banking, alerts, and credit score views in a broad mobile app. Its clearest strength is branch banking with alerts and score views. That focus helps a reader decide quickly, instead of comparing long feature lists with no clear winner.
In daily use, Wells Fargo is best judged by how it handles the work it claims to do well. The pros point to large branch network; real-time alerts; fico score view. Check the current plan page before paying, because plan names and limits change, and the free tier may cover less than an older review suggests.
The honest catch is some accounts need conditions to avoid fees. Some accounts need conditions to avoid fees; past trust issues remain a concern for some readers Before committing, try the free plan or trial on one real project, invite the people who will actually use it, and confirm that exports, mobile access, and support meet the need. If any of those fail, move to the next option on this list.
- Large branch network
- Real-time alerts
- FICO score view
- Some accounts need conditions to avoid fees
- Past trust issues remain a concern for some readers
When cashback debit and simple banking is the priority, Discover makes the shortlist on its own merits. Discover suits readers who want cashback on debit spending and simple online banking. Its clearest strength is cashback debit with simple no-fee accounts. That focus helps a reader decide quickly, instead of comparing long feature lists with no clear winner.
In daily use, Discover is best judged by how it handles the work it claims to do well. The pros point to cashback debit; no-fee accounts; fico score view. Check the current plan page before paying, because plan names and limits change, and the free tier may cover less than an older review suggests.
The honest catch is there are no branches, and the product range is narrower. No branches; product range is narrower than large banks Before committing, try the free plan or trial on one real project, invite the people who will actually use it, and confirm that exports, mobile access, and support meet the need. If any of those fail, move to the next option on this list.
- Cashback debit
- No-fee accounts
- FICO score view
- No branches
- Product range is narrower than large banks
How we picked these
Start with access. If cash deposits, in-person help, or a local branch matter, a branch bank has a clear edge. If low fees and savings tools matter more, an online bank may win. Next, check security tools: biometric login, transaction alerts, card lock, and two-factor sign-in. Turn those on after opening an account, and review transactions each week. Also confirm FDIC insurance and read the fee schedule for overdraft, ATM, and account conditions. A free app can still cost money through fees that only appear in the fine print.
Choosing a mobile banking app safely
Compare the total cost, not just the app design. Look at monthly fees, fee waiver rules, ATM fees, and overdraft terms, and add them up for a normal month. Then test the daily tasks: deposit a check, send money, lock a card, and find help in the app. If help is hard to find, that matters when a payment goes wrong. For savings, compare the current rate and any balance conditions, and remember that rates change with the market. Keep a second payment method available while switching banks, so bills and direct deposits do not fail during the move.
Frequently asked questions
What is the best mobile banking apps for most people?
There is no single winner for every reader, because budget, team size, and daily habits change the answer. Start with the option whose best_for line matches the main job, use its free plan or trial on a real task, and keep the one that the team actually opens each day.
Are there good free mobile banking apps options?
Yes, several options on this list offer a free plan, but free plans usually limit seats, storage, or advanced features. Read the free-plan line in the table, then test the exact feature that matters most before assuming the free tier will be enough long term.
How much should I expect to pay?
That depends on whether the price is per user, per account, or per year, and on how many people need paid seats. Use the starting_price line as a guide only, check the vendor pricing page for taxes and add-ons, and compare the annual total rather than the monthly headline.
Can I switch later if I pick the wrong one?
In most cases, yes, but switching takes time if data, templates, or team habits are tied to one tool. Before paying for a year, confirm that export is available, test it with a small sample, and keep a copy of important work outside the tool.
How do I choose between the top two options?
List the three tasks that will happen every week, then test those tasks in both tools. The better choice is usually the one with fewer steps for those tasks, clearer pricing, and support that answers in a useful timeframe, not the one with the longest feature list.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 zendesk alternatives
Best Zendesk Alternatives in 2026
Compare the best Zendesk alternatives in 2026, from budget help desks to AI-first support tools, with current pricing, free plans, and honest trade-offs.
Read → wordpress alternatives
Best WordPress Alternatives in 2026
Looking for the best WordPress alternatives? We compare 8 free and paid options for blogs, business sites, stores, and developer-led projects in 2026.
Read → which real estate company has the best training
Best Real Estate Company Training in 2026
Compare which real estate company has the best training, from Keller Williams and eXp to Compass and Coldwell Banker, by program, mentor, and fit in 2026.
Read →