 ProMapRanker
Best Life Insurance Company in 2026

Whole life and financial strength · Pricing starts at: See website
Key takeaways
- Northwestern Mutual, New York Life, MassMutual and Guardian lead on financial strength, each holding top AM Best ratings.
- MassMutual stands out for whole life cash value growth, while Guardian is a strong pick for term and customer service.
- State Farm suits buyers who want term value plus a local agent, and Mutual of Omaha suits seniors and simpler applications.
- Ethos and Pacific Life suit faster or more flexible applications, but policy details still need a careful read.
- Life insurance is not personalised advice, so compare quotes for the same coverage amount and term, and check exclusions before you buy.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
| Northwestern Mutual | Whole life and financial strength | See website | No | Visit |
 New York Life | Long-term permanent cover | See website | No | Visit |
 MassMutual | Whole life cash value growth | See website | No | Visit |
 Guardian Life | Term cover and customer service | See website | No | Visit |
 State Farm | Term value and local agent support | See website | No | Visit |
 Mutual of Omaha | Seniors and simpler applications | See website | No | Visit |
 Ethos | Fast online term applications | See website | No | Visit |
 Pacific Life | Flexible permanent and term options | See website | No | Visit |
The best life insurance companies
We compared official product pages, financial strength ratings, customer satisfaction studies and public reviews for leading US life insurers. The best company for life insurance depends on whether you want term cover for a set period, permanent cover for life, or a policy that builds cash value. All eight companies below are major US insurers, though product availability varies by state and health profile. This article is general information only, not personalised financial advice.
Northwestern Mutual is our pick for buyers who want maximum financial strength in a permanent policy. It holds AM Best's top A++ rating, and it has paid dividends on eligible whole life policies for many years, though dividends are never guaranteed. Its range covers term, whole life and universal life, so one insurer can serve both temporary and lifelong needs.
The honest catch is price and process. Whole life costs far more than term for the same death benefit, and Northwestern Mutual is typically sold through financial representatives rather than a fully online flow. That advice can help with complex planning, but it is slower if you want a quick term quote. For a permanent policy you may hold for decades, strength and dividend history matter, and Northwestern Mutual leads on both.
- Top A++ AM Best rating
- Long dividend history on eligible policies
- Broad term and permanent options
- Often sold through agents, so online-only buyers may prefer another route
- Whole life premiums are higher than term
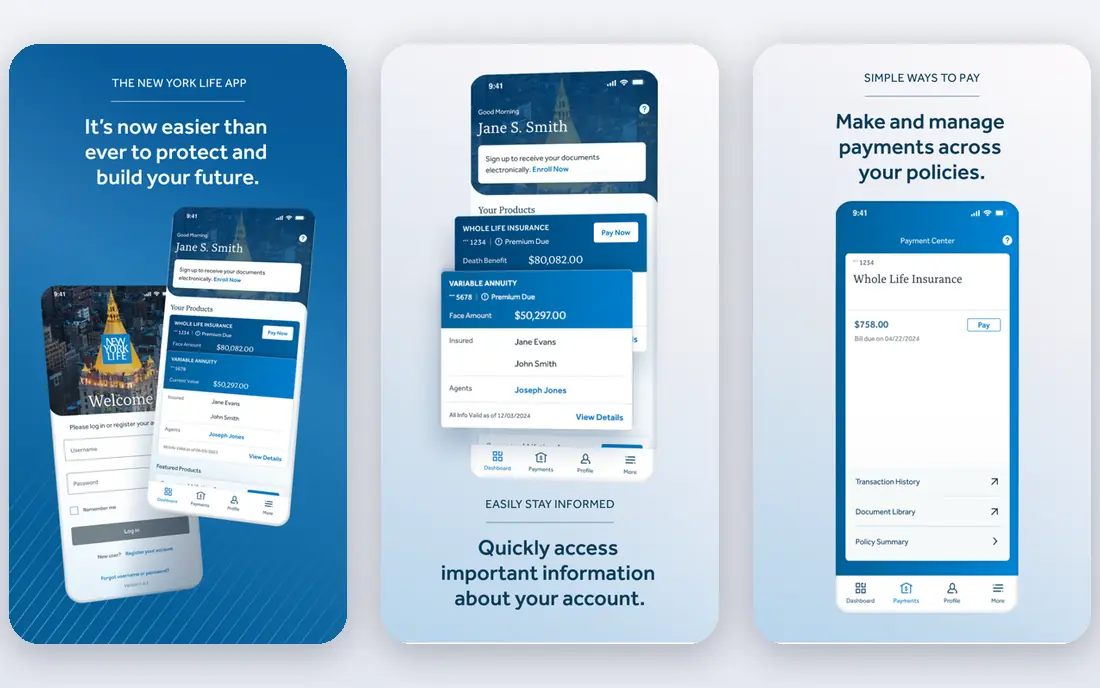
New York Life is the best life insurance company for buyers who want a large mutual insurer with a long track record. It holds top ratings from major agencies, offers a broad range of permanent policies, and has paid dividends on eligible policies for many years. Its size and history reassure buyers who worry whether an insurer will still be strong in forty years.
The trade-off is the buying model. New York Life sells mainly through agents, so shoppers who want an instant online term quote may find Ethos or State Farm faster. Term pricing also varies by profile, so a quote comparison matters. For permanent cover held for life, New York Life is a benchmark against which other insurers should be measured.
- Top A++ AM Best rating
- Broad permanent policy range
- Long dividend history on eligible policies
- Agent-led sales model
- Term pricing can be less competitive than digital rivals for some profiles
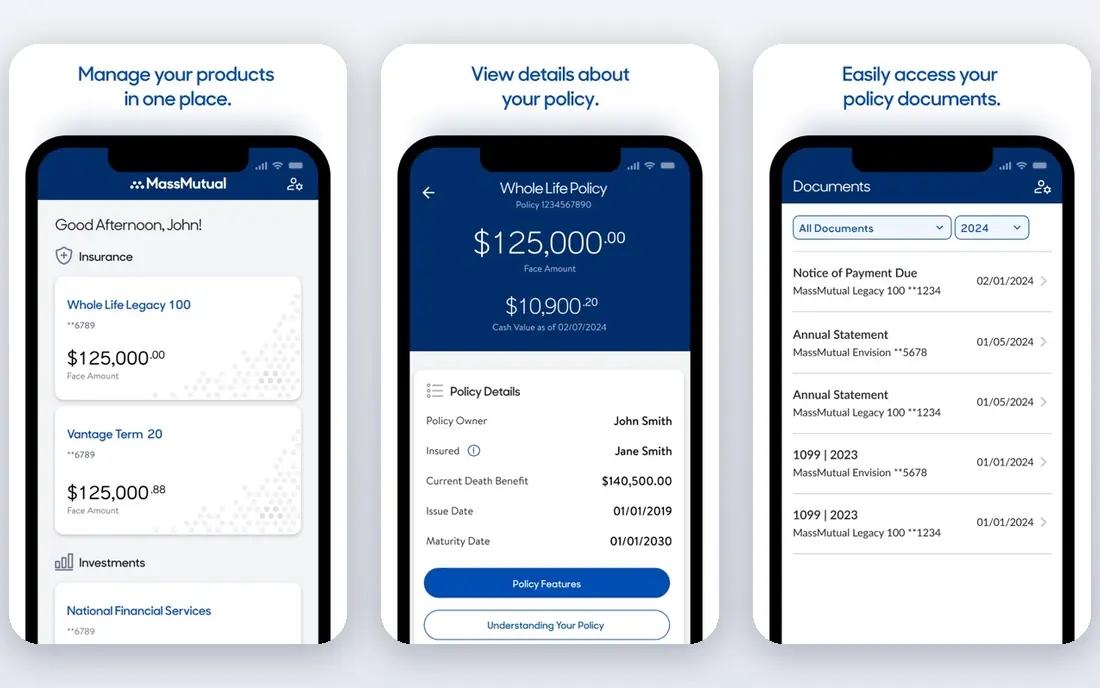
MassMutual stands out for whole life buyers who care about cash value growth. Published comparisons name it among the strongest for whole life cash value, and it holds a top A++ financial strength rating. Its term policies are also competitive, so buyers can start with term and consider permanent cover later.
The weakness is cost and complexity. Whole life premiums are much higher than term, and permanent applications involve more underwriting detail. MassMutual is not the cheapest term quote for every profile, so compare it against State Farm and Guardian for term. For a whole life policy intended to build value over decades, MassMutual is a leading candidate.
- Top A++ AM Best rating
- Strong whole life cash value performance in published comparisons
- Term and permanent options
- Whole life is expensive compared with term
- Application process can be detailed for permanent policies
Guardian Life is a strong all-round pick, and it is often named the best insurance life company for customer experience. It holds a top financial strength rating, offers term and permanent policies, and adds useful riders such as disability-related options that suit professionals. Its customer satisfaction scores are among the strongest in the industry.
The catch is distribution and price variation. Guardian often sells through agents, and term pricing depends heavily on health class, so a healthy applicant and an applicant with health issues can see very different results. Get a Guardian quote alongside MassMutual and State Farm, and check rider details, since those extras can be worth more than a small premium difference.
- Top A++ AM Best rating
- Strong customer satisfaction record
- Flexible term and permanent options plus disability riders
- Agent-led distribution in many cases
- Pricing varies by health profile and state
State Farm is the best life insurance company for buyers who already trust a local agent. Its term pricing is competitive for many healthy applicants, and bundling life with home and auto can simplify billing and service. Agents can also explain term lengths, conversion options and riders in person, which helps first-time buyers.
The limit is permanent depth. State Farm offers permanent policies, but its range is narrower than Northwestern Mutual, New York Life or MassMutual for complex permanent planning. For straightforward term cover, especially when you already insure a home or car with State Farm, it is a strong and convenient quote. Check conversion terms, since the right to convert term to permanent cover without a new exam matters if your health changes.
- Competitive term pricing for many profiles
- Local agent network
- Bundling with home and auto
- Permanent policy range is narrower than mutual specialists
- Pricing varies by state
Mutual of Omaha suits older buyers and people who want a simpler application. It scored highly for customer satisfaction in J.D. Power's 2026 study, and it offers guaranteed issue whole life for seniors who might struggle with full underwriting elsewhere. Its term range is broad, and its brand is familiar to many families.
The trade-off is price for younger buyers. Healthy younger applicants may find cheaper term quotes from State Farm, Ethos or Guardian, so Mutual of Omaha should not be the only quote. For seniors, final expense cover or a simplified application, it is a leading option, and its service record supports that choice.
- Strong customer satisfaction in J.D. Power studies
- Guaranteed issue whole life options for seniors
- Broad term range
- Pricing for younger healthy buyers can trail digital term rivals
- Some products are simplified issue with lower limits
Ethos is the digital pick among the best life insurance companies. Its online application can approve many healthy applicants without a medical exam, and decisions often arrive quickly. That speed suits busy parents and young professionals who have delayed buying term cover because the traditional process felt slow.
The catch is partner dependence. Ethos policies are issued by partner insurers, so final terms, limits and pricing depend on the matched carrier and your health profile. Complex permanent planning still suits a mutual insurer with an agent. If you want term cover fast and online, Ethos is the easiest first application, and you can compare its quote against State Farm before you commit.
- Online application with many no-exam approvals
- Fast decisions for eligible applicants
- Term and whole life options
- Coverage limits and pricing depend on underwriting partner
- Not suited to complex permanent planning
Pacific Life suits buyers who want flexibility in permanent cover. Its universal life and indexed universal life options allow adjustable premiums and death benefits within limits, which appeals to buyers whose income or needs change over time. It also offers term policies, and its financial strength is solid.
The downside is complexity. Indexed and universal policies involve caps, participation rates and cost-of-insurance charges that are easy to misunderstand, so first-time buyers should get advice before choosing them over simple term or whole life. Pacific Life is best for buyers who understand those trade-offs or work with an adviser, and it rounds out this list with genuine permanent flexibility.
- Broad term, universal and indexed universal options
- Strong financial strength
- Flexible policy design
- Product complexity can confuse first-time buyers
- Agent or broker often needed for best fit
How we picked these
We compared official product pages, AM Best financial strength ratings, customer satisfaction studies and public reviews for major US life insurers. We favoured companies with top or near-top strength ratings, clear product ranges and a distinct advantage: whole life strength, term value, service, senior access, speed or flexibility. We treated dividends as never guaranteed, and we avoided fixed premium figures, since life premiums depend on age, health, coverage amount, term and state.
How to choose life insurance without overspending
Start with the amount and length you actually need. Term cover for the years your family depends on your income, such as until a mortgage is paid or children are independent, is often the most affordable route. Permanent cover suits lifelong needs, such as estate planning or a dependent who needs lifelong support, but it costs far more for the same death benefit.
Next, compare quotes for identical coverage amounts and terms, and check conversion options, exclusions and riders. A term policy that can convert to permanent cover without a new medical exam is valuable if your health changes. Finally, be honest on the application, since misstatements can affect a claim, and review beneficiaries and coverage every few years as income, debts and family circumstances change. This is general information, not advice for your situation, so consider a licensed adviser for complex needs.
Frequently asked questions
What is the best life insurance company overall?
Northwestern Mutual, New York Life, MassMutual and Guardian all hold top financial strength ratings and rank highly in published comparisons. The best life insurance company for you depends on whether you want term or permanent cover, your health profile and your budget.
Which company is best for whole life insurance?
MassMutual stands out for whole life cash value growth, while Northwestern Mutual and New York Life lead on dividend history and financial strength. Whole life costs far more than term, so compare illustrated values and guaranteed figures, not just dividends.
What is the best company for term life insurance?
State Farm offers strong term value with agent support, Guardian combines term with strong service, and Ethos offers the fastest online term application for eligible buyers. Compare quotes for the same amount and term length before you choose.
How much life insurance do I need?
A common starting point is ten to twelve times annual income, plus debts and future costs such as education, but the right amount depends on your family, mortgage and savings. Use a needs calculator, then adjust for debts, existing cover and a partner income.
Do I need a medical exam for life insurance?
Many term policies now offer no-exam approval for healthy applicants, especially through Ethos and other digital insurers, while larger amounts and permanent policies often require an exam. No-exam policies can cost more or offer lower limits, so compare both routes.
Are dividends on whole life policies guaranteed?
No, dividends are never guaranteed, though long-established mutual insurers have paid them for many years. Treat dividends as a possible bonus, and judge a whole life policy on its guaranteed death benefit and guaranteed cash value first.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 youtube alternatives
Best YouTube Alternatives in 2026
Looking for youtube alternatives in 2026? We compare Vimeo, Dailymotion, Twitch, Rumble, and more on price, audience, monetization, control and privacy.
Read → what's the best ai tool for photo editing
What Is the Best AI Tool for Photo Editing in 2026
What is the best AI tool for photo editing? We compare ten tools for 2026, from Photoshop and Lightroom to Luminar, Topaz, Canva and mobile editors today.
Read → twitter alternatives
Best Twitter Alternatives in 2026
Compare the best twitter alternatives for 2026, from Bluesky, Threads, and Mastodon to Reddit, Tumblr, and Micro.blog, with free plans and audience notes.
Read →