 ProMapRanker
Best IRA Rollover Companies in 2026

Key takeaways
- This is not financial advice. Rollover tax rules matter, so use a direct rollover where possible and check the 60 day rule before taking a check yourself.
- Fidelity is our pick for most rollovers, with $0 account fees, $0 listed trades and a guided rollover process.
- Charles Schwab is the best pick if you want a dedicated Rollover Consultant on the phone at no cost.
- Vanguard suits buy and hold investors who want low cost funds and plan to leave the money invested long term.
- A rollover company should not charge you to receive the money, so compare transfer out fees at your old provider as well as the new one.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 Fidelity | Most rollovers | $0 account fee | No | Visit |
 Charles Schwab | Phone guided rollovers | $0 account fee | No | Visit |
 Vanguard | Low cost buy and hold | $0 to open, $25 annual fee waived with e-delivery | No | Visit |
 E*TRADE | Web platform and research | $0 account fee | No | Visit |
 Merrill Edge | Bank of America customers | $0 account fee | No | Visit |
 Interactive Brokers | Advanced investors | From $0 commissions | No | Visit |
 Robinhood | Simple mobile rollovers | $0 account fee | No | Visit |
 SoFi | Simple investing with guidance | $0 account fee | No | Visit |
 Betterment | Hands off managed rollovers | See website | No | Visit |
The best ira rollover companies
We compared official rollover pages, pricing guides and account fee schedules for US brokers and robo advisors that accept 401k rollovers into IRAs today. A rollover IRA here means an IRA that receives money from a former employer plan, usually through a direct trustee to trustee transfer. Fees noted are account fees, not fund expenses, which apply separately to the investments you choose.
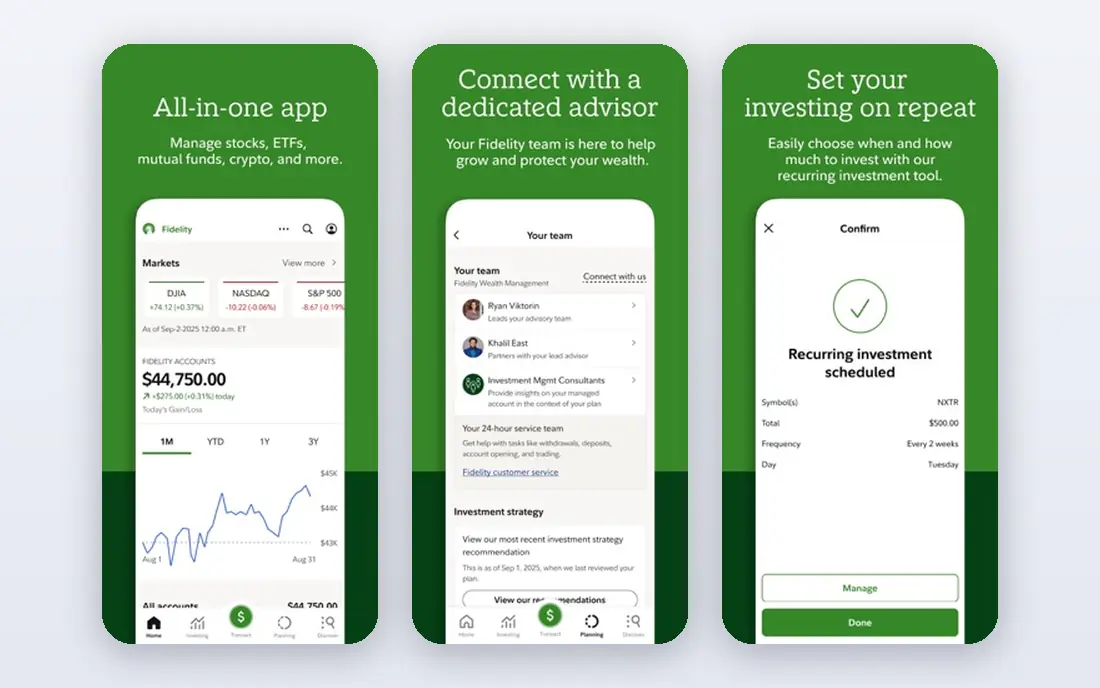
Fidelity is our pick for most rollovers because it removes the common friction points. There is no account fee to open or maintain a rollover IRA, listed trades are $0 online, and the rollover process is laid out in clear steps with phone help when the old plan paperwork gets confusing. The fund range covers everything from zero expense ratio index funds to thousands of other funds, stocks, ETFs and bonds.
The catch is mostly about choice overload. New rollover savers can feel lost among thousands of funds, so start with a broad index or target date fund if you want a simple portfolio, and use Fidelity's guidance tools before picking individual stocks. For a straightforward, low cost rollover with strong support, Fidelity is hard to beat.
- $0 account fee and $0 online listed stock and ETF trades
- Guided three step rollover process with phone support
- Zero expense ratio funds available for some index strategies
- No standing advertised rollover bonus in recent checks
- Investment choice can feel large for first time rollover savers
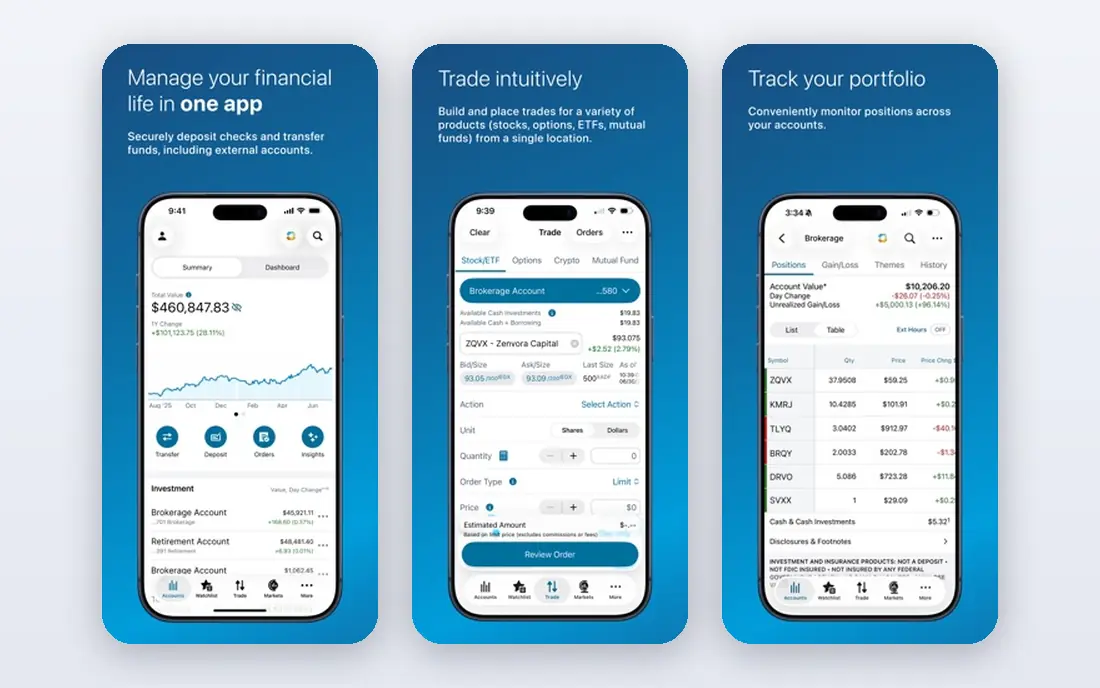
Charles Schwab is the best pick if you want a person to walk you through the move. Its Rollover Consultants help with the old plan forms, the account setup and the transfer steps at no cost, which matters when a former employer's paperwork is unclear. The account itself costs $0 to open and maintain, listed trades are $0 online, and branch access adds a human option that app only brokers cannot offer.
The fee to note is on exit, not entry: a full transfer out costs $50, while partial transfers are $0, based on published pricing. That should not stop a rollover, since most people keep a rollover IRA for years, but it is worth knowing before you move money in. For guided help and a full service broker, Schwab is a strong, safe choice.
- $0 to open and maintain a rollover IRA
- Dedicated Rollover Consultants available by phone at no cost
- 400 plus US branches for in person help
- Full transfer out fee of $50 applies if you later move the whole account elsewhere, though partial transfers out are $0
Vanguard suits investors who want to roll over a 401k, pick a few low cost funds, and leave the portfolio alone for years. Its index funds and ETFs are among the cheapest in the industry, and the brokerage IRA opens with $0, with the $25 annual service fee waived for clients who elect e-delivery. Fractional purchases of Vanguard ETFs from $1 help invest the full rollover amount without leftover cash.
The trade off is hand holding. Vanguard's rollover process expects you to contact the old plan yourself, with phone support available if you get stuck, and deposits can take two to four weeks in published guidance. If you want a consultant to manage the move, Schwab or Fidelity fit better. If you want low costs and a simple portfolio, Vanguard is a classic pick.
- Low cost index funds and ETFs with a long track record
- $0 online stock and ETF trades
- Simple portfolio building for long term investors
- $25 annual account service fee unless waived by e-delivery or other qualifying terms
- Rollover process is more self serve, with phone help if you get stuck
E*TRADE, part of Morgan Stanley, is a good rollover home for investors who want a capable web platform and research alongside a retirement account. The rollover IRA opens with no account minimum and no annual fee on published terms, listed trades are $0 online, and the platform covers stocks, ETFs, mutual funds and bonds. Investors who also use Morgan Stanley banking or advice services get a joined up view.
The fee to note is the $75 full transfer out charge in published comparisons, so moving the whole account away later costs more than at Schwab or Fidelity. For most rollover savers who plan to stay put, that is a minor point. For active investors who want a strong platform, E*TRADE is a dependable choice.
- $0 account minimum and no annual fee on published terms
- $0 online listed stock and ETF trades
- Strong web platform and Morgan Stanley research
- Full transfer out fee of $75 based on published comparisons
- Rollover guidance is solid but less dedicated than Schwab's consultant team
Merrill Edge is the natural rollover pick for Bank of America customers. The IRA sits alongside checking and savings in one login, branch staff can help with rollover questions in person, and the platform offers stocks, ETFs, mutual funds and guided investing options. That integration saves time for households that already bank with Bank of America and want retirement money in the same place.
The exit fee is $49.95 for a full transfer or closeout on published terms, with partial transfers at $0, so the same stay put logic applies as with other brokers. For non Bank of America customers, Fidelity or Schwab offer a similar service without the banking tie. For Bank of America households, Merrill Edge is a convenient, well supported rollover home.
- $0 account minimum and no annual fee on published terms
- In person help through Bank of America branches
- Integrated view with Bank of America accounts
- Full transfer or IRA closeout fee of $49.95 on published terms
- Fund and advice costs depend on the investments and guidance tier chosen
Interactive Brokers suits advanced investors who want a rollover IRA inside a powerful brokerage account. Lite pricing gives $0 commissions on US listed stocks and ETFs, and the platform covers global markets, bonds and many security types that simpler brokers do not. Experienced traders who manage a rollover alongside active trading will value that breadth.
Most rollover savers do not need that depth, and the platform can feel overwhelming for a first rollover. If your rollover plan is a few index funds held for decades, Fidelity, Schwab or Vanguard will be simpler and better supported. Pick Interactive Brokers when you already know the platform and want its tools inside an IRA.
- IBKR Lite offers $0 commissions on US listed stocks and ETFs
- Very broad market and security access
- Advanced tools for experienced investors
- Platform complexity is high for rollover savers who only want a simple IRA
- Rollover support is less hand held than Schwab or Fidelity
Robinhood is the simple mobile option for a rollover, especially for younger savers who already use the app. The IRA setup is quick, listed trades are $0, and the published 1 percent IRA match on contributions adds a perk that traditional brokers do not offer, subject to terms and holding conditions. For a straightforward rollover into stocks and ETFs, the app is easy to use.
The limit is depth. Retirement guidance, fund research and phone support are lighter than at Fidelity or Schwab, and the match terms should be read carefully, since they carry conditions. If you want a simple, mobile first rollover and you are comfortable choosing your own investments, Robinhood is a fair pick. If you want guided help, choose Schwab or Fidelity.
- Simple mobile IRA setup
- $0 commission on listed stocks and ETFs
- 1 percent match on IRA contributions on published terms, subject to conditions
- Research and retirement guidance are lighter than full service brokers
- Transfer and match terms need a close read before relying on them
SoFi suits rollover savers who want simplicity plus a human to talk to. The IRA opens with no account fee on published terms, automated investing can build a diversified portfolio from a risk questionnaire, and SoFi members can access financial planning help alongside banking, lending and other products. That bundle appeals to savers who want one financial home without a complex platform.
Active investors will find the range narrower than Fidelity or Schwab, and research tools are lighter. For a hands off rollover with automated investing and planning support, SoFi is a solid, low cost choice. For a self directed portfolio with thousands of funds and deep research, a full service broker fits better.
- $0 account fee on published terms
- Simple IRA setup with automated investing options
- Access to financial planners and broader SoFi products
- Investment range and research tools are narrower than full service brokers
- Active traders will want a deeper platform
Betterment is the robo advisor pick for savers who want the rollover managed for them. Answer a risk questionnaire, roll the old 401k into a Betterment IRA, and the platform builds a diversified portfolio, rebalances it and handles the ongoing maintenance. That hands off model suits people who know they will not rebalance a self directed portfolio on their own.
The cost is the management fee, which sits on top of the underlying fund expenses, so check the current plan against the value of the managed service for your balance. Investors who want to pick stocks or funds themselves should choose a self directed broker instead. For a managed, low effort rollover, Betterment is a strong, well established choice.
- Managed portfolios built from your risk profile
- Automatic rebalancing and tax aware features for taxable accounts
- Clear rollover support for moving old 401k money
- Management fee applies on top of fund expenses, so check the current plan
- Less control for investors who want to pick individual stocks
How we picked these
We compared official rollover pages, pricing guides and account fee schedules, and we kept only US companies that accept 401k rollovers into IRAs today. We favored $0 account fees, clear rollover help, broad investment choice and published transfer fees, and we noted where a fee applies on exit rather than entry. We did not claim hands on testing; our comparisons rest on published fees, features and public reviews. This article is educational only and is not financial advice.
How to roll over a 401k without a tax surprise
Use a direct rollover whenever you can. That means the old plan sends the money straight to the new IRA provider, trustee to trustee, so no tax is withheld and no 60 day deadline applies. If you receive a check made out to you instead, you usually have 60 days to deposit it into an eligible IRA, and the old plan may withhold 20 percent for taxes, which you must replace from other funds to complete a full rollover.
Before you move money, compare the old plan and the new IRA on fees, investment choice and creditor protections, because some employer plans offer lower cost funds or stronger protections than an IRA. Check if your old plan charges a transfer out fee, and confirm the new provider's account fee and any management fee. Keep the tax forms: the old plan reports the distribution on Form 1099-R, and the new provider reports the rollover on Form 5498. When in doubt, call the new provider's rollover team before moving money, and consider tax advice for large balances, Roth conversions or mixed pre tax and after tax money.
Frequently asked questions
What is the best company for an IRA rollover?
Fidelity is the best company for most IRA rollovers, with $0 account fees, $0 listed trades and a guided process. Charles Schwab is best for phone guided help through a Rollover Consultant, and Vanguard is best for low cost buy and hold investors. The right pick depends on how much help you want and how you invest.
What is the best rollover IRA company for a 401k?
For a 401k rollover, Fidelity and Charles Schwab lead on low fees and rollover support, with Vanguard close behind for low cost funds. E*TRADE and Merrill Edge are strong alternatives for investors who already use those platforms. Use a direct rollover to avoid withholding and the 60 day deadline.
Does it cost money to roll over a 401k to an IRA?
Most major brokers charge $0 to open and maintain a rollover IRA and $0 to receive the rollover. Your old plan may charge a transfer out fee, and fund expenses apply to the investments you choose. Managed providers such as Betterment add a management fee, so check the full cost before choosing.
What is a direct rollover, and why does it matter?
A direct rollover sends money straight from the old plan to the new IRA provider, trustee to trustee, with no tax withholding and no 60 day deadline. An indirect rollover pays the money to you first, which can trigger 20 percent withholding and a 60 day deposit deadline, with taxes and penalties if you miss it.
How long does an IRA rollover take?
A direct rollover commonly takes one to four weeks, depending on the old plan's paperwork and processing time. Vanguard's published guidance notes deposits typically take two to four weeks. Start the process with the new provider, follow up with the old plan, and do not close the old account until the money has arrived.
Should I roll over a 401k or leave it with my old employer?
Rolling over usually gives more investment choice and consolidates retirement accounts, while leaving it may keep lower cost funds or specific plan protections. Compare fees, funds and protections in both places, and consider tax advice for large balances or Roth conversions before deciding.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 zscaler alternatives
Best Zscaler Alternatives in 2026
Looking for zscaler alternatives? We compare 9 SASE and zero trust platforms on architecture, data protection, pricing, and fit for your network and team.
Read → zapier alternatives free
Best Zapier Alternatives Free in 2026
Nine automation tools for zapier alternatives free in 2026, all with genuinely free tiers, plus free plan limits, starting prices and upgrade paths explained.
Read → which platform is best for online reputation
Which Platform Is Best for Online Reputation in 2026
Wondering which platform is best for online reputation? We compare 8 review, listing, and response tools for small and multi-location businesses and agencies.
Read →