 ProMapRanker
Best Fintech App for Personal Banking in 2026

Key takeaways
- Chime is our pick for most everyday US banking because it charges no monthly fee and offers early direct deposit and a large fee-free ATM network.
- SoFi suits people who want banking, investing, and lending in one app, while Varo suits people who want a chartered digital bank with no monthly fee.
- Revolut is best for travel and multi-currency spending, and Current is best for families and teen accounts.
- This article is general information only and is not financial advice; check FDIC coverage and fee schedules before opening an account.
- Savings rates and overdraft limits change with eligibility and direct deposit, so read the current terms on the provider site.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 Chime | Fee-free everyday banking | Free | Yes | Visit |
 SoFi | All-in-one banking, investing, and lending | Free | Yes | Visit |
 Varo | Chartered digital bank with no monthly fee | Free | Yes | Visit |
 Revolut | Travel and multi-currency spending | Free | Yes | Visit |
 Current | Families and teen accounts | Free | Yes | Visit |
 Cash App | Simple payments plus banking features | Free | Yes | Visit |
 Wise | International transfers and multi-currency balances | Free | Yes | Visit |
 MoneyLion | Banking plus credit building tools | Free | Yes | Visit |
 Dave | Small cash advances for cash flow gaps | Free | Yes | Visit |
The best fintech apps for personal banking
Fintech banking apps promise the same core job as a bank, without branches: checking, savings, a debit card, and an app that shows spending clearly. These nine apps cover everyday banking, travel, families, and cash advances at different strengths.
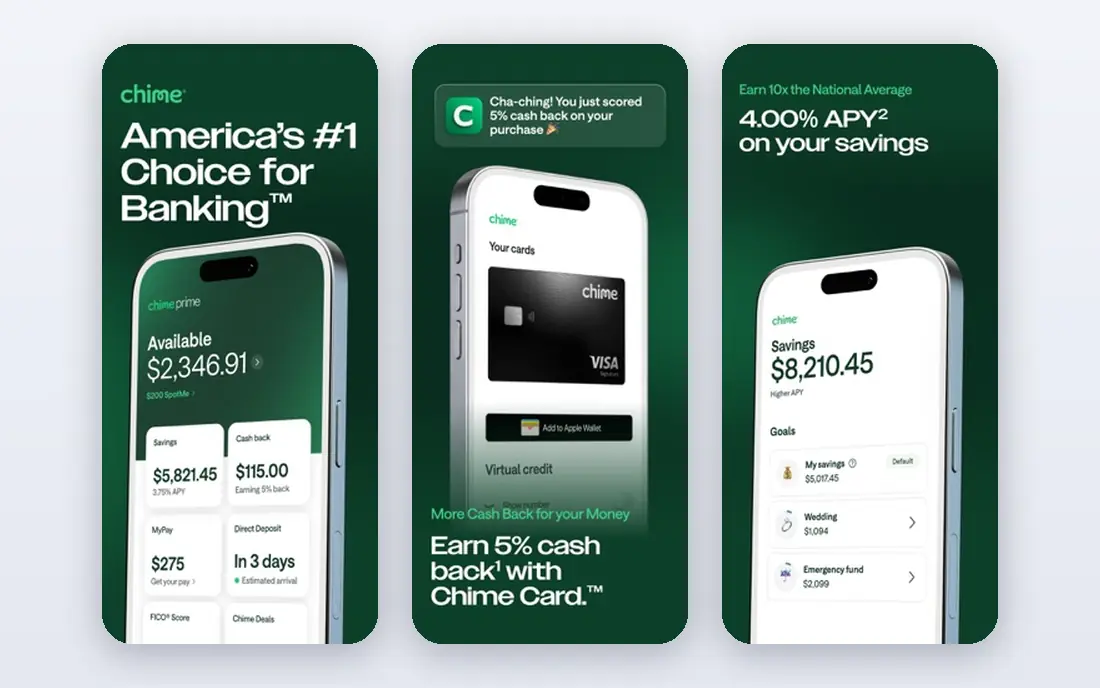
Chime is a financial technology company that offers checking and savings accounts through partner banks, with FDIC insurance through those partners up to the legal limit. Accounts charge no monthly fee, and direct deposit can arrive up to two days early depending on when the payer submits payroll. A large fee-free ATM network covers cash withdrawals in many locations.
The limits sit in the details. Some savings and overdraft features, including SpotMe, require qualifying direct deposits and account history. Cash deposits go through retail partners rather than branches. For everyday US banking without monthly fees, Chime remains the simplest default.
- No monthly fees
- Early direct deposit
- Large fee-free ATM network
- No branches
- Some features need qualifying direct deposit
- Cash deposits need retail partners
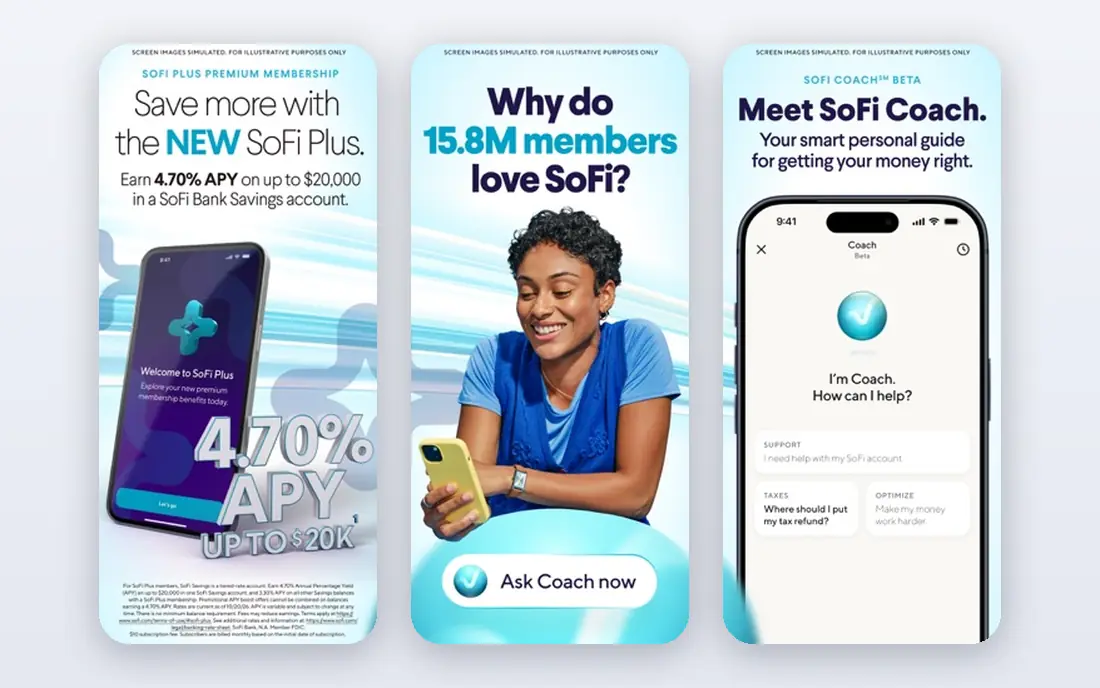
SoFi combines checking, savings, investing, and lending in one app, which suits people who want fewer financial accounts. Checking and savings carry no monthly fee, direct deposit can arrive early, and fee-free ATMs are available through a partner network. Investing and loan products sit in the same login, though each product has its own terms.
Savings rates and some benefits depend on direct deposit or membership conditions, so read current terms before comparing headline rates. SoFi has no branches, so cash handling and in-person help are limited. For an all-in-one money app, SoFi is the broadest option here.
- No monthly fees
- Checking and savings in one app
- Investing and lending alongside banking
- Best savings terms need direct deposit or membership conditions
- No branches

Varo is a chartered digital bank, which means it holds its own banking license rather than operating only through a partner. Accounts charge no monthly fee, direct deposit can arrive up to two days early, and fee-free ATMs are available in network. Savings tools and cashback options support everyday budgeting.
Higher savings rates and some benefits require direct deposit amounts or other conditions, so check the current schedule. The product range is narrower than SoFi, with less emphasis on investing and lending. For people who value a licensed bank with a clean fee structure, Varo is a strong choice.
- No monthly fees
- Chartered bank status
- Early direct deposit
- No branches
- Higher savings tiers need direct deposit thresholds
- Smaller product range than SoFi
Revolut suits travelers and people who hold or spend in more than one currency. The app supports multiple currency balances, card spending abroad, budgeting tools, and savings vaults, with premium tiers adding higher limits and travel benefits. In the US, accounts operate through a partner bank with FDIC insurance through that partner.
The US product lacks some features available in Europe, and free-plan currency exchange has monthly limits and weekend conditions. Paid plans raise those limits but add a monthly cost. For international spending as a second account, Revolut is hard to match.
- Multi-currency accounts
- Competitive exchange within limits
- Budgeting and vaults
- US product is less full than European product
- Premium tiers cost extra
- Exchange limits apply on free plan
Current is built for younger users and families, with teen accounts that parents can oversee, allowances, and spending controls. Basic accounts charge no monthly fee, direct deposit can arrive early, and debit spending can earn points on eligible purchases. Savings pods help separate money for goals.
Premium features and higher benefits cost extra, and there are no branches for cash or in-person help. Accounts operate through partner banks with FDIC insurance through those partners. For a family banking setup, Current offers controls that general fintech apps lack.
- No monthly fee on basic accounts
- Teen accounts with parental controls
- Points on debit spending
- No branches
- Premium features cost extra
- Savings pods need setup
Cash App started as a peer payment app and now offers a Cash Card, direct deposit, and savings features through partner banks. Sending money to friends is fast, and the card works for everyday spending with optional discounts on selected merchants. That simplicity makes it a good second account or first account for younger users.
Banking depth is lighter than dedicated banking apps: budgeting, joint accounts, and branch-like services are limited. Investing features exist in the same app but carry market risk and need separate consideration. For payments first and banking second, Cash App fits well.
- Easy peer payments
- Cash Card debit
- Direct deposit and savings options
- Banking features are lighter than Chime or SoFi
- Investing is separate and carries risk
Wise is best known for international transfers with transparent fees and mid-market exchange rates. Users can hold balances in several currencies, receive money with local account details in supported regions, and spend abroad with a debit card. That makes it a strong companion account for freelancers, travelers, and people sending money across borders.
Wise is not a full replacement for a US checking account for most people: direct deposit, bill pay, and domestic banking depth vary by country. Some card and transfer fees apply depending on currency and method. For cross-border money, Wise is the clearest specialist here.
- Transparent transfer fees
- Multi-currency balances
- Debit card for travel spending
- Not a full US checking replacement
- Some features vary by country
- Card fees may apply
MoneyLion combines checking and savings with cashback, investing, and credit building tools in one app. Basic banking carries no monthly fee, and rewards on eligible spending add value for everyday users. Credit building features help people establish or improve credit history, subject to terms and eligibility.
Some benefits need membership, direct deposit, or other conditions, and the app packs many products into one feed, which can feel busy. For users who want banking and credit tools together, MoneyLion offers a broader bundle than Chime or Varo.
- No monthly fee on basic banking
- Cashback and rewards
- Credit building features
- Some features need membership or conditions
- Product range can feel busy
Dave offers banking plus ExtraCash advances, which help cover small gaps before payday without interest charges. The basic tier carries no monthly fee, while a paid membership adds fuller features. Direct deposit can arrive early, and budgeting tools help track spending between paydays.
Advance limits depend on account history and direct deposit, and they start modestly for new users. Advances should not replace an emergency fund or steady budgeting, since repeated advances can mask a larger cash flow problem. For occasional short gaps, Dave is a practical safety net.
- Cash advances without interest
- No monthly fee on basic tier
- Early pay options
- Advance limits start small
- Full features need a paid membership
- Advances are not a long-term fix
How we picked these
We compared official fee schedules, account features, FDIC arrangements, and app tools for fintech banking apps available to US users in October 2026. We kept only apps that still operate and offer real checking or banking accounts, and we avoided quoting savings rates as guarantees, since rates and eligibility change. Where a rate appeared in search results, we described it in general terms and pointed readers to current terms.
How to choose a fintech banking app
Start with how you actually use money. If most spending is domestic and fee-free banking matters most, Chime, Varo, or SoFi cover the basics well. If travel or cross-border payments matter, add Revolut or Wise as a companion account. If family controls or teen accounts matter, Current leads.
Check three details before opening any account: FDIC insurance arrangement, fee schedule for out-of-network ATMs and overdrafts, and direct deposit conditions for early pay and savings benefits. Also test cash handling: if you deposit cash often, a fintech app without branches may frustrate you. Keep a traditional bank or credit union as a backup if cash deposits, cashier checks, or in-person help matter to you.
Frequently asked questions
What is the best fintech app for personal banking overall?
Chime is our pick for most everyday US banking because it charges no monthly fee and covers early pay and fee-free ATMs. SoFi wins for all-in-one banking plus investing, Varo wins for a chartered digital bank, and Revolut wins for travel. Match the app to your main banking job.
What is the best fintech software for personal banking with no monthly fee?
Chime, SoFi, Varo, Current, and Revolut Standard all offer no-monthly-fee basic accounts, though other fees can still apply. Check out-of-network ATM fees, overdraft terms, and conditions for savings benefits, since a no-monthly-fee label does not mean every service is free.
Is fintech banking safe?
Reputable fintech apps hold customer funds through partner banks with FDIC insurance up to the legal limit, or, in Varo case, as a chartered bank itself. Confirm the FDIC arrangement on the provider site before depositing large sums, use strong passwords and two-factor authentication, and keep records of transfers.
Can a fintech app replace a traditional bank?
For many people, yes, for everyday checking, savings, and card spending. Fintech apps lack branches, so cash deposits, in-person help, and some certified services can be harder. Many users keep a traditional account alongside a fintech app for those needs.
Do fintech banking apps pay interest on savings?
Many do, but rates, tiers, and eligibility conditions change often and depend on direct deposit or membership status. This article does not quote a guaranteed rate, since a rate seen in one month may differ the next. Check the current savings terms on the provider site before opening an account for interest alone.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 zoho inventory alternatives
6 Alternatives to Zoho Inventory, Compared on Price and Fit
Zoho Inventory alternatives: 6 tools compared on price, free plans and fit. Katana leads the list for manufacturers. Fit and flaws are laid out for each entry.
Read → zoho crm alternatives
Best Zoho CRM Alternatives (2026)
Need Zoho CRM alternatives? We compare 7 tools on cost, free access and who each suits. Every pick gets a straight assessment. Built for quick decisions.
Read → zelle alternatives
Best Zelle Alternatives in 2026
Compare the best Zelle alternatives for sending money to friends, paying sellers and moving funds abroad, with honest notes on fees, speed and safety in 2026.
Read →