 ProMapRanker
Best Fiduciary Financial Advisor Companies in 2026

Key takeaways
- A fiduciary is legally required to act in a client best interest, which is a stronger standard than simply selling a suitable product.
- Always ask for fiduciary status in writing, and check whether it applies to all advice or only to certain accounts or services.
- Fees matter over time, so compare flat fees, percentage-of-assets fees, and hourly fees on the same service level.
- Verify registration and disciplinary history through official sources before hiring any adviser, and do not rely on a website claim alone.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 Facet | Flat-fee planning | See website | No | Visit |
 Vanguard Personal Advisor | Low-cost advised portfolios | See website | No | Visit |
 Charles Schwab Wealth Advisory | Branch and phone advice | See website | No | Visit |
 Fidelity Wealth Management | Broad planning and investing | See website | No | Visit |
 Fisher Investments | Larger portfolios | See website | No | Visit |
 Edelman Financial Engines | Workplace and retail planning | See website | No | Visit |
 Creative Planning | Comprehensive wealth planning | See website | No | Visit |
 Edward Jones | Local branch relationships | See website | No | Visit |
 Garrett Planning Network | Hourly and project advice | See website | No | Visit |
The best fiduciary financial advisor companies
We compared advisory firms that describe themselves as fiduciaries or operate as registered investment advisers, with attention to fee structure, minimums, planning depth, and service style. A fiduciary, in plain terms, is an adviser who must put client interests ahead of their own, disclose conflicts, and act with care when giving advice. That duty can apply to investment advice, retirement advice, or broader financial planning, depending on the firm and the account, so readers should confirm the scope in writing.
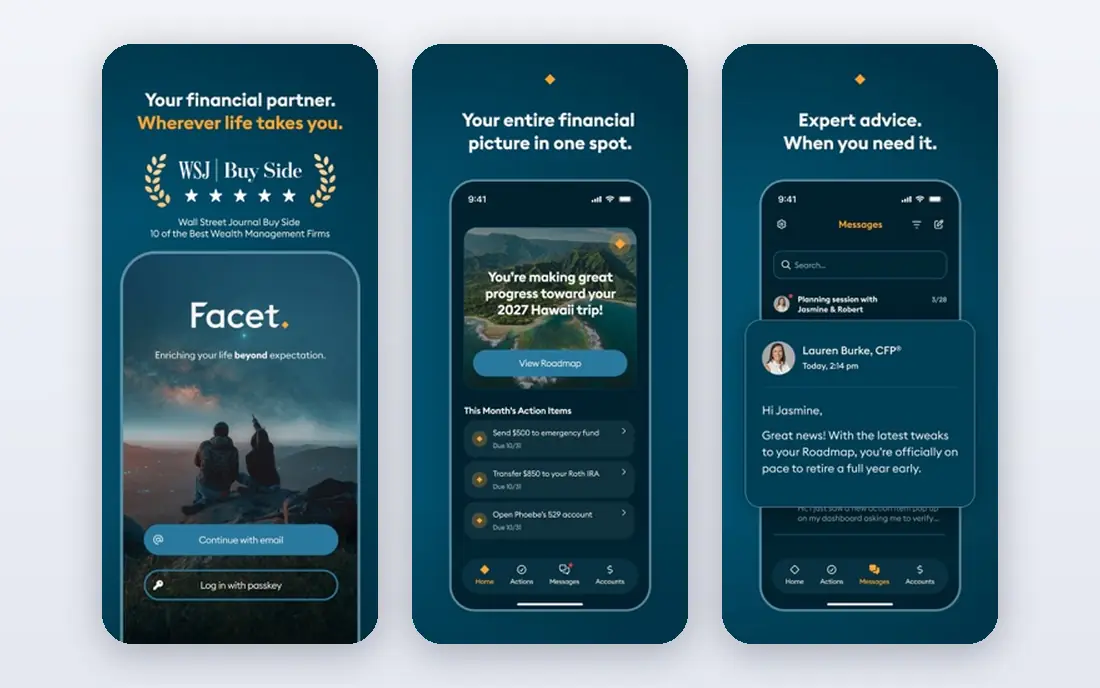
Facet is often the first name to check for households that want comprehensive planning without a percentage-of-assets fee that grows with the portfolio. Its membership model charges a flat annual fee based on plan complexity, and includes planning from a certified financial planner, along with investment management in many plans. Topics covered can include cash flow, debt, retirement, tax-aware investing, company stock plans, and education savings, which suits households whose questions go beyond picking funds.
The trade-off is service style. Facet is virtual-first, with meetings by video and messaging, so buyers who want a local office and face-to-face meetings may prefer a branch firm. Fees also vary by plan, so the lowest plan may not include the same meeting frequency or dedicated planner access as a higher plan. For readers who value a clear flat fee, a named planner, and broad planning, Facet is a strong starting point, provided they confirm fiduciary status and fee scope in writing.
- Flat-fee membership model
- Dedicated certified financial planner in higher plans
- Broad planning topics
- Virtual-first service may not suit in-person buyers
- Fee varies by plan complexity
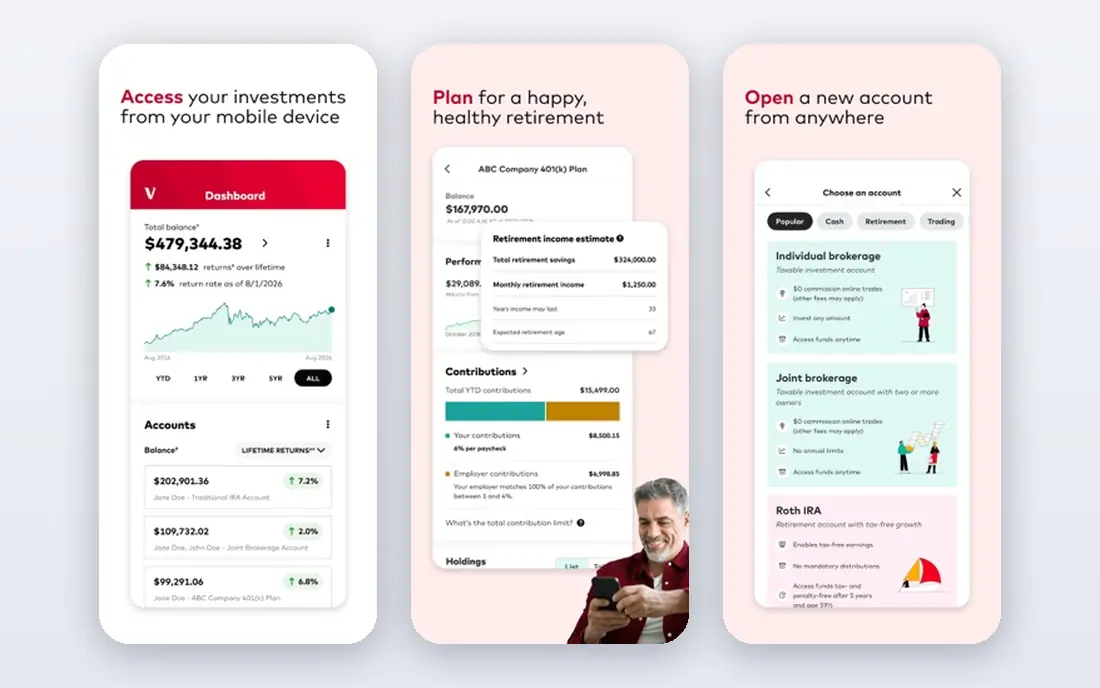
Vanguard Personal Advisor combines low-cost investing with access to financial planners, and it is often chosen by long-term investors who want advice without a high advisory fee. The service builds a diversified portfolio based on goals and risk tolerance, rebalances over time, and gives clients access to planners for retirement, tax, and estate questions within the service scope. That blend of low cost and planning depth is hard to match at larger asset levels.
The main limit is personal touch. Advice is delivered mainly by phone and online, rather than through a local branch office, and the level of planner access can depend on assets and service tier. Vanguard also focuses on diversified, long-term portfolios, so investors who want active stock picking or complex private investments may need a different firm. For retirement savers who want fiduciary advice at a low cost, Vanguard Personal Advisor remains a benchmark to compare against.
- Low advisory cost relative to many firms
- Access to certified planners in advised services
- Diversified portfolios
- Service is mainly phone and digital
- Higher-touch service may need higher assets
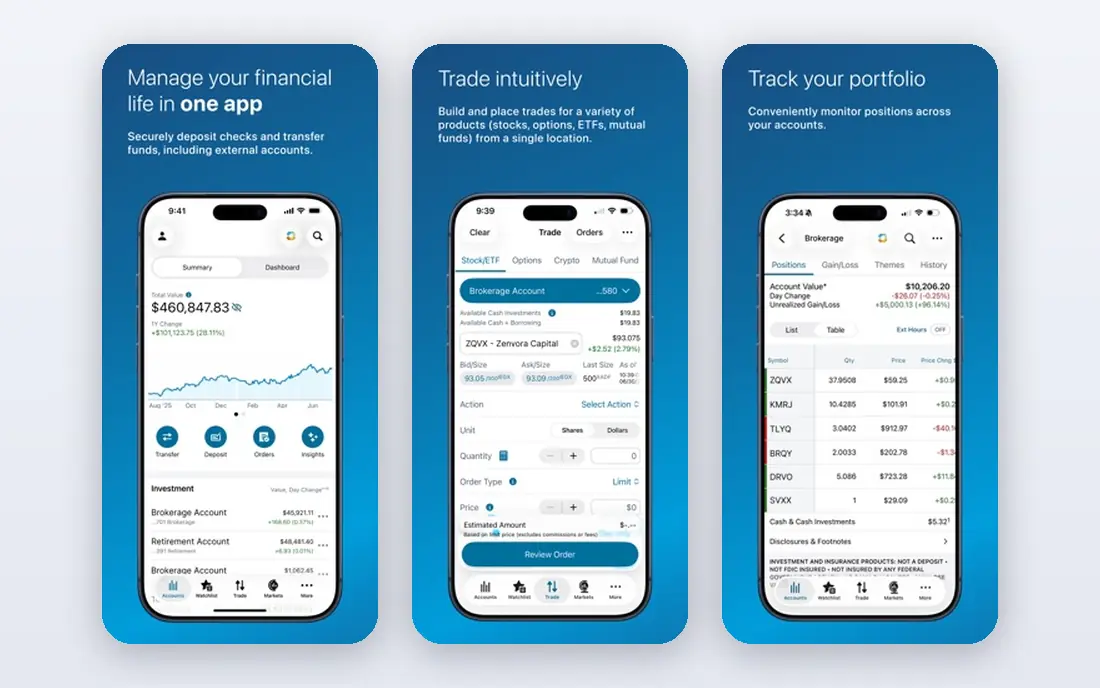
Charles Schwab Wealth Advisory suits investors who want fiduciary advice with the option of a branch visit as well as phone and online support. Schwab offers a range of advisory services, from managed portfolios to more comprehensive wealth advisory for larger clients, with planning for retirement, tax, estate, and charitable giving depending on the service. Its banking and brokerage integration also helps clients who want investments, cash management, and planning in one firm.
Fees and minimums vary by service, so readers should ask which Schwab advisory service they are being offered, what it costs, and whether the adviser is acting as a fiduciary for that service. A managed portfolio service and a full wealth advisory service are not the same, even when both sit under the Schwab name. For investors who value in-person access and a large, established firm, Schwab is a practical comparison, especially at higher asset levels.
- Branch network plus phone advice
- Wealth planning services
- Broad account and banking integration
- Minimums apply to some advisory services
- Fee structure varies by service
Fidelity Wealth Management covers a wide range, from planning help for retirement savers to dedicated wealth management for larger clients. Its advisers can help with portfolio construction, retirement income, tax-aware investing, and estate planning topics, depending on the service tier, and clients can combine managed accounts with self-directed accounts where that fits. The Fidelity branch network and online tools also give clients more than one way to reach an adviser.
As with Schwab, the key is to identify the exact programme. Fidelity offers free planning tools, lower-cost managed portfolios, and higher-touch wealth services, and fiduciary scope and fees differ between them. Readers should ask for the programme name, fee, minimum, and fiduciary statement in writing before enrolling. For households that already use Fidelity for brokerage or retirement accounts, Fidelity Wealth Management is a natural first advice quote.
- Large adviser and branch network
- Broad planning tools
- Managed and self-directed options
- Service and fees vary by programme
- Minimums apply to some wealth services
Fisher Investments is an established investment management firm that serves many clients with larger portfolios, often starting around a high minimum. Its approach is active and research-driven, with portfolios built around market outlook and client goals, and clients receive ongoing service from a dedicated contact team. For investors who want a firm to manage investments actively and who meet the minimum, Fisher offers a long track record and a clear service model.
The cost and minimum are the main barriers. A percentage-of-assets fee, even at around one percent, adds up over years, and investors should compare it with flat-fee and low-cost advisory alternatives on the same portfolio size. Active management also does not guarantee better returns than a diversified index portfolio, and readers should ask how performance, fees, and taxes are reported. Fisher is best for larger investors who consciously choose active management and understand its cost.
- Established investment management firm
- Dedicated client service
- Active portfolio management approach
- Higher minimums in many cases
- Percentage fee can be costly on large portfolios
Edelman Financial Engines is one of the largest independent planning firms in the United States, and many readers first meet it through a workplace retirement plan. It offers retirement planning, managed accounts, and broader financial planning for retail clients, with planners who can help with savings rates, investment allocation, Social Security timing, and retirement income. That workplace link can be valuable, because advice is tied to the actual retirement account the employee holds.
Service depth depends on whether the client comes through an employer plan, a retail managed account, or a fuller planning service, so fees and planner access vary. Readers should ask which Edelman service they are in, what it costs, and what planning topics are included. For employees whose workplace plan includes Edelman advice, it is worth using that benefit first, then comparing retail planning options if more comprehensive advice is needed.
- Large planning firm
- Workplace retirement advice
- Retail planning and managed accounts
- Service depth varies by employer plan or retail tier
- Fees vary by service
Creative Planning is a large independent wealth management firm known for comprehensive planning that brings together investments, tax planning, estate planning, and business owner advice where relevant. Its teams include specialists beyond a single adviser, which can help households with complex situations, such as business ownership, stock compensation, or multi-generational planning. That breadth is the main reason to consider it over a simpler robo-advisor or single-planner firm.
The barriers are minimums and cost. Creative Planning typically serves clients with larger portfolios, and its percentage-based fee should be compared with flat-fee planning on the same asset level. Readers should also confirm fiduciary status for the specific service and ask how tax and estate specialists are included or billed. For complex, higher-asset households that want one firm to coordinate many topics, Creative Planning is a strong contender.
- Comprehensive planning across tax, estate, and investments
- Large independent firm
- Specialist teams
- Minimums apply in many cases
- Fee is percentage-based in many services
Edward Jones suits investors who want a local adviser in their community and a long-term relationship built around regular meetings. Its branch model places advisers in many towns and cities, and its planning focus covers retirement, education savings, and estate topics that matter to families and small business owners. For readers who prefer to discuss money face to face, rather than by video or phone only, that local presence is a real benefit.
Fees, account types, and fiduciary scope vary by programme, so readers should ask whether a given account is advisory or brokerage, what the fee is, and whether the adviser acts as a fiduciary for that account. Product recommendations and service quality can also vary by individual adviser, so meeting the actual adviser, not just the brand, matters. For relationship-driven investors, Edward Jones is worth a local meeting, alongside a flat-fee or low-cost comparison.
- Very large branch network
- Local adviser relationships
- Retirement and education planning focus
- Fees and product range vary by programme
- Branch experience varies by adviser
Garrett Planning Network is different from the other firms here, because it is a network of independent advisers who offer hourly or project-based planning, rather than a single firm with one fee schedule. That model suits readers who need advice on a specific question, such as retirement timing, a job change, or a tax decision, without handing over a portfolio for ongoing management or paying a yearly percentage fee. Many Garrett advisers have no asset minimum, which opens advice to younger savers and middle-income households.
Because it is a network, experience and quality vary by individual adviser, so verification matters even more. Readers should check each adviser registration, credentials, disciplinary history, fee, and fiduciary statement, and ask for a written scope for the project. Ongoing portfolio management, if needed, may require a separate agreement. For one-time or occasional advice, Garrett is often the most flexible and affordable route to a fiduciary planner.
- Hourly and project-based advice
- No asset minimum in many cases
- Nationwide adviser directory
- It is a network, so adviser quality varies
- Ongoing management may need a separate arrangement
How we picked these
We compared official firm pages, fee descriptions, service tiers, minimums, and fiduciary statements, along with public guides on adviser types. We did not claim hands-on testing, and we did not rank firms by returns, because advice quality cannot be judged from past portfolio performance alone. We favoured firms with a current United States advisory service, a clear fee model, and a route for ordinary readers to verify registration and fiduciary status before hiring.
How to verify a fiduciary adviser before you hire one
Start by asking three questions in writing: Are you acting as a fiduciary for all advice you give me, what are all the fees I will pay, and how are you compensated beyond those fees. A clear fiduciary will answer directly, disclose conflicts such as commissions or product incentives, and put the fee and scope in an agreement. If an adviser avoids the fiduciary question, describes a product as suitable without explaining alternatives, or cannot state total cost, treat that as a reason to keep looking.
Next, verify independently. Check the adviser and firm on the SEC Investment Adviser Public Disclosure site, known as AdviserInfo, and on FINRA BrokerCheck where the person also holds a brokerage licence. Look for registration status, credentials such as CFP, employment history, and any disciplinary disclosures. Credentials alone do not prove quality, but a missing registration, a revoked credential, or a pattern of disclosures should prompt hard questions. Keep copies of the agreement, fee schedule, and fiduciary statement, and review them each year as your situation changes.
Finally, match the fee model to your need. A flat fee suits planning-heavy households, a percentage fee suits investors who want ongoing management and can compare the yearly cost, and an hourly fee suits a single project or second opinion. Ask how often you will meet, who your day-to-day contact will be, and how investment changes are communicated. The best adviser is not the largest firm or the lowest fee in isolation, but the firm whose fee, service, and fiduciary scope fit your goals and whose answers survive an independent check.
Frequently asked questions
What does fiduciary mean in plain terms?
Fiduciary means the adviser is legally required to act in your best interest, disclose material conflicts, and act with care when giving advice. It is stronger than a suitability standard, under which a product only needs to be suitable, even if a cheaper or better option exists. Always confirm fiduciary status in writing and check whether it covers all advice or only certain accounts.
How do I check if an adviser is really a fiduciary?
Ask for a written fiduciary statement for the specific service, then verify registration on SEC AdviserInfo and, where relevant, FINRA BrokerCheck. Check credentials, employment history, and disciplinary disclosures. A website claim alone is not verification, and an adviser who acts as a fiduciary for one account may act under a different standard for another account.
What is the difference between a flat fee and a percentage fee?
A flat fee is a set annual or project amount that does not rise with portfolio size, which can be cheaper for larger portfolios. A percentage fee is a share of assets under management, usually charged yearly, which rises as the portfolio grows. An hourly fee charges for time spent on a specific project. Compare total yearly cost on the same service level, not just the fee label.
Do fiduciary advisers charge less than other advisers?
Not always. Fiduciary status describes a duty of loyalty and care, not a price level. Some fiduciary firms charge high percentage fees, while some non-fiduciary services charge low fees. Compare fee, service depth, and conflicts together, and ask for total cost including fund fees and any product charges.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 zscaler alternatives
Best Zscaler Alternatives in 2026
Looking for zscaler alternatives? We compare 9 SASE and zero trust platforms on architecture, data protection, pricing, and fit for your network and team.
Read → zapier alternatives free
Best Zapier Alternatives Free in 2026
Nine automation tools for zapier alternatives free in 2026, all with genuinely free tiers, plus free plan limits, starting prices and upgrade paths explained.
Read → which platform is best for online reputation
Which Platform Is Best for Online Reputation in 2026
Wondering which platform is best for online reputation? We compare 8 review, listing, and response tools for small and multi-location businesses and agencies.
Read →