 ProMapRanker
Best Earned Wage Access Apps in 2026

Key takeaways
- EarnIn is the lowest-cost consumer option for many workers, with no mandatory fee and standard transfers at no cost, though instant delivery costs extra.
- Brigit and Dave charge monthly fees, so they cost more for occasional use, even when an individual advance looks cheap.
- DailyPay and Payactiv work through employers, so availability depends on your workplace, not just on downloading an app.
- Fees, tips, and instant-delivery charges add up fast, and a small advance taken often can cost more than it first appears.
- Earned wage access is not a loan in the usual sense where it advances pay already earned, but terms vary by provider and state, so read the fee schedule first.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 EarnIn | Lowest mandatory cost for earned pay | Free | Yes | Visit |
 Dave | Banking bundle with ExtraCash advances | See website | No | Visit |
 Brigit | Credit building plus advances | $8.99 per month | No | Visit |
 MoneyLion Instacash | Advances inside a wider banking app | Free | Yes | Visit |
 DailyPay | Employer-based early pay | Free | No | Visit |
 Payactiv | Employer pay access plus benefits | See website | No | Visit |
 Branch | Employer and gig worker pay options | See website | No | Visit |
 Gerald | No-fee advances with a purchase step | Free | Yes | Visit |
The best earned wage access apps
We compared consumer apps and employer-based platforms on mandatory fees, advance limits, delivery speed, and eligibility. Our pick for most workers who can choose freely is EarnIn for cost, while workers whose employer offers DailyPay or Payactiv should check that route first, since employer terms can be simpler.
EarnIn lets eligible workers access pay they have already earned before payday, with standard transfers at no mandatory cost and repayment taken automatically from the next paycheck. Current 2026 comparisons list limits up to $150 per day and up to $1,000 per pay period, with higher limits for some users on Live Pay. That combination of no subscription and a high cap is why it leads this list for cost.
The catch is speed and habit. Instant Lightning Speed transfers carry a fee, listed in recent comparisons from $3.99 to $8.99 depending on amount and bank, and optional tips can add cost if you leave them on. Standard transfers take one to three business days, so plan ahead if you can. EarnIn also needs a consistent direct deposit schedule and is not available in every state, so check eligibility before relying on it.
- No mandatory fee for standard transfers
- High per-pay-period limit for eligible users
- No credit check for Cash Out
- Instant delivery fees vary and can add up
- Requires consistent direct deposit and employment verification
Dave offers ExtraCash advances through its app, alongside a Dave banking account and budgeting tools. Recent comparisons list ExtraCash up to $500, with a monthly membership for new members and a per-advance fee of $5 or 5 percent, whichever is greater, plus an optional express fee for fast delivery to an external debit card. That bundle suits someone who wants banking and advances in one app.
The cost structure is the weakness. A membership plus a per-advance fee means a single small advance can cost more than the same advance on EarnIn, especially if you also pay for express delivery. Dave also relies on bank account history rather than employer timesheets, which helps gig and irregular workers. Check the current membership price on the vendor site, since recent listings differ between new and legacy members.
- ExtraCash advances up to $500 in current listings
- Dave banking account available
- No late fees on advances
- Monthly membership plus a per-advance fee
- Express delivery costs extra to an external card
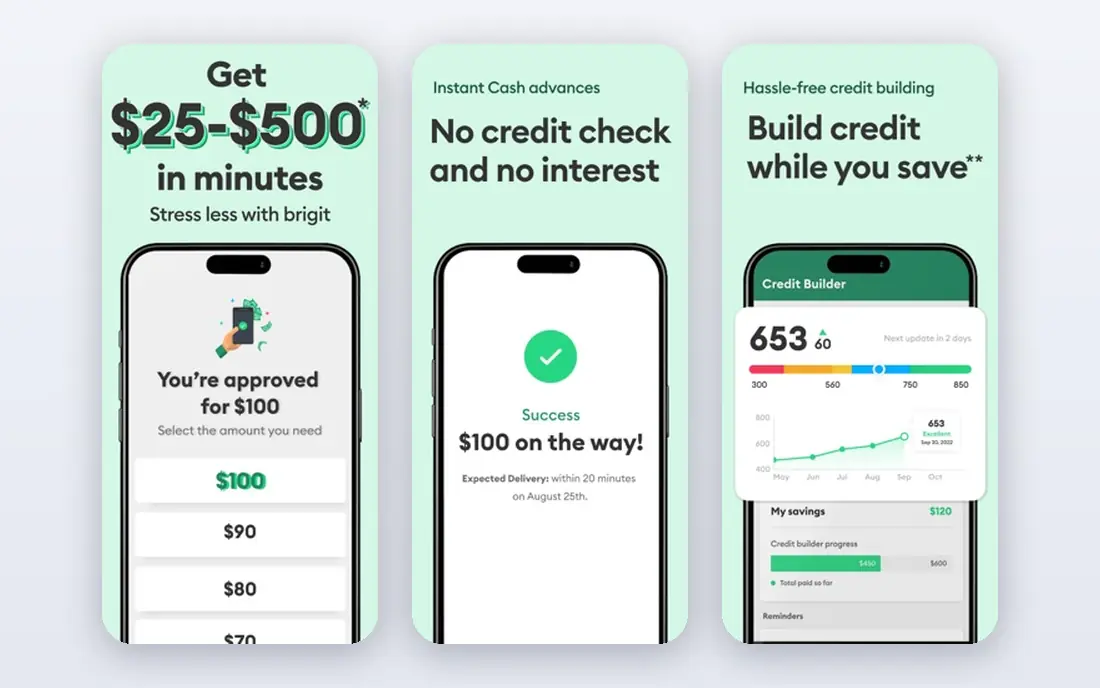
Brigit requires a paid plan for cash advances, with Plus listed at $8.99 per month and Premium at $15.99 per month in current comparisons. Advances are listed up to $500, though most users qualify for less at first. Premium adds a Credit Builder that reports to all three bureaus, which is the main reason to pick Brigit over a cheaper advance app.
The trade is clear: if you advance money once a month, the subscription alone is your cost before any express fee. Brigit makes more sense for someone who will use the budgeting, overdraft prediction, and credit building tools every month, not just for a one-off advance. If you only need occasional early pay, a no-subscription app will usually cost less.
- Predictable monthly plans
- Credit Builder on Premium reports to bureaus
- Overdraft prediction tools
- Paid plan required for advances
- Monthly cost adds up for occasional use
- Many users qualify for less than the headline limit
MoneyLion Instacash is an earned wage access product that lets eligible users access a portion of earned pay before payday. Current listings put Instacash up to $500, or up to $1,000 with qualifying recurring direct deposits to a MoneyLion account. There are no mandatory fees, and standard delivery takes one to five business days, with minutes available for an optional Turbo Fee.
The appeal is the wider app: banking, investing, and credit building tools sit alongside Instacash, so a user who already banks with MoneyLion gets advances without a separate subscription. The limit is that instant delivery costs extra and the amount you qualify for depends on direct deposit history. Check the Turbo Fee for your amount before choosing instant delivery.
- No mandatory fees for Instacash
- Higher limit with qualifying direct deposits
- No credit check for advances
- Instant Turbo Fee varies
- Full feature set sits behind higher tiers for some users
DailyPay works through employers, letting workers transfer earned pay before payday once their employer has signed up. That employer link is both the strength and the limit: setup is tied to payroll, so the amount available reflects hours already worked, and repayment is handled through payroll rather than a separate debit. For workers at a participating employer, it can be the simplest route, with no separate app subscription to manage.
The catch is availability and fees. If your employer does not offer DailyPay, you cannot use it on your own, and transfer fees vary by employer plan and by whether you choose instant or next-day delivery. Ask your employer or check the DailyPay site for the fee schedule that applies to your workplace before your first transfer.
- Access earned pay through your employer
- Clear employer-side setup
- No credit check for most users
- Only available if your employer offers it
- Transfer fees depend on employer plan and speed
Payactiv is another employer-based platform, offering earned wage access alongside savings, bill payment, and financial wellness tools for workers at participating employers. Because it connects to payroll, the amount you can access is based on earned wages, and the employer plan shapes fees and delivery options. That structure suits workers who want early pay plus other workplace benefits in one place.
The limit is the same as DailyPay: no employer offer means no access, and terms differ by workplace. Payactiv also serves employers directly, so consumer pricing is not a single public number. Check with your employer for the exact fee schedule, transfer options, and any caps that apply to your role.
- Employer-based earned wage access
- Wider benefits such as savings and bill tools
- Payroll-linked repayment
- Employer availability required
- Pricing and fees depend on the employer plan
Branch provides pay access tools for employers, gig platforms, and workforces that need flexible pay timing. Eligible workers can access earned pay early, and Branch also offers a card and account tools for managing that pay. That mix helps workers whose income comes from shifts, gigs, or multiple employers, where a single consumer app may not fit the pay pattern.
The downside is variation. Fees, limits, and delivery speed depend on the employer or platform partner, so two Branch users can face different terms. Read the terms for your specific employer or platform, and compare the total cost of an instant transfer with waiting for standard payroll timing where that is possible.
- Works with employers and gig platforms
- Instant pay options for eligible workers
- Card and account tools available
- Availability depends on employer or platform
- Fees and limits vary by partner
Gerald takes a different route: it offers advances up to $200 with no subscription, interest, transfer fees, or late fees in its stated model, but you first use its buy-now-pay-later store, which then allows an advance to be transferred to your bank. That purchase step is the key detail, and it means Gerald is not a straight advance app for everyone. For a user who already shops through Gerald, the no-fee story is attractive.
The limits are the lower cap and the purchase requirement. At up to $200, Gerald covers a small gap, not a large bill, and users who do not want to shop through its store will find the step awkward. Still, for small, occasional needs, the absence of fees makes it worth knowing about, provided you understand the purchase step before you sign up.
- No subscription, interest, transfer fee, or late fee in its stated model
- Advances up to $200 in current listings
- Simple fee story
- Advance requires a buy-now-pay-later purchase first
- Limit is lower than EarnIn or Dave
- Newer and smaller than the leaders
How we picked these
We compared earned wage access apps and employer platforms using vendor fee pages and current 2026 comparisons that cite vendor fees and limits. We favoured products with clear fee schedules, no mandatory interest, and a real path to early pay, whether through a consumer app or an employer. We used See website where recent listings conflicted on a price, rather than publishing a disputed figure as fact. We did not claim hands-on testing; this is a comparison of published fees, limits, and eligibility.
What to check before you use early pay
Start with the total cost of one advance, not just the headline fee. Add the monthly membership, the per-advance fee, any tip you leave, and any instant-delivery fee, then divide by the amount advanced. A $5 fee on a $100 advance taken often is a high cost for short-term cash, even if the fee looks small on its own. If you can wait one to three business days for a standard transfer, you often remove the largest extra charge.
Employer route first, consumer route second
If your employer offers DailyPay, Payactiv, Branch, or another earned wage access benefit, check that route before downloading a consumer app. Employer terms are often simpler, repayment runs through payroll, and you avoid a separate subscription. If no employer route exists, compare consumer apps on mandatory cost first, then on limit and speed.
Avoid the advance cycle
Early pay works best as an occasional bridge for a timing gap, such as a bill due days before payday. If you need an advance every pay period to cover regular costs, the pattern is a sign to review the budget, check for cheaper help, or talk to a nonprofit credit counsellor. Automatic payday repayment can also trigger an overdraft if the account balance is low, so check the repayment date and balance before you advance.
Terms, states, and eligibility
Availability, limits, and fees vary by state and by employment type. Some apps need a consistent direct deposit schedule, some need employer verification, and some work from bank history alone. Check state availability, the repayment method, and what happens if a paycheck is delayed. This is general information only, not financial advice, and fees and terms vary by provider.
Frequently asked questions
What is the best earned wage access app with no monthly fee?
EarnIn is the strongest no-mandatory-fee option in current comparisons, with standard transfers at no cost and no subscription required. Gerald also states no fees, but its advance requires a prior buy-now-pay-later purchase and caps at a lower amount. MoneyLion Instacash also has no mandatory fees, though instant delivery costs extra.
Is earned wage access a loan?
Not in the usual sense where it applies. Most earned wage access products advance pay you have already earned, with repayment from your next paycheck, and they do not charge interest in the way a loan does. Some products still carry fees, tips, or instant-delivery charges, and regulators treat different models differently, so read the terms for the specific product you use.
How fast do earned wage access apps pay out?
Standard transfers usually take one to three business days, and some take up to five days. Instant transfers can arrive in minutes, but they almost always cost extra. If timing is tight, check the exact instant fee for your amount before you confirm, since it varies by app and bank.
Do I need my employer to use earned wage access?
It depends on the product. EarnIn, Dave, Brigit, MoneyLion, and Gerald are consumer apps you can use without an employer signup, subject to bank and direct deposit checks. DailyPay, Payactiv, and Branch in their employer form require your employer or platform to offer them, so availability is set by your workplace.
What is the best earned wage access software for employers?
DailyPay and Payactiv are the most widely cited employer platforms, with Branch also strong for employers and gig platforms. The best choice for an employer depends on payroll setup, workforce size, fee model, and whether the team wants wider benefits such as savings tools alongside early pay. Get a written fee schedule for your workforce before signing.
Sources
- https://www.earnin.com
- https://www.dave.com
- https://www.hellobrigit.com
- https://www.moneylion.com
- https://www.dailypay.com
- https://www.payactiv.com
- https://www.branchapp.com
- https://www.joingerald.com
- https://walletgrower.com/earned-wage-access/earnin-vs-dave-vs-brigit-2026-cheapest-by-paycheck-size
- https://www.moneylion.com/learn/personal-loans/reviews/earnin
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 zoho inventory alternatives
6 Alternatives to Zoho Inventory, Compared on Price and Fit
Zoho Inventory alternatives: 6 tools compared on price, free plans and fit. Katana leads the list for manufacturers. Fit and flaws are laid out for each entry.
Read → zoho crm alternatives
Best Zoho CRM Alternatives (2026)
Need Zoho CRM alternatives? We compare 7 tools on cost, free access and who each suits. Every pick gets a straight assessment. Built for quick decisions.
Read → zelle alternatives
Best Zelle Alternatives in 2026
Compare the best Zelle alternatives for sending money to friends, paying sellers and moving funds abroad, with honest notes on fees, speed and safety in 2026.
Read →