 ProMapRanker
Best Debt Payoff App in 2026: 9 Apps Compared

Key takeaways
- Undebt.it is the best free planner for comparing snowball, avalanche, and custom payoff strategies side by side.
- Debt Payoff Planner is the best mobile-first pick, with visual progress and a simple monthly payment slider.
- YNAB suits people who want debt payoff inside a full budget, rather than a standalone calculator.
- Unbury.me is the fastest free check for a single payoff timeline, with no account needed.
- This guide is not financial advice, and anyone facing hardship should consider a nonprofit credit counselor alongside an app.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 Undebt.it | Comparing payoff strategies | Free | Yes | Visit |
 Debt Payoff Planner | Mobile snowball and avalanche plans | Free | Yes | Visit |
 YNAB | Debt inside a full budget | $14.99 per month | Free trial | Visit |
 Unbury.me | Simple free payoff check | Free | Yes | Visit |
 Goodbudget | Envelope budgeting with debt tracking | Free | Yes | Visit |
 Changed | Rounding up spare change to debt | See website | Yes | Visit |
 Bright | Automated payoff and credit building | See website | Yes | Visit |
 Empower | Net worth and liability tracking | Free | Yes | Visit |
 NFCC | Nonprofit credit counseling | See website | Yes | Visit |
The best debt payoff apps
These apps and services help a person list debts, choose a payoff order, and see a debt-free date. Some only plan, while others link to accounts or automate payments, so the right pick depends on how much automation you want. This is not financial advice, and the figures any app shows depend on the balances, rates, and payments you enter, so check them against your statements.
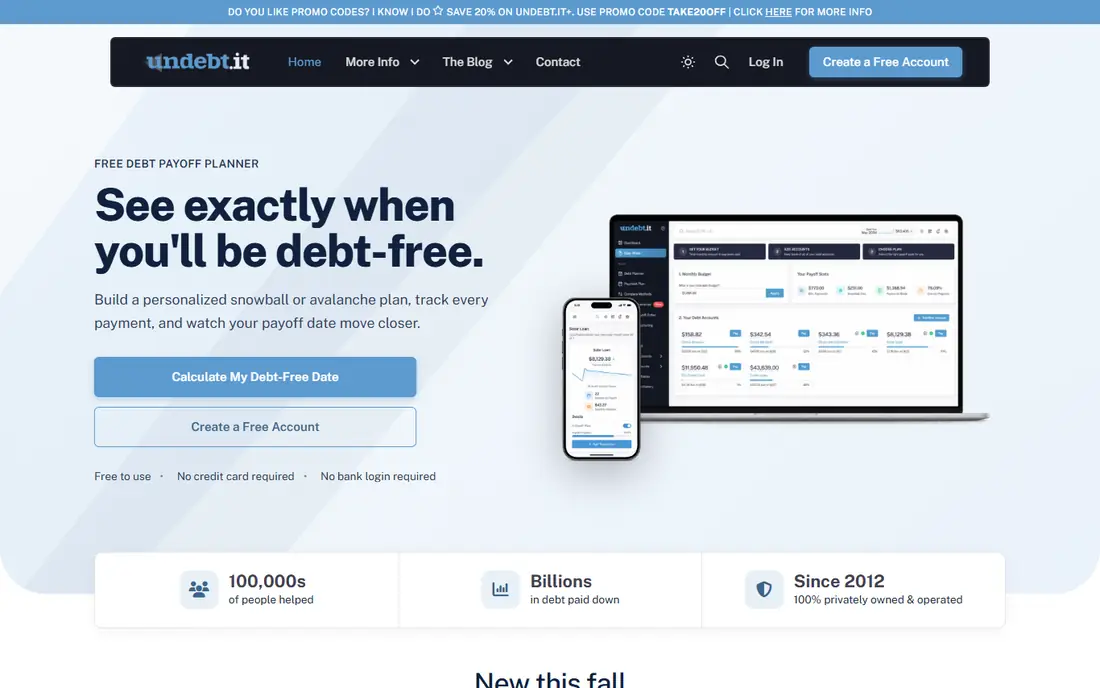
Undebt.it is the planner we would point most people to first. You enter each debt with its balance, interest rate, and minimum payment, pick a strategy, and get a month-by-month plan with a projected debt-free date. The side-by-side comparison is the standout feature, because it shows how much interest each method saves before you commit to one.
Manual entry is the trade-off. Free users type in every balance and update payments by hand, which takes discipline when several accounts are involved. Premium, at $12 per year, adds balance tracking graphs, payment tracking, and custom due dates, and a YNAB integration is available on premium. For a careful planner, the free version is already enough to make a good decision.
- Supports snowball, avalanche, and custom plans
- Side-by-side strategy comparison
- Unlimited debts on the free version
- Web only with no dedicated mobile app
- Manual entry on the free version
- Premium is needed for some tracking features
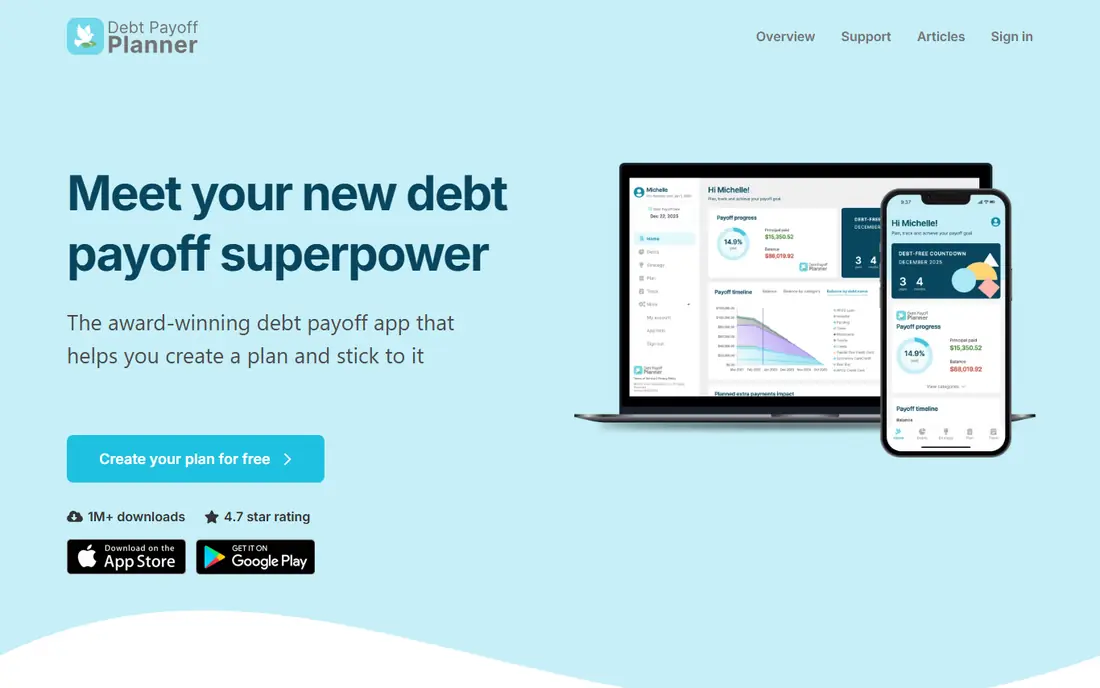
Debt Payoff Planner is the mobile-first alternative to Undebt.it. It covers snowball, avalanche, and custom plans, with charts that make progress easy to see and a slider that shows how an extra monthly payment moves the debt-free date. That visual feedback helps when motivation dips, because a small extra payment becomes a concrete date change.
The free version handles the core job well, while the Pro plan, at $1.99 per month, removes ads and adds automated bank sync and advanced reports. If you want a payoff plan on your phone and you will actually open it each month, this is the pick.
- Native iOS and Android apps
- Visual progress charts
- Slider shows how extra payments change the debt-free date
- Bank sync needs a paid plan
- Free version has ads and fewer reports
- Manual entry on the free tier
YNAB, short for You Need A Budget, treats debt payoff as part of a budget, not as a separate calculator. Every dollar gets a job, including debt payments, and the loan planner shows how extra payments affect the payoff date. That structure helps people whose debt problem is really a spending and cash flow problem, because the budget and the payoff plan stay in one place.
The price and learning curve are real barriers. At $14.99 per month, or $109 per year, YNAB costs far more than Undebt.it, and new users need time to learn zero-based budgeting. If you only want a payoff date, use a free planner instead, but if you want a budget that funds the payoff, YNAB is the stronger system.
- Full zero-based budget with loan planner
- Bank sync
- Strong habit and goal tools
- Higher price than standalone planners
- Learning curve for new budgeters
- No free plan beyond the trial
Unbury.me is the simplest tool on this list, and that simplicity is its strength. Enter loan details, see how long payoff takes on minimum payments, and test how extra payments shorten the timeline. You do not need an account for a quick check, and you do not link any bank account, which suits people who want a fast answer without sharing financial logins.
Long-term tracking is thinner. Saving a plan and following it over months is easier in Undebt.it or Debt Payoff Planner, and Unbury.me does not automate payments or sync balances. Use it for a first check, then move to a planner if you want to track the plan month by month.
- Free with no account needed for a quick check
- Simple snowball and avalanche comparison
- No bank linking
- No account sync or long-term tracking without an account
- Fewer features than Undebt.it
- Web only
Goodbudget uses digital envelopes to plan spending, and debt payments sit inside that plan as envelopes with targets. That method suits households that want to see, in plain terms, how much is set aside for each debt each month. A shared budget also helps couples who manage money together.
Debt payoff features are less detailed than Undebt.it, because Goodbudget is a budget first and a payoff tool second. Premium, at $10 per month or $80 per year, adds bank sync and unlimited envelopes, while the free plan covers basic budgeting. Choose Goodbudget when the budget is the priority and debt is one goal inside it.
- Envelope budgeting that pairs with debt goals
- Shared budgets for households
- Bank sync on premium
- Debt tracking is inside a budget, not a dedicated payoff engine
- Bank sync needs a paid plan
Changed works on a simple idea: round up card purchases to the next dollar and send the spare change toward a debt. That automation helps people who find it hard to set aside a large extra payment, because the extra money arrives in small, painless amounts. Seeing round-ups add up can also keep motivation going between larger payments.
The limit is scale. Round-ups alone rarely pay off a large balance quickly, so Changed works best alongside a main payoff plan, not instead of one. Check current fees and supported debt types on the vendor site before linking accounts, because terms for round-up services change.
- Rounds up everyday purchases toward debt
- Automates small extra payments
- Motivating for people who struggle to save a lump sum
- Extra payments are small, so impact depends on spending volume
- Linking accounts is required for round-ups
Bright is for people who want automation rather than a manual spreadsheet. It links creditor accounts, builds a payoff plan, and moves money toward that plan on a schedule, with progress updates as balances change. That hands-off approach suits busy households that will not update a manual planner each month.
Account linking is required for the automated features, which some users will not want, and Bright's fees and plan terms should be checked on its site before signing up. If you prefer full control and no bank link, Undebt.it is the better fit, but if automation is what keeps you on track, Bright is worth a look.
- Links creditor accounts and projects a payoff date
- Automates payments toward a plan
- Credit building features
- Automation needs account linking
- Fees and plan terms vary
- Not a pure manual planner
Empower, formerly Personal Capital, gives a free dashboard that pulls together bank, investment, and liability accounts into one net worth view. That context helps, because a payoff plan looks different when you can see all debts, assets, and cash flow together. The dashboard itself is free, which makes it a useful companion to a dedicated planner.
Empower is not a payoff engine. It tracks liabilities and shows totals, but it does not build a snowball or avalanche schedule in the way Undebt.it does. Use Empower to see the full picture, and use a planner on this list to build the month-by-month payoff order.
- Free dashboard for accounts and liabilities
- Net worth view shows debt in context
- Bank and investment linking
- Not a dedicated payoff planner
- No custom snowball or avalanche engine
- Advisory upsells inside the product
The National Foundation for Credit Counseling is not an app, but it belongs on a debt payoff list because it helps people an app cannot. Member agencies offer counseling, budget help, and, where suitable, a debt management plan that negotiates payments with creditors. That human help matters when debts feel unmanageable or when collectors are involved.
NFCC is not a self-serve calculator, and a debt management plan can affect credit accounts, so a counselor should explain the trade-offs before you enroll. Many member agencies offer free or low-cost first sessions, so it is a sensible call alongside any app, especially if minimum payments are hard to meet. This is not financial advice, and a counselor can give advice tailored to your situation.
- Nonprofit member agencies offer counseling by phone or video
- Help with budgets and debt management plans
- No product sales pressure
- Not an app with a payoff calculator
- Counseling availability and fees vary by agency
- A debt management plan may close some accounts
How we picked these
We compared official feature pages, pricing pages, and app store listings for debt payoff apps and services that work in October 2026, and we favored tools that clearly support snowball, avalanche, or custom payoff plans, or that provide credible nonprofit counseling. We left out tools that no longer operate and tools that mainly sell loans or credit products. We did not claim hands-on testing, and we marked prices as See website where vendor pricing was unclear or quote based.
How to choose a debt payoff method
Start by listing every debt with its balance, interest rate, minimum payment, and due date, then check those figures against your statements. An app can only plan from the numbers you enter, so a wrong rate or a missed balance will produce a wrong debt-free date. That list also shows whether one high-rate card is doing most of the damage, which changes the method choice.
Snowball, avalanche, or a custom order
The snowball method pays the smallest balance first, which gives quick wins and momentum. The avalanche method pays the highest interest rate first, which usually saves more interest over time. A custom order can blend the two, for example by clearing a small urgent debt first, then switching to the highest rate. There is no single right answer, and the best method is often the one you will stick with for months.
Make the plan survive a bad month
Set a minimum extra payment you can keep even in a tight month, rather than a large amount you will abandon. Automate the minimum payments so nothing is missed, and put any windfall, such as a tax refund or bonus, toward the current target debt. If a payment is missed or a rate changes, update the app the same week, because an out-of-date plan quietly stops working.
Know when to get human help
If minimum payments are unaffordable, if collectors are calling, or if a debt is in collections, an app alone may not be enough. A nonprofit counselor through NFCC can review the full budget, explain options, and, where suitable, set up a debt management plan. Avoid paid debt settlement firms that promise to cut what you owe without explaining fees and credit effects, and get any agreement in writing before paying.
Frequently asked questions
What is the best app for debt payoff?
Undebt.it is the best free debt payoff app for comparing strategies, and Debt Payoff Planner is the best mobile app for tracking a snowball or avalanche plan on your phone. YNAB is the best choice when debt payoff needs to sit inside a full budget. The best pick depends on whether you want a free planner, a mobile tracker, or a full budget.
What is the best debt snowball app?
Debt Payoff Planner and Undebt.it both support the debt snowball method well, with Debt Payoff Planner giving the clearer mobile view and Undebt.it giving the deeper strategy comparison. Both let you switch to avalanche or a custom order without re-entering your debts. Try the free version of each and keep the one you open more often.
Do debt payoff apps move money for you?
Some do and some do not. Undebt.it, Debt Payoff Planner, and Unbury.me plan payments but do not move money, so you pay each creditor yourself. Bright and Changed automate payments or round-ups once accounts are linked. Check whether an app moves money before linking an account, and keep control of payment dates and amounts.
Are free debt payoff apps safe?
Free planners that use manual entry, such as Undebt.it and Unbury.me, do not need bank logins, which limits exposure. Apps that link accounts should use a recognized connection service and publish a privacy policy, and you should check what data is stored. Never share full card numbers or passwords with a planner that does not need them.
Can a debt payoff app hurt my credit?
A planner itself does not change your credit, because it only calculates a plan from numbers you enter. Missing payments, closing accounts, or entering a debt management plan can affect credit, so keep minimum payments current while you follow a plan. If you are unsure about a step, talk with a nonprofit counselor before acting.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 zscaler alternatives
Best Zscaler Alternatives in 2026
Looking for zscaler alternatives? We compare 9 SASE and zero trust platforms on architecture, data protection, pricing, and fit for your network and team.
Read → zapier alternatives free
Best Zapier Alternatives Free in 2026
Nine automation tools for zapier alternatives free in 2026, all with genuinely free tiers, plus free plan limits, starting prices and upgrade paths explained.
Read → which platform is best for online reputation
Which Platform Is Best for Online Reputation in 2026
Wondering which platform is best for online reputation? We compare 8 review, listing, and response tools for small and multi-location businesses and agencies.
Read →