 ProMapRanker
Best Consumer Banking Companies Customer Service in 2026

Key takeaways
- This guide frames customer service on publicly reported factors such as branch access, phone and chat support, app tools, and complaint handling, not on invented scores.
- The best service fit depends on how you bank: branch visits, phone help, in-app messaging, or a mix of all three.
- Eligibility matters for USAA and Navy Federal, which serve military members and their families, not the general public.
- Fees, account terms, and support hours vary by product, so check the exact account you plan to open, not just the bank brand.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 USAA | Military members and families | See website | No | Visit |
 Navy Federal Credit Union | Military-affiliated members | See website | No | Visit |
 Capital One | Hybrid branch and digital banking | See website | No | Visit |
 Discover Bank | Online banking support | See website | No | Visit |
 Chase | Large branch network | See website | No | Visit |
 TD Bank | Branch service and hours | See website | No | Visit |
 Ally Bank | Digital-first banking | See website | No | Visit |
 PNC Bank | Branch and digital mix | See website | No | Visit |
 U.S. Bank | National branch and digital service | See website | No | Visit |
The best consumer banking companies customer service
We compared consumer banks and credit unions on service factors that readers can verify: branch availability, phone and digital support routes, app tools for everyday problems, and the clarity of fees and account terms. This is not a scored ranking, because service surveys use different methods and samples, and a bank that leads one survey may not lead another. Use this guide to shortlist banks that match how you prefer to get help.
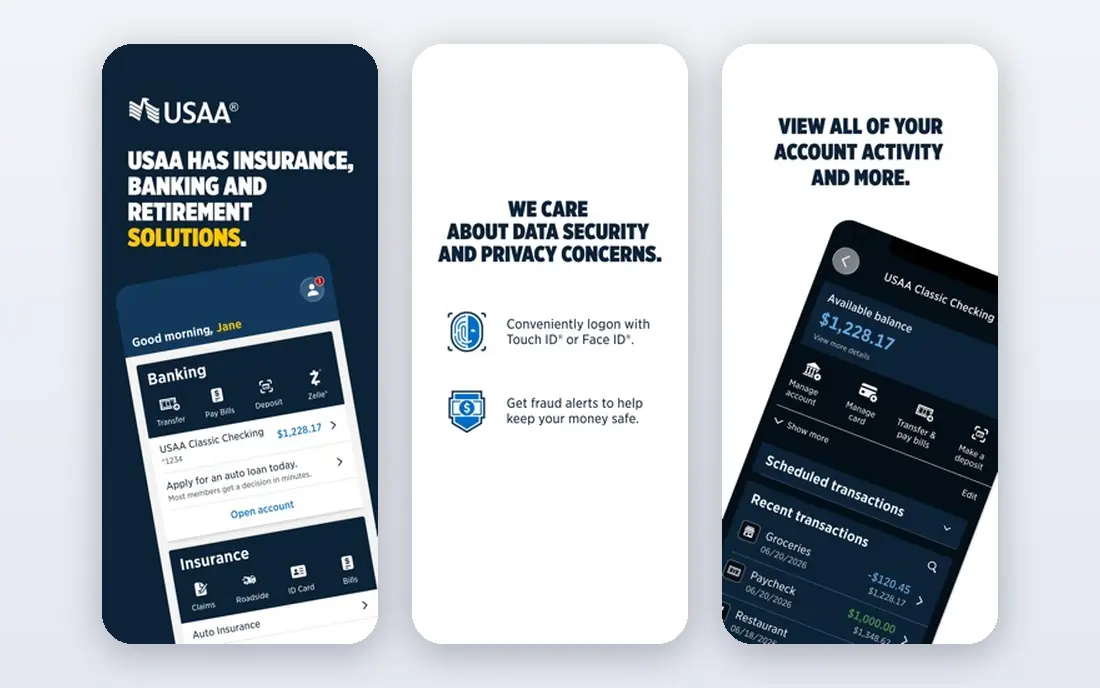
USAA is often discussed first in service conversations because it is built for a specific community: military members, veterans, and eligible family members. That focus shapes its support model, with phone, online, and mobile service designed for members who move frequently, deploy, or live far from a branch. USAA banking, insurance, and investment products are presented together, which can simplify money management for members who want one provider for several needs.
Eligibility is the hard limit. If you are not a military member or an eligible family member, USAA is not an option, no matter how strong its service reputation is. Members should also check product terms, fees, and support hours for the exact account they open, because service can vary by product. For eligible readers, USAA is a strong first comparison, especially for phone and digital help.
- Long-standing military focus
- Phone and digital support built for mobile members
- Broad banking and insurance range
- Eligibility is limited to military members and eligible family
- No general public branch network in the same way as large banks
Navy Federal Credit Union is the largest credit union in the United States by many public measures, and it serves military members, veterans, Department of Defense personnel, and eligible family members. As a credit union, it is member-owned, which shapes its service pitch around member benefit rather than shareholder return. Its support includes branches, many near military bases, along with phone and digital banking for members who move or deploy.
Like USAA, eligibility limits who can join. Readers without a military connection cannot open a Navy Federal account, so it should not be presented as a general public option. Eligible members should still compare account fees, loan terms, and support for the specific product they need, because credit union service can vary by branch and channel. For eligible members who value a military-focused credit union, Navy Federal is a natural shortlist entry.
- Member-owned credit union model
- Military community focus
- Branch, phone, and digital support
- Eligibility is limited to military-affiliated members
- Branch locations are concentrated near military communities
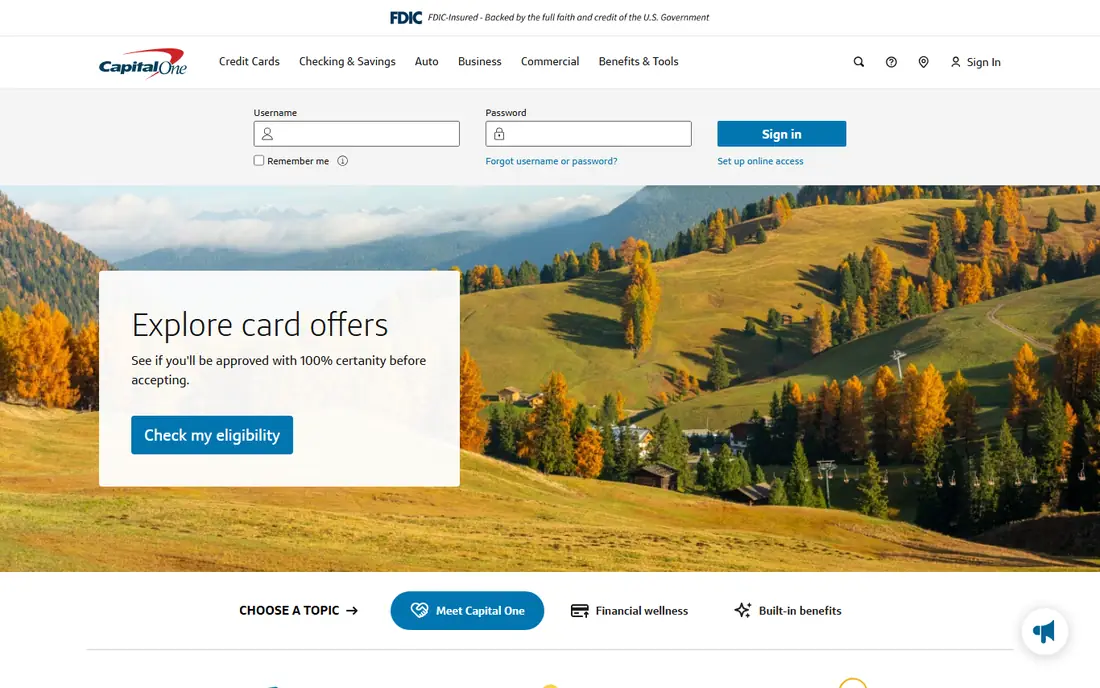
Capital One is a useful hybrid choice for readers who want strong digital banking but still want a place to talk to a person for complex questions. Its mobile app and online banking cover everyday tasks, while Capital One Cafes and branches in select cities offer face-to-face help, workspaces, and a less formal branch experience. Phone support is also a central part of its model, which matters for customers who do not live near a Cafe or branch.
The limit is geography. Capital One does not have a branch in every city, so readers who rely on regular branch visits should check local availability before switching. Service details, fees, and support hours also vary by account type, including checking, savings, and credit cards. For digital-first customers who like the option of in-person help in select cities, Capital One offers a balanced service mix.
- Digital tools plus Capital One Cafes and branches in select cities
- 24-hour phone support described by the company
- Clear app tools
- Branch coverage is not national in the same way as Chase
- Service details vary by product
Discover Bank suits customers who are comfortable banking entirely online and by phone, and who value clear terms over branch access. Its checking and savings accounts are managed through its app and website, with phone support for problems that cannot be solved digitally. That online-only model keeps the product range focused, which can make fees and terms easier to compare than at a large bank with many overlapping accounts.
The trade-off is in-person service. Discover does not offer a traditional branch network, so customers who need to deposit cash regularly, get a cashier check in person, or sit down with a banker will face limits. Support quality by phone therefore carries more weight, and readers should test how easy it is to reach a person for their account type. For online-first customers, Discover is a straightforward service comparison.
- Online bank model with phone support
- Clear account terms for many products
- App-based account management
- No traditional branch network
- Cash deposits and in-person help are limited
Chase is the strongest choice for readers who want a branch nearby almost anywhere in the United States. Its branch and ATM network is among the largest, and it combines in-person banking with a full app, secure messaging, and phone support. That breadth helps customers who move between cities, need in-person help for a mortgage or business question, and still want to manage everyday banking on a phone.
Fees are the main check. Some Chase checking accounts carry monthly service fees that can be waived by meeting balance, deposit, or other conditions, and overdraft and other fees vary by account. Readers should confirm the waiver conditions for the exact account they open, and not assume that branch access alone means low cost. For branch-first customers, Chase service breadth is hard to match, provided the account terms fit their balance and usage.
- Very large branch and ATM network
- App, secure messaging, and phone support
- Broad consumer product range
- Monthly fees apply to some accounts unless waived
- Service experience varies by branch
TD Bank is known for a branch service culture, with extended hours in many locations and a focus on in-person help. That model suits customers who value walking into a branch, talking to a banker by name, and getting help with accounts, cards, and loans without a long phone queue. TD also offers phone and digital banking, so branch customers are not cut off when they travel or need help outside branch hours.
Geography is the limit. TD branch coverage is strongest in eastern states and select other regions, so readers in other parts of the country may have few or no nearby branches. Account fees and waiver conditions also vary, so the service benefit should be weighed against total account cost. For readers in TD footprint who prefer branch service, it is a strong service-first option.
- Branch-focused service culture
- Extended hours in many locations
- Phone and digital support alongside branches
- Branch footprint is strongest in the East and select regions
- Fees vary by account
Ally Bank is a digital-first bank that appeals to customers who want to manage money online and by phone, with support available around the clock as described by the company. Its app covers checking, savings, and other accounts, with tools for transfers, bill pay, card controls, and alerts. For customers who rarely visit a branch, Ally offers a focused, digital service model without the overhead of a branch network.
In-person help is the trade-off, as with other online banks. Cash deposits, notarisation, and face-to-face advice are limited or handled through partner arrangements, so readers who need those services regularly should check options before opening an account. Fees and interest terms also vary by product and over time. For digital-first customers who value phone access at any hour, Ally is a solid comparison.
- Online bank with 24-hour phone support described by the company
- Clear digital tools
- No traditional branch fees structure in the same way as branch banks
- No branches for in-person help
- Cash handling options are limited
PNC Bank combines a substantial branch network with digital banking tools, including its Virtual Wallet product that separates spending, reserve, and growth money in one view. That mix suits customers who want branch access for important questions and digital tools for everyday budgeting, without choosing a purely online or purely branch bank. PNC also offers a broad consumer range, from checking and savings to mortgages and investment services through related businesses.
Regional coverage and fees need checking. PNC branches are concentrated in certain states, so readers outside those areas may rely more on digital channels. Some accounts carry monthly fees that can be waived under conditions, so the exact account terms matter. For customers in PNC footprint who want both branch and digital service, PNC offers a balanced option.
- Large branch network in many regions
- Virtual Wallet tools
- Phone, branch, and digital support
- Branch coverage varies by region
- Account fees and waiver rules need checking
U.S. Bank is a large national bank with branches and ATMs across many states, along with app, online, and phone support. Its consumer range covers checking, savings, cards, mortgages, and small business banking, which can suit households and small firms that want one bank for several needs. That national footprint helps customers who travel or move, because branch access is available in many regions, not just one state.
As with other large banks, fees and waiver conditions vary by account, and service can differ between branches and digital channels. Readers should compare the exact checking or savings account they plan to open, including monthly fees, overdraft terms, and ATM access. For customers who want a national bank with both branch and digital service, U.S. Bank is a dependable final comparison in this guide.
- Large national branch and ATM network
- App and phone support
- Broad consumer and small business range
- Fees vary by account
- Service experience varies by branch and channel
How we picked these
We compared official bank and credit union pages, product and support descriptions, branch and digital access, and public reporting on service surveys and complaint handling. We did not claim hands-on testing, and we did not invent satisfaction scores or rankings, because survey methods and samples differ. We favoured institutions with a current United States consumer banking offer, a clear support route, and a product range that ordinary customers can actually open and use.
How to judge customer service before you switch banks
Start with how you actually get help. List the last three times you needed bank help, such as a lost card, a disputed charge, a fee question, or a loan query, and note whether you solved it in an app, by phone, by message, or in a branch. Then test the banks on your shortlist against those moments: can you lock a card in the app, reach a person by phone at the hours you need, and visit a branch for a complex issue if you want to. A bank that is excellent for app users may be frustrating for branch users, and vice versa.
Next, check fees, support hours, and complaint routes in writing. Read the account agreement for monthly fees, waiver conditions, overdraft terms, and ATM fees, and note phone support hours for your account type. Ask how disputes are handled, how long a replacement card takes, and what happens if you need help while travelling. Keep a note of the answers, because service promises in advertising are less useful than the written terms and the actual support route.
Finally, switch in stages where possible. Open the new account, test a transfer, a bill payment, and a support contact, and keep the old account open until direct deposits and automatic payments have moved successfully. That staged switch reduces the risk of a missed payment during the move, and it gives you a real service test before closing the old account. If service disappoints in that test period, you can reconsider before the switch is complete.
Frequently asked questions
What counts as good customer service at a bank?
Good service usually means you can reach help quickly through your preferred channel, get a clear answer without repeated transfers, and resolve problems such as card issues, disputes, and fee questions without excessive effort. Branch access, phone hours, app tools, and clear fee terms all contribute, and the right mix depends on how you bank. No single survey captures all of these factors for every customer.
Are online banks worse for customer service than branch banks?
Not necessarily. Online banks often offer strong phone and in-app support, while branch banks offer in-person help that online banks cannot match. The better choice depends on whether you need branch visits, cash handling, or face-to-face advice. Online banks suit digital-first customers, while branch banks suit customers who regularly need in-person service.
Can anyone join USAA or Navy Federal?
No. USAA serves military members, veterans, and eligible family members, and Navy Federal serves military members, veterans, Department of Defense personnel, and eligible family members, under their own eligibility rules. Readers without that connection should compare general public banks such as Chase, Capital One, TD Bank, PNC, and U.S. Bank instead.
How do I compare bank fees alongside service?
Read the fee schedule for the exact account, including monthly service fees, waiver conditions, overdraft fees, ATM fees, and wire fees. A bank with strong service but high fees may still be a poor fit if you cannot meet waiver conditions. Compare total yearly cost for your balance and usage pattern, not just the headline service reputation.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 zscaler alternatives
Best Zscaler Alternatives in 2026
Looking for zscaler alternatives? We compare 9 SASE and zero trust platforms on architecture, data protection, pricing, and fit for your network and team.
Read → zapier alternatives free
Best Zapier Alternatives Free in 2026
Nine automation tools for zapier alternatives free in 2026, all with genuinely free tiers, plus free plan limits, starting prices and upgrade paths explained.
Read → which platform is best for online reputation
Which Platform Is Best for Online Reputation in 2026
Wondering which platform is best for online reputation? We compare 8 review, listing, and response tools for small and multi-location businesses and agencies.
Read →