 ProMapRanker
Best Commercial Banking Companies Fees and Rates in 2026

Full-service branch and business banking · Pricing starts at: See website
Key takeaways
- Monthly checking fees at large banks are often waivable, but transaction, cash deposit and wire fees change the true cost.
- Chase, Bank of America and Wells Fargo suit firms that need branches and cash handling, while digital-first banks suit firms that rarely handle cash.
- Commercial lending rates are quoted per borrower, so published account fees tell only part of the story.
- Always ask for the full fee schedule and a lending quote before switching, since fees and approval vary and are never guaranteed.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
| JPMorgan Chase | Full-service branch and business banking | See website | No | Visit |
 Bank of America | Established firms with broad account choice | See website | No | Visit |
 Wells Fargo | Flexible business accounts and SBA lending | See website | No | Visit |
 U.S. Bank | Business support with payment tools | See website | No | Visit |
 PNC Bank | Growing firms needing treasury tools | See website | No | Visit |
 Capital One | Hybrid digital and branch banking | See website | No | Visit |
 Truist | Multiple checking options | See website | No | Visit |
 Fifth Third Bank | Relationship banking for mid-size firms | See website | No | Visit |
The best commercial banking companies fees and rates
This is general information only, not financial advice. Fees, interest rates and lending approval vary by business, balance, transaction volume and location, and no rate is guaranteed. We compared official fee schedules, business banking pages and public comparisons to build this list, focusing on banks that serve commercial and larger small-business customers.
Chase suits firms that want branches, cash handling and a full product range from one bank. Its business checking tiers cover different transaction volumes, and its payments, merchant services and lending products sit alongside deposit accounts. For firms with several locations or frequent cash deposits, that branch access can matter more than a small monthly fee difference.
The cost catch is in the details. Monthly maintenance fees can often be waived with a minimum balance or linked accounts, but excess transaction and cash deposit charges apply beyond included allowances. Chase business banking pages list account-specific terms, so confirm the tier that matches your actual volume. Firms that deposit little cash and transact mainly online may find a cheaper digital option.
- Very large branch network
- Business checking, cards, payments and lending in one place
- Strong digital tools
- Monthly fees and transaction limits need careful checking
- Pricing varies by account tier
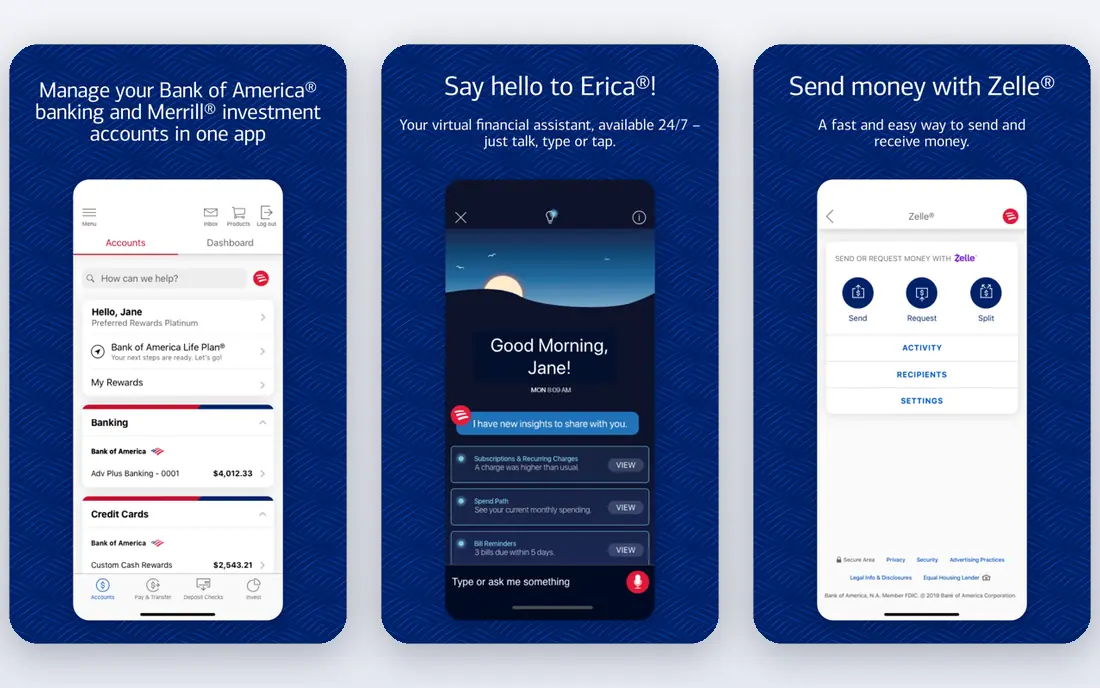
Bank of America offers several business checking tiers, which helps a firm pick an account that matches its transaction count rather than paying for unused capacity. Its credit lines, business cards and merchant services also suit established firms that want lending and payments from the same provider. Online and mobile tools include cash flow features that help finance teams track balances and upcoming payments.
Fees need close reading. One common account carries no monthly fee for an initial period, then a monthly fee that can be waived with a qualifying balance, debit purchases or relationship membership. Cash deposit allowances and excess transaction charges also affect firms with high paper volumes. Ask for the current fee schedule for your exact account tier before opening.
- Wide account range
- Business credit and merchant tools
- Cash flow and forecasting features
- Monthly fee rises after any introductory period on some accounts
- Excess transaction fees apply
Wells Fargo is a practical choice for firms that want branch access plus lending, including Small Business Administration loans where eligible. Its business checking range covers low-volume firms through to higher-volume accounts, and payroll, tax and merchant services can be bundled through the same provider. That breadth helps firms that prefer one relationship for daily banking and borrowing.
The fee structure rewards firms that keep a qualifying balance or meet activity thresholds, and penalises firms that exceed transaction or cash allowances. Wells Fargo publishes account fees and waiver rules, so model your real monthly transactions before choosing a tier. Firms with mainly digital payments may pay less elsewhere, while cash-heavy firms may value the branch network enough to accept the fees.
- Large branch network
- Several business checking tiers
- Strong SBA lending presence
- Transaction and cash fees beyond allowances
- Fee waivers depend on balance or activity
U.S. Bank suits firms that transact mainly digitally but still want branch and lending support. Some business accounts separate digital transactions from paper and teller transactions, which can keep costs down for firms that bank online. Payment solutions, business cards and treasury services sit alongside checking, so a growing firm can add services without switching banks.
Regional coverage is the limitation, since branch density differs across the country. Firms outside its core footprint should check local branch and ATM access before relying on in-person service. Fees also vary by account, so compare the tier that matches your transaction mix. For digitally focused firms inside its footprint, U.S. Bank offers a balanced package.
- Business checking with digital transaction focus
- Payment solutions
- Lending and treasury options
- Branch footprint varies by region
- Higher tiers cost more for added features
PNC fits firms that are outgrowing basic checking and need treasury management, payables and lending in one relationship. Its business checking tiers scale with transaction volume, and its treasury tools help finance teams manage cash, payments and reporting. Bookkeeping integrations also reduce manual reconciliation for firms that already use accounting software.
Fees and waivers differ by tier, and some waivers depend on linked services such as merchant processing. That makes a direct fee comparison tricky without your own numbers. Ask PNC for a fee estimate based on your monthly transactions, balances and cash deposits. Firms that use the treasury tools will get more value than firms that only need a basic account.
- Treasury management and lending tools
- Multiple business checking tiers
- Bookkeeping integrations
- Monthly fees on some tiers
- Waiver rules vary by account and relationship
Capital One appeals to firms that want digital-first banking with some branch access, without a monthly maintenance fee on certain business checking accounts. Its online and mobile tools handle payments, transfers and account management well, and business savings accounts sit alongside checking for firms that want to hold reserves. That combination suits firms that rarely need a branch but want one available.
The trade-off is scale and lending. Capital One's branch footprint is smaller than Chase or Bank of America, which matters for cash-heavy firms. Commercial loan rates and terms are quoted per borrower, so published account fees do not tell the full borrowing cost. For digitally focused firms, the fee structure is a clear advantage, provided branch access is not a daily need.
- No monthly fee on some business checking accounts
- Strong digital tools
- Business savings options
- Branch network is smaller than the largest banks
- Commercial lending terms vary by borrower
Truist offers a lineup of business checking accounts that lets a firm match fees to transaction volume and balance, rather than forcing one account on every business. Its small-business services cover checking, savings, cards and lending, and its treasury options suit firms with more complex cash needs. That range helps firms that expect to grow and change tiers over time.
Fee details vary by account and market, so a headline monthly fee does not capture the full cost for a specific firm. Digital tool preferences also differ, and some users may prefer the apps of larger rivals. Request the fee schedule for your state and tier, and test the online tools during onboarding. For firms in Truist's footprint, the account choice is the main draw.
- Several business checking tiers
- Small-business services
- Lending and treasury options
- Fees vary by tier and region
- Digital tools trail some larger rivals for some users
Fifth Third suits mid-size firms that value a relationship banker and a regional branch network. Its business checking tiers include waiver routes based on combined balances or card and relationship activity, which can keep monthly costs down for firms that bank broadly with Fifth Third. Lending and treasury services support firms that need more than basic checking.
Regional coverage limits its appeal for firms with national branch needs, and waiver rules require attention to balances and activity. Firms should model their own balances against the waiver thresholds before assuming the monthly fee disappears. Inside its footprint, Fifth Third offers a solid mix of personal service and commercial capability.
- Business checking with relationship waivers
- Lending and treasury services
- Regional branch strength
- Branch footprint is regional
- Fees depend on combined balances and card activity
How we picked these
We compared official bank fee schedules, business banking pages and public fee comparisons, and we kept only banks actively offering business and commercial banking in the United States in October 2026. We weighted branch access, fee transparency, waiver routes, treasury and lending breadth, and digital tools. We treated published monthly fees as a starting point only, since transaction, cash and wire fees often matter more.
How to compare fees and rates fairly
Build a simple monthly model before you choose. Count your transactions by type, including paper, teller, digital, ACH and card items, and total your cash deposits, since banks count these differently. Then apply each bank's fee schedule to those numbers, including monthly maintenance, excess transaction charges and cash processing fees. A bank with a higher monthly fee can still cost less if its allowances match your pattern.
For lending, request a written quote that states the rate type, margin, fees, term and any collateral or guarantee requirements. Compare the annual percentage rate and total fees, not just the headline rate, and ask how the rate changes if benchmarks move. Finally, check treasury fees, wire fees and account analysis charges, which commercial accounts often carry separately from checking fees.
Frequently asked questions
What fees do commercial banks usually charge?
Common charges include monthly maintenance, excess transaction fees, cash deposit processing, wires, treasury services and account analysis charges. The exact mix depends on the account tier and your transaction pattern, so ask for the full fee schedule.
Can I waive the monthly business checking fee?
Often yes, through a minimum balance, linked accounts, debit card activity or relationship membership, depending on the bank. Waiver rules vary by account, so confirm the exact threshold for your tier and check it against your usual balances.
Are commercial loan rates published?
Most commercial rates are quoted per borrower after underwriting, based on credit, collateral, term and market benchmarks. Published account fees do not guarantee a loan rate, and approval is never guaranteed.
Should a firm choose a digital bank or a branch bank?
It depends on cash handling and service needs. Firms that deposit cash regularly or need in-person support usually benefit from branches, while firms that transact online may save fees with a digital account. Some firms use both, with a branch bank for cash and a digital account for payments.
What is account analysis pricing?
Account analysis is a commercial banking method where the bank offsets service charges against an earnings credit on your balances. It suits higher-balance firms with many services, but the calculation is complex, so ask the bank to model it on your actual activity.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 worlds best local seo company
8 Worlds Best Local SEO Companies for Map Pack Growth in 2026
Compare the worlds best local seo company options for Google Business Profile work, citations, reviews, and multi-location rankings and reporting in 2026.
Read → world's best web hosting company
World's Best Web Hosting Company in 2026
Searching for the world's best web hosting company? We compared 10 hosts on price, renewal rates, speed, and support to help you choose well today in 2026.
Read → who's got the best nanny tax services
Who's Got the Best Nanny Tax Services in 2026
We answer who's got the best nanny tax services, comparing full filing, back taxes, software, and pricing so families can handle nanny taxes correctly.
Read →