 ProMapRanker
Best Cash Advance Apps in 2026

Key takeaways
- EarnIn is our overall pick for workers with regular direct deposits, with no mandatory fees and access to wages already earned.
- Dave ExtraCash suits small, occasional advances, while Brigit pairs advances with budgeting tools and overdraft prediction.
- Free standard delivery usually takes one to three business days, so instant delivery fees are the main cost to watch.
- Most apps here do not run a hard credit check, but they do check bank history, income patterns and direct deposits.
- Cash advances carry fees and risk, and this guide is for information only and is not financial advice. Use them sparingly and check the total cost first.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 EarnIn | Earned wage access | Free | Yes | Visit |
 Dave ExtraCash | Small occasional advances | $5 per month | No | Visit |
 Brigit | Budgeting plus advances | $8.99 per month | No | Visit |
 MoneyLion Instacash | Larger advances | Free | Yes | Visit |
 Chime MyPay | Chime banking users | Free | Yes | Visit |
 Albert | Advances plus saving tools | See website | No | Visit |
 Klover | No-fee base advances | Free | Yes | Visit |
 Current Paycheck Advance | Current banking users | Free | Yes | Visit |
 Gerald | Fee-free advances | Free | Yes | Visit |
The best cash advance apps
We compared cash advance apps on advance limits, mandatory fees, instant delivery fees, delivery speed, eligibility and privacy practices, using official product pages, pricing pages, app store listings and public reviews. The best app to borrow money instantly is not always the cheapest, since instant fees, subscriptions and tips can add up fast on small amounts. The best instant cash advance apps below include earned wage access tools and bank-linked advances, so you can match the app to your pay pattern and bank.
EarnIn is our pick for the best cash advance app for workers with a regular paycheck. It is earned wage access rather than a traditional loan, which means you access pay you have already earned before payday. Eligible users can access up to $200 per day, with a maximum of $1,000 per pay period, with no interest and no mandatory fees. Standard delivery is free and takes one to three business days, while Lightning Speed delivery moves funds in minutes for a fee starting at $3.99. Tips are optional and do not affect service.
The limits are tied to work verification. EarnIn checks your bank account and work pattern, using timesheets, location data or employer systems in many cases, and new users often start with a lower daily limit that grows with history. If you have steady direct deposits and a regular pay cycle, EarnIn gives the cleanest cost model on this list, since waiting for free delivery means the advance itself costs nothing.
- No mandatory fees or interest on Cash Out
- Access up to $200 per day and $1,000 per pay period
- No credit check for eligibility
- Needs regular direct deposits and work verification
- Instant Lightning Speed delivery starts at $3.99
Dave ExtraCash suits users who need a small advance now and then, rather than regular wage access. Eligible users can advance up to $500, with no hard credit check and repayment tied to a linked bank account. Instant delivery to a Dave checking account is free in many cases, which is a useful perk for Dave banking users.
Costs need careful reading. Dave membership costs up to $5 per month, and ExtraCash also carries a service fee equal to the greater of $5 or 5% of the advance, capped at $15 in many cases. Instant delivery to an external debit card adds a further fee of about 1.5%. Dave is best when you use free standard delivery or a Dave account, and when you treat the advance as an occasional bridge rather than a regular income top-up.
- Advances up to $500 for eligible users
- No hard credit check
- Overdraft alerts and budgeting tools included
- Membership plus a service fee on each advance
- Instant delivery to an external card costs extra
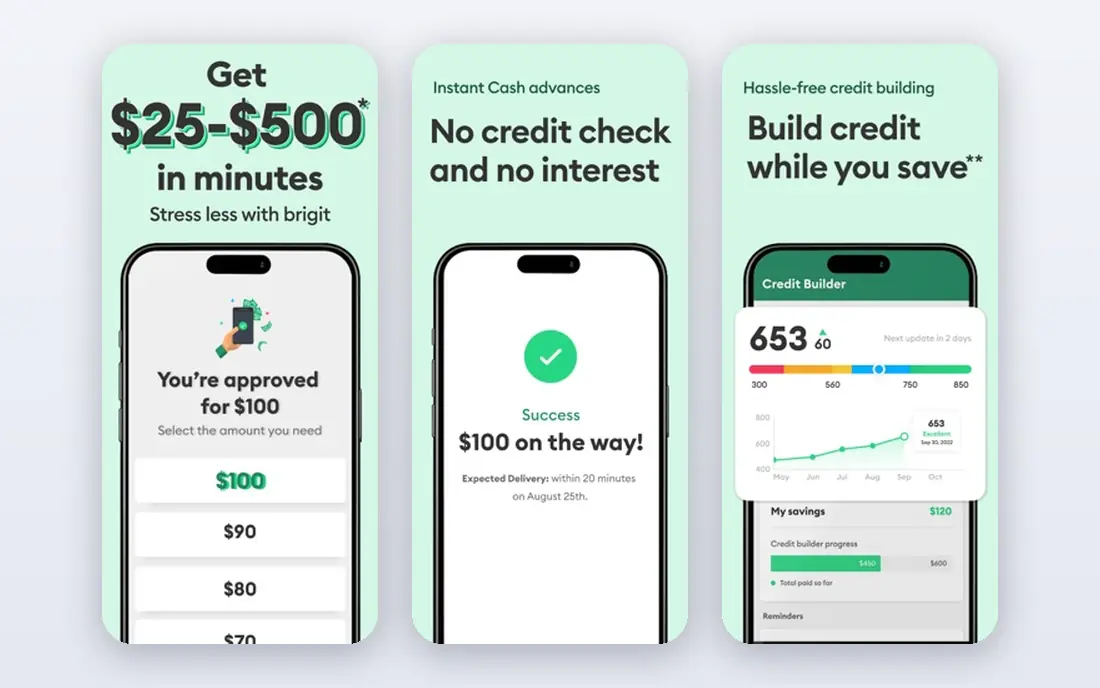
Brigit pairs cash advances with financial health tools, which suits users who overdraw often and want warning before a fee hits. Eligible users can advance from $25 to $500, with an average advance far lower than the maximum, and Brigit monitors linked accounts to predict overdrafts. Budgeting tools, spending insights and credit building features sit alongside advances in the Plus and Premium plans, priced at $8.99 and $15.99 per month in recent pricing. Express delivery costs from $0.99 to $5.99, while standard delivery takes one to three business days.
The subscription is the main catch. You pay every month whether or not you take an advance, so a single $50 advance in a year can cost far more than the advance itself once twelve months of fees are counted. If you only need one advance, a no-subscription app such as EarnIn or MoneyLion will usually cost less.
- Advances from $25 to $500 for eligible users
- Overdraft prediction and budgeting tools
- No hard credit check
- Subscription required to access advances
- Subscription runs even in months with no advance
MoneyLion Instacash is a strong choice for users who need a larger advance without a subscription. Basic Instacash offers up to $500 for eligible users, rising to $1,000 for users with a RoarMoney account and qualifying history. There is no mandatory subscription for basic Instacash, and standard delivery is free, taking one to five business days depending on the bank. MoneyLion also offers banking, investing and credit building tools in the same app, which can suit users who want several money products in one place.
Instant delivery is where costs appear. The fee ranges from $0.49 to $8.99 depending on amount and delivery method, so a small instant advance can carry a high fee relative to its size. Higher limits also take time to build, since new users often start well below the maximum. MoneyLion is best for users who can wait for free standard delivery or who already bank with MoneyLion, and who want a larger limit than Dave or Brigit offer without a monthly fee.
- Advances up to $500, or $1,000 with a RoarMoney account
- No mandatory subscription for basic Instacash
- No hard credit check
- Instant delivery fee ranges from $0.49 to $8.99
- Higher limits need a MoneyLion account and history
Chime MyPay is the simplest advance option for existing Chime customers. Eligible users with qualifying direct deposits can access up to $500 of earned pay before payday, with no mandatory fees for standard access. Chime also offers SpotMe overdraft cover for eligible users, which can complement MyPay for small shortfalls.
The limit is availability. MyPay is only for eligible Chime banking customers with qualifying direct deposits, so non-Chime users cannot use it without switching banks. Instant delivery carries a fee of 3% of the advance, with a $2 minimum and $5 maximum per advance in recent terms, while standard access is free within 24 hours in many cases. For Chime users, MyPay is one of the cleanest advance options available. For everyone else, EarnIn or MoneyLion are easier starting points.
- Advances up to $500 for eligible Chime users
- No mandatory fees for standard access
- No hard credit check
- Only available to eligible Chime banking customers
- Instant delivery fee applies on some advances
Albert combines cash advances with saving and budgeting tools, which suits users who want help building a buffer as well as covering a shortfall. Eligible users can access advances through the app, with limits that grow with bank history and direct deposits. Automatic saving, spending insights and financial guidance sit alongside advances, and the app aims to help users reduce repeat borrowing over time rather than only covering each gap.
The paid plan is the catch. Full advance access and guidance features sit behind the Genius subscription, priced in recent sources at $14.99 per month, so the total cost of an occasional advance can be high. Instant delivery also carries a fee, while standard delivery takes two to three business days. Albert is best for users who will use the saving and guidance tools every month. Users who only need an advance should compare EarnIn, MoneyLion or Chime first, since those options have no mandatory subscription.
- Advances for eligible users alongside saving tools
- Automatic saving and budgeting features
- No hard credit check for advances
- Full advance access sits behind a paid Genius plan
- Instant delivery fee applies
Klover offers a no-subscription route to small advances, which makes it worth a look for users who dislike monthly fees. Eligible users can access advances based on bank history and recurring deposits, with no mandatory subscription for the base tier. A points system rewards activities such as surveys, receipts and engagement, and points can help raise limits over time. That model suits users who are comfortable with a data-sharing trade in return for free access, though privacy settings deserve a careful review.
Instant delivery fees are the main cost to watch. Standard delivery is free but takes about three business days, so Klover is not ideal for a same-hour emergency unless you accept the instant fee. New users also start with low limits, so Klover works best as a backup app that you build up over time rather than a first-week large advance.
- No mandatory subscription for base advances
- No hard credit check
- Points system can raise limits over time
- Instant delivery fees can be high on larger amounts
- Base limits start low for new users
Current Paycheck Advance suits users who already bank with Current and receive payroll deposits there. Eligible users can access up to $750 before payday, with no mandatory fee for standard access and repayment from the next payroll deposit. Since the advance sits inside the Current banking app, setup is simple for existing customers, and the higher maximum beats Dave, Brigit and Chime MyPay for users who qualify at the top end.
Availability is narrow by design. You need a Current account with payroll deposits into Current, so non-Current users cannot access the advance without switching banks. Limits also depend on payroll history, so new Current users may start well below $750. For Current customers with steady payroll deposits, this is a clean, low-cost advance option. For others, EarnIn and MoneyLion offer similar limits without a bank switch.
- Advances up to $750 for eligible Current users
- No mandatory fee for standard access
- No hard credit check
- Only available to Current banking customers with payroll deposits
- Limits depend on payroll history
Gerald stands out for its fee model. The app charges no mandatory fees, interest, late fees or subscriptions for cash advances, and eligible users can receive funds in minutes at no extra delivery cost. That makes Gerald one of the cheapest advance apps on paper, especially for small, urgent amounts where instant fees elsewhere can be high. Gerald also offers buy now, pay later features in its own store, which tie into how advances are made available.
That store link is the catch. Advance access requires a qualifying purchase through the Gerald store, so you cannot simply open the app and advance cash without that step. Limits are also modest for new users, often around $200 or less, and grow with history. Gerald is best for users who already shop through Gerald or who are willing to make a small qualifying purchase to gain a fee-free advance. Users who want a larger advance without a purchase step should look at EarnIn or MoneyLion instead.
- No mandatory fees, interest or subscriptions for advances
- Instant delivery available for eligible users
- No hard credit check
- Advance access requires a qualifying purchase in the Gerald store
- Limits are modest for new users
How we picked these
We compared official feature pages, pricing pages, app store listings, privacy policies and public reviews for cash advance apps that work in the United States in October 2026. We looked at advance limits, mandatory fees, instant fees, delivery speed, eligibility rules and whether each app runs a hard credit check. We favoured apps with clear fee disclosure, bank-level security practices and free standard delivery. We did not claim hands-on testing of borrowing or repayment, and we did not rank on maximum limits alone, since new users rarely qualify for the maximum at first.
This guide is for information only and is not financial advice. Cash advances carry fees and risk, including the risk of repeat borrowing when repayment leaves too little for the next pay cycle. Check the total cost, including subscriptions, service fees, tips and instant delivery fees, before you accept an advance, and consider lower-cost options first.
Using cash advance apps without falling into a cycle
Start with the cheapest path for your timing. If a bill is not due for several days, free standard delivery costs nothing on several apps here, while instant delivery can cost several dollars on a small amount. Add up every cost for one advance, including any monthly subscription divided across the advances you actually take.
Lower-cost options to check first
Before you advance, check whether your employer offers earned wage access directly, since employer tools can be cheaper than consumer apps. Keep an emergency fund, even a small one, separate from spending money, so one unexpected bill does not force an advance every month.
What eligibility really means
Most apps here skip a hard credit check, but that does not mean approval is automatic. Apps check bank history, recurring deposits, account age, spending patterns and, for EarnIn, work verification.
Frequently asked questions
What is the best cash advance app with no credit check?
EarnIn, Dave, MoneyLion Instacash, Brigit and Gerald all skip a hard credit check for eligible users, basing decisions on bank and income history instead. EarnIn leads for no-fee earned wage access, while MoneyLion suits users who want a larger limit without a subscription.
What is the best app to borrow money instantly?
The best app for cash advance speed depends on your bank and account. EarnIn Lightning Speed, Dave instant delivery and Gerald instant delivery can move funds in minutes for eligible users, but instant fees apply on several apps. If you can wait one to three days, free standard delivery is far cheaper.
What are the best instant cash advance apps no credit check?
EarnIn, MoneyLion Instacash and Gerald are strong no credit check choices for instant or fast delivery, with EarnIn leading on mandatory fees and MoneyLion leading on maximum limits. Check instant fees before you choose, since a fast $100 advance can cost several dollars in delivery fees alone.
How much can the best cash advance apps lend at first?
New users often start at $25 to $100, even when the advertised maximum is $500 or $1,000. Limits grow with direct deposit history, bank balance and repayment record, so treat the maximum as a later goal rather than a first-week promise.
Are cash advance apps safe?
Established apps use bank-level encryption and account connections through services such as Plaid, but safety also depends on fees and repayment terms. Read the full fee schedule, check privacy settings, avoid apps that hide subscription or instant fees, and never advance more than you can repay on payday without hardship.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 youtube alternatives
Best YouTube Alternatives in 2026
Looking for youtube alternatives in 2026? We compare Vimeo, Dailymotion, Twitch, Rumble, and more on price, audience, monetization, control and privacy.
Read → what's the best ai tool for photo editing
What Is the Best AI Tool for Photo Editing in 2026
What is the best AI tool for photo editing? We compare ten tools for 2026, from Photoshop and Lightroom to Luminar, Topaz, Canva and mobile editors today.
Read → twitter alternatives
Best Twitter Alternatives in 2026
Compare the best twitter alternatives for 2026, from Bluesky, Threads, and Mastodon to Reddit, Tumblr, and Micro.blog, with free plans and audience notes.
Read →