 ProMapRanker
Best Buy Now Pay Later Apps in 2026

Key takeaways
- Pay in 4 plans are usually interest free when every payment is made on time, while longer monthly plans often carry interest.
- Affirm stands out for larger purchases and for charging no late fees, while Klarna offers the widest mix of short term payment choices.
- Late fees, interest rates and credit reporting differ sharply, so read the plan terms at checkout before you confirm.
- A buy now pay later plan is still debt, and stacking several plans at once can make repayments hard to track.
- This is not financial advice. Trading or borrowing carries risk, and you should only split a purchase you can afford to repay.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 Affirm | Larger purchases | Free | Yes | Visit |
 Klarna | Flexible payment choices | Free | Yes | Visit |
 Afterpay | Simple Pay in 4 shopping | Free | Yes | Visit |
 PayPal Pay Later | Existing PayPal shoppers | Free | Yes | Visit |
 Sezzle | Budget shoppers building credit | Free | Yes | Visit |
 Zip | Shopping almost anywhere | Free | Yes | Visit |
 Splitit | Using an existing credit card | Free | Yes | Visit |
 Shop Pay Installments | Shopify store shoppers | Free | Yes | Visit |
The best buy now pay later apps
We compared the best buy now pay later apps on plan types, fees, interest, store coverage and credit checks. The eight below cover the main ways people split a purchase in the United States in 2026.
Affirm works well when a purchase is too large for a four payment plan. Monthly plans can stretch over a longer period, and the app shows the total interest cost before you agree, which makes the true price clear. That transparency matters for furniture, electronics and travel, where a small monthly figure can hide a large total.
The catch is interest. Pay in 4 is interest free, but monthly financing can range from 0 percent to 36 percent APR depending on the merchant and your profile. Affirm charges no late fees, which is a real advantage, but missed payments can still be reported and can affect your credit. Use it for a planned purchase with a fixed end date, not for everyday spending.
- No late fees
- Total cost shown before checkout
- Longer monthly plans available
- Longer plans can carry interest up to 36 percent APR
- Approval depends on credit and purchase size
Klarna gives shoppers more choices at checkout than most rivals. You can split a purchase into four interest free payments, pay the full amount within 30 days, or choose monthly financing for a larger order. A virtual card also lets you use Klarna in stores through a mobile wallet, which widens its use beyond online checkout.
That flexibility needs care. Monthly financing can carry interest, and late fees apply when a payment is missed. Klarna suits shoppers who want options and who will pay on time, but it is less forgiving than Affirm if a payment slips. Check which plan is selected before you confirm, because the default is not always the interest free one.
- Pay in 4, Pay in 30 and monthly financing
- Virtual card for in store use
- Wide merchant network
- Late fees up to 7 dollars per missed payment
- Monthly financing can carry interest
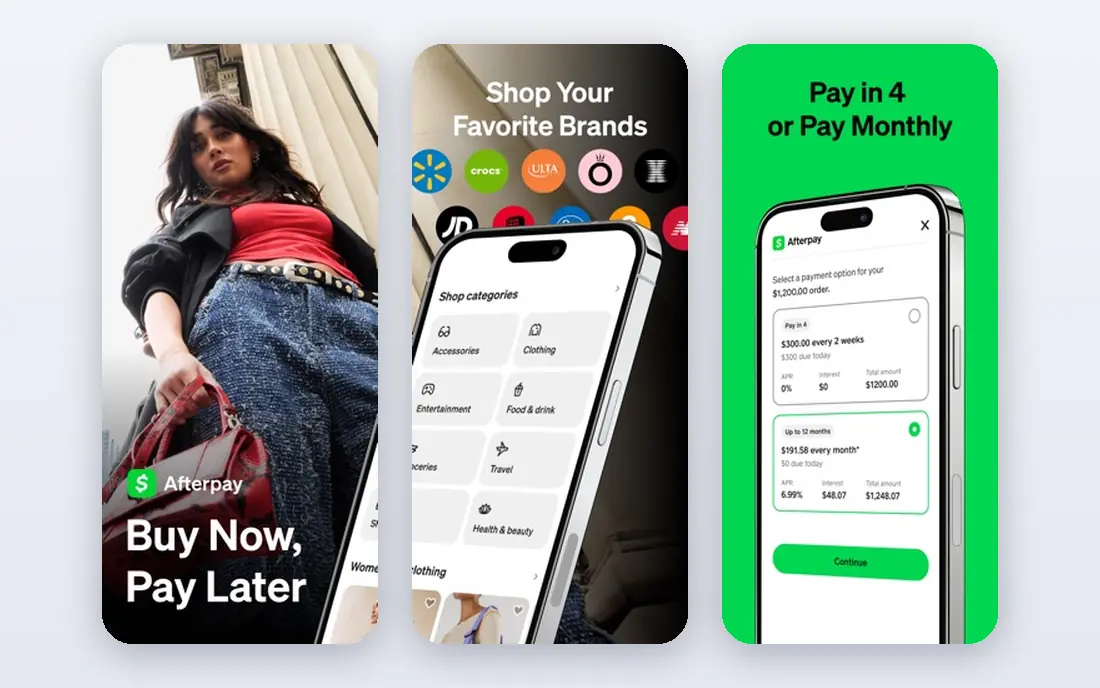
Afterpay keeps the model simple: one purchase split into four equal payments, due every two weeks, with no interest when paid on time. That simplicity is why it fits fashion, beauty and lifestyle shopping so well. The app also offers an in store card, so the same plan can work at a physical checkout.
The limits are the main drawback. New users often start with a lower spending limit that grows with a good payment history, and late fees can add up to 25 percent of the order total. Afterpay is a good pick if you want a short, predictable plan and you are comfortable with a two week rhythm. It is not built for large purchases that need months to repay.
- Four interest free payments every two weeks
- Simple structure
- In store card through the app
- Late fees capped at 25 percent of the order
- Spending limits vary and can start low
PayPal Pay Later is the easiest option for people who already pay with PayPal. Pay in 4 appears inside the normal checkout flow, with no separate app to learn and no new account to set up in most cases. That convenience matters when you are checking out quickly and do not want to add another payment tool.
The trade off is scale. Pay in 4 is designed for smaller purchases, while larger monthly plans can carry interest and have different terms. PayPal also reports some monthly plans, so a longer plan is not the same as a short interest free split. Pick this one when you already use PayPal and the purchase fits a four payment plan.
- Built into PayPal checkout
- Pay in 4 with no interest
- No late fees on Pay in 4
- Pay in 4 limits are lower than monthly plans
- Monthly plans can carry interest
Sezzle is built around budgeting. Its Pay in 4 plan splits a purchase with no interest, and you can reschedule a payment without a fee in many cases, which helps when payday moves by a few days. Sezzle Up, an optional feature, reports on time payments to credit bureaus, which can help people who want to build a credit history while shopping.
Watch the fees. Some Sezzle plans and payment methods add a service fee, and late fees can apply if a payment is missed. The app suits careful shoppers who want a little breathing room and who value credit reporting. It is less suited to large purchases, where a longer Affirm style plan may fit better.
- Pay in 4 with no interest
- Free payment rescheduling
- Optional credit reporting through Sezzle Up
- Some plans add service fees
- Late fees can apply
- Limits vary by merchant
Zip, formerly Quadpay, stands out because it is not limited to partner stores. A virtual card lets you shop at many online and in store retailers that accept Visa, then split the purchase into four payments. That freedom is useful for stores that do not offer a built in pay later button at checkout.
The cost needs a close look. Zip can charge a small fee per installment on some purchases, and late fees apply for missed payments. Read the fee shown before you confirm, because the total can differ from a partner store plan that charges no fee. Zip is a strong pick when the store you want does not offer another pay later option.
- Virtual card works where Visa is accepted
- Pay in 4 with no interest
- Simple app flow
- Per installment fees can apply
- Late fees up to 7 dollars
- Limits can be modest at first
Splitit takes a different route. Instead of a new loan, it splits a purchase across your existing credit card, holding the full amount on the card while charging it in installments. That means no interest from Splitit itself and no separate credit check in many cases, which appeals to cardholders who want to spread a cost without opening a new account.
The limit is your card. You need enough available credit for the full purchase, and your card issuer may still charge interest if the balance is not paid in full under your card terms. Store coverage is also smaller than the biggest pay later brands. Splitit fits a cardholder with room on a card who wants a clean installment plan for a larger purchase.
- No interest and no new credit application in most cases
- Uses your existing card limit
- No late fees from Splitit
- Requires an existing credit card with room on it
- Fewer stores than Klarna or Affirm
- Card issuer terms still apply
Shop Pay Installments appears at checkout in Shopify stores, which makes it almost invisible until you need it. Four interest free payments cover most everyday orders, while monthly plans cover larger purchases with interest shown at checkout. If you shop often on Shopify stores, this is often the fastest pay later choice because your payment details are already saved.
The obvious limit is coverage. It only works where Shop Pay is offered, so it cannot replace a general pay later app for other retailers. Monthly plan interest can also be high, so a larger order deserves a comparison with Affirm before you commit. Use Shop Pay for convenience inside Shopify, and a broader app elsewhere.
- Built into Shopify checkout
- Four interest free payments
- Monthly plans for larger orders
- Only at Shopify stores
- Monthly plans can carry interest from 10 to 36 percent APR
- Limits vary
How we picked these
We compared official feature pages, pricing pages and app store listings for the leading buy now pay later services, plus public reviews of fees and plan terms. We kept only services that work in the United States in October 2026, that offer a clear Pay in 4 or monthly plan, and that publish their fee and interest terms. We left out services with unclear terms or very narrow store coverage, and we did not claim hands on testing that did not happen.
What to check before you split a payment
Start with the total cost, not the installment size. A 50 dollar monthly payment looks small, but over 24 months with interest it can cost far more than the sticker price. Look for the APR, any fees, and the final total shown at checkout, and compare that total with paying in full or using a low interest card.
Next, check the payment dates against your paydays. Pay in 4 plans run every two weeks, which does not always line up with a monthly salary. A plan that falls a few days before payday is more likely to be missed, and missed payments bring fees and possible credit reporting. Set a reminder for each due date, and avoid stacking more than one or two active plans at once.
Finally, check credit reporting and returns. Some short plans do not report on time payments, while some monthly plans do report missed payments. Returns can also be slower with pay later plans, because the refund has to pass through the provider before your installments stop. If you often return items, a short plan with a clear refund process is safer than a long monthly plan.
Frequently asked questions
What is the best buy now pay later app overall?
Klarna is a strong overall pick for flexibility, because it offers Pay in 4, Pay in 30 and monthly financing in one app. Affirm is often better for larger purchases, because it offers longer terms and no late fees. The best choice depends on the purchase size and the plan length you need.
Are buy now pay later apps interest free?
Pay in 4 plans are usually interest free when every payment is made on time. Longer monthly plans often carry interest, with rates that can reach 36 percent APR depending on the provider and your profile. Always check the APR shown at checkout before you confirm a monthly plan.
Do buy now pay later apps affect your credit score?
Most providers run a soft credit check for Pay in 4, which does not affect your score. Longer monthly plans may involve a harder check, and missed payments can be reported to credit bureaus by some providers. Sezzle Up and similar optional features report on time payments, which can help build credit history.
What are the best alternatives to Affirm?
Klarna and PayPal Pay Later are the closest alternatives for general shopping, while Afterpay and Sezzle suit smaller Pay in 4 purchases. Zip works well when a store does not offer a built in pay later option, and Splitit suits shoppers who prefer to use an existing credit card. Compare fees and plan length, not just the installment size.
Can I use buy now pay later in stores?
Yes, several apps offer a virtual card for in store use, including Klarna, Afterpay and Zip. You add the card to a mobile wallet and pay at checkout, then repay in installments through the app. Availability depends on the store and the card network, so check the app before you shop.
What happens if I miss a payment?
Most providers charge a late fee, and some report the missed payment to credit bureaus. Affirm charges no late fees, but missed payments can still affect your credit on longer plans. If you know a payment will be late, contact the provider early, because some offer a free reschedule.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 zendesk alternatives
Best Zendesk Alternatives in 2026
Compare the best Zendesk alternatives in 2026, from budget help desks to AI-first support tools, with current pricing, free plans, and honest trade-offs.
Read → wordpress alternatives
Best WordPress Alternatives in 2026
Looking for the best WordPress alternatives? We compare 8 free and paid options for blogs, business sites, stores, and developer-led projects in 2026.
Read → which real estate company has the best training
Best Real Estate Company Training in 2026
Compare which real estate company has the best training, from Keller Williams and eXp to Compass and Coldwell Banker, by program, mentor, and fit in 2026.
Read →