 ProMapRanker
Best App for Direct Deposit in 2026

Key takeaways
- Chime, SoFi, Current, Varo and Cash App all offer pay up to two days early with no monthly fee, but early pay depends on when your employer sends payroll.
- Current and Chime add useful extras, such as paycheck advances and overdraft cover, once you meet deposit conditions.
- Ally, Capital One and Discover suit people who want a traditional bank account with early pay plus branch or cash back benefits.
- Early pay is not a promise for every paycheck. First deposits, large amounts and employer timing can delay availability.
- This is general information only, not financial advice. Fees, rates and eligibility vary, so check the account terms before you move your direct deposit.
Quick comparison
| Pick | Great for | Pricing starts at | Free tier | |
|---|---|---|---|---|
 Chime | Simple early pay with SpotMe | Free | Yes | Visit |
 Cash App | Easy setup with a debit card | Free | Yes | Visit |
 SoFi | Full bank account with savings | Free | Yes | Visit |
 Current | Paycheck advance with early pay | Free | Yes | Visit |
 Varo | Early pay with savings tools | Free | Yes | Visit |
 PayPal | Direct deposit into a payment account | Free | Yes | Visit |
 Ally Bank | Online bank with early pay | Free | Yes | Visit |
 Capital One | Early pay with a large bank | Free | Yes | Visit |
 Discover | Cash back debit with early pay | Free | Yes | Visit |
The best app for direct deposit
We compared official product pages and recent comparison guides, and we focused on early pay timing, monthly fees, savings features, overdraft cover and how easy it is to set up direct deposit. All accounts below are free to open in their basic form, and early pay usually means up to two days early, not a fixed guarantee.
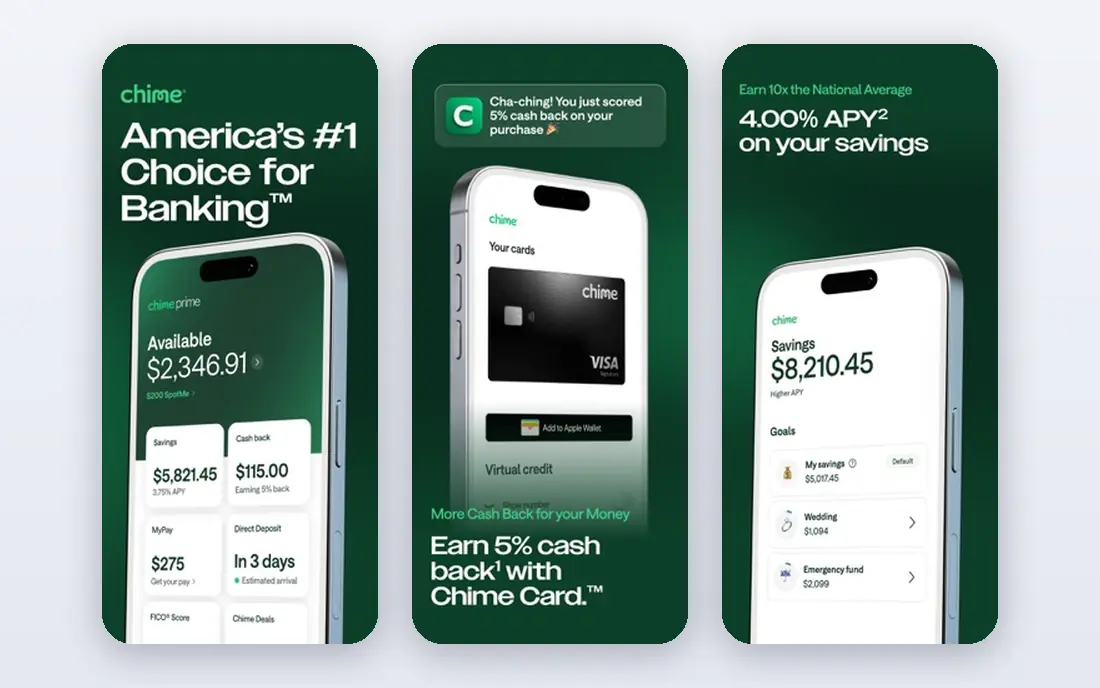
Chime is the simplest early pay choice for most people. Open a checking account, give your employer the routing and account numbers from the app, and payroll can arrive up to two days early when your employer sends it through ACH. There is no monthly fee and no minimum balance, which removes the usual conditions that block early pay. SpotMe adds a cushion for eligible debit purchases, starting at $20 and rising to $200 or more with qualifying direct deposits. The savings rate also varies, with higher rates for Chime Prime members who receive at least $3,000 in qualifying monthly deposits. Chime suits mobile first users who want early pay without a branch or a fee.
- Pay up to two days early
- No monthly fees
- SpotMe up to $200
- Large fee free ATM network
- Chime is a fintech, not a bank itself
- SpotMe needs qualifying deposits
- Savings rate depends on Chime Prime status
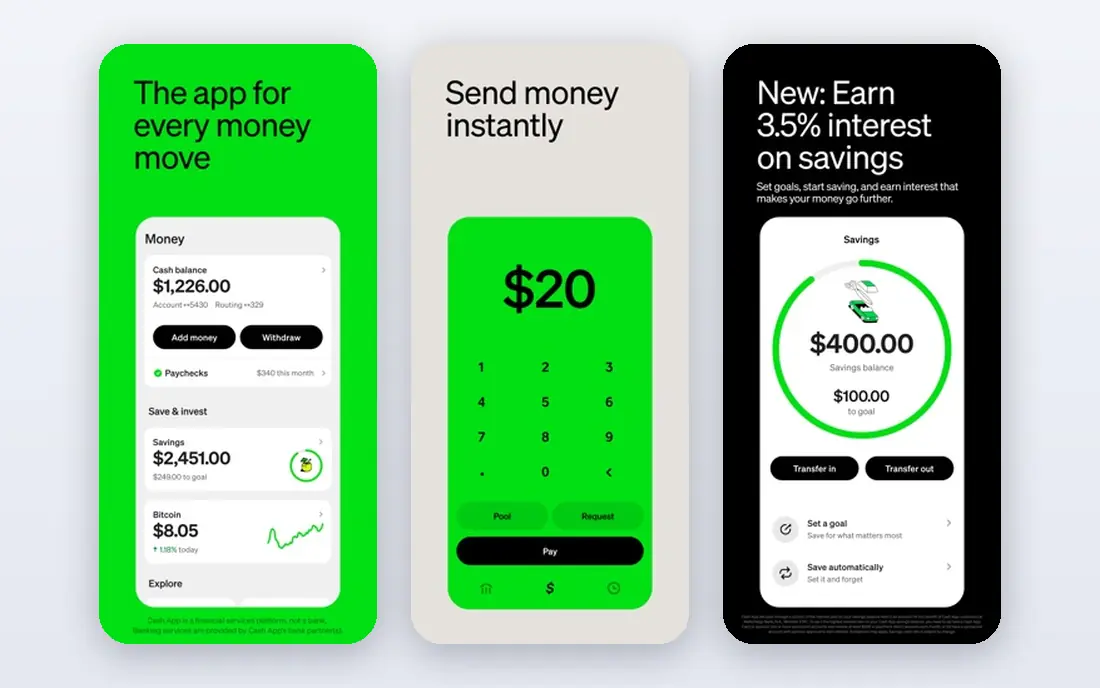
Cash App is the fastest way to set up direct deposit if you already use the app for payments. You can find your routing and account numbers in the app, share them with payroll, and receive pay up to two days early. The Cash App Card lets you spend the deposit at once, and you can also send money to friends from the same balance. The drawback is banking depth. Cash App does not offer a high yield savings account in the same way as SoFi or Varo, and its overdraft style cover is limited to eligible users who meet deposit conditions. Borrow, which offers $20 to $500 for eligible users at a flat fee, is also not available to everyone. Cash App suits people who want speed and simplicity over savings tools.
- Direct deposit up to two days early
- Free Cash App Card
- Easy peer payments
- Optional Borrow for eligible users
- No savings interest in the basic account
- Overdraft cover is limited
- Borrow is not available to all users
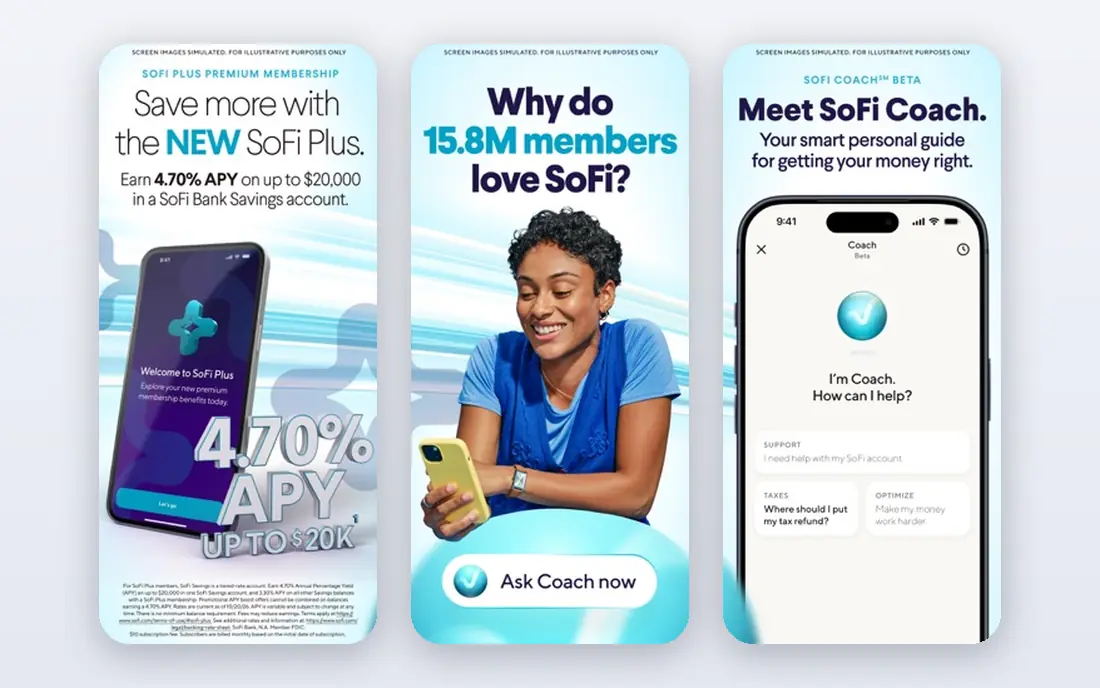
SoFi is the best full bank pick for direct deposit, because it pairs early pay with a real bank account, savings, loans and investing. Checking and savings carry no account fees, and pay can arrive up to two days early. SoFi also offers overdraft cover up to $50 on debit purchases for users who meet deposit conditions. The conditions matter. The best savings rate and overdraft cover usually need direct deposit, with $1,000 or more in deposits per 31 days in some listings. If you already bank with SoFi or you want loans and investing alongside checking, that condition is easy to meet. If you only want early pay, Chime or Cash App may be simpler.
- Checking and savings with no account fees
- Pay up to two days early
- Overdraft cover up to $50
- Loans and investing in one app
- Overdraft cover needs $1,000 or more in direct deposits per 31 days
- Best savings rate needs direct deposit
- No branches
Current combines early pay with a paycheck advance in one account, which makes it useful when a bill falls before payday. Direct deposit can arrive up to two days early, and eligible users can access a Paycheck Advance up to $1,000, with no monthly fee and no credit check. Savings Pods help you split money for rent, bills and goals. The advance limit depends on deposit history, so new users start lower. Instant delivery fees are shown in the app and vary, while standard delivery is slower. Current suits people who want early pay plus a built in advance, and who are happy to keep their direct deposit in one mobile account.
- Pay up to two days early
- Paycheck Advance up to $1,000
- No monthly fee
- Savings Pods for goals
- Advance needs eligible payroll deposits of $200 or more
- Advance limit grows with history
- Instant fee shown in app
Varo Bank is a chartered bank with a mobile first account, which gives it a stronger banking base than some fintech rivals. Direct deposit can arrive up to two days early, there are no monthly fees, and the Save Your Pay feature can move part of each paycheck to savings automatically. That automatic split helps people who struggle to save after payday. Varo Advance offers $20 to $250 for new users, rising to $700 over time with qualifying activity, with fees based on the advance amount. That fee range means a large advance can cost more than it first appears, so check the fee in the app before you confirm. Varo suits savers who want a real bank account with early pay and automatic savings.
- Pay up to two days early
- No monthly fees
- Varo Advance up to $700 over time
- Save Your Pay feature
- Advance starts at $20 to $250 for new users
- Advance fees vary by amount
- No branches
PayPal offers direct deposit for users who want pay to land in a payment account they already use for shopping and sending money. Eligible direct deposits can arrive early, and you can spend the balance online, send it to others or use a PayPal Debit Card for purchases. Setup is simple if you already have a PayPal account. The limit is scope. PayPal is not a full replacement for a bank account for every user, and its banking features, such as savings and overdraft style tools, vary by product and region. It suits freelancers, sellers and online shoppers who already receive money through PayPal and want payroll in the same place.
- Direct deposit into PayPal balance
- Early access for eligible deposits
- Easy online payments
- Debit card option
- Not a full bank account for everyone
- Savings and banking features vary
- Some features need a PayPal Debit Card
Ally Bank is a strong online bank choice for direct deposit, with no monthly fees, a well rated mobile app and early pay for eligible deposits. Its Spending Account can receive pay early, and CoverDraft offers up to $250 in overdraft cover for eligible users. Savings accounts also pair well with direct deposit for automatic transfers. Check the early pay limits. In some listings, up to eight early direct deposits are allowed per statement cycle, and each deposit must be $10,000 or less. That limit will not affect most workers, but it matters for large or frequent deposits. Ally suits people who want a full online bank, not just a payment app.
- Pay up to two days early in many cases
- No monthly fees
- CoverDraft up to $250
- Strong mobile app
- Early deposits are capped per statement cycle in some listings
- No branches
- Savings rate varies
Capital One suits people who want early pay plus the backing of a large bank with branches. Its 360 Checking account has no monthly fee, and eligible direct deposits can arrive up to two days early. A no fee overdraft option is available with opt in and deposit eligibility, which helps if a payment lands before payday. The experience is more traditional than Chime or Current, with a fuller website and branch network in some cities, but also more steps in setup. Savings rates are also lower than some online only banks. Capital One is best if you value a large bank, occasional branch access and early pay in one account.
- Pay up to two days early
- No monthly fee on 360 Checking
- Branches and cafes in some cities
- No fee overdraft option with opt in
- Overdraft cover needs opt in and deposit eligibility
- Savings rate is lower than some online rivals
- Setup is more traditional
Discover Cashback Debit pairs early pay with cash back on debit purchases, which is rare among bank accounts. There is no monthly fee, eligible direct deposits can arrive up to two days early, and the account works well for everyday spending. If you use a debit card for most purchases, the cash back adds a small return on money you would spend anyway. Cash back terms and caps apply, so read the current offer before you count on a fixed return. Discover also has no branches, and it offers fewer advance and savings tools than SoFi or Current. It suits debit card users who want early pay plus a simple reward, without a complex app.
- Pay up to two days early
- No monthly fees
- Cash back on debit purchases
- Strong customer service reputation
- Cash back terms and caps apply
- No branches
- Fewer extra tools than SoFi or Current
How we picked these
We compared official product pages and recent comparison guides, and we kept only accounts that are live in the United States in October 2026 and that clearly offer direct deposit with early pay or a direct deposit feature. We favoured accounts with no monthly fee, clear early pay timing and useful extras, such as savings tools, overdraft cover or advances, and we mixed fintech apps with traditional and online banks. We did not claim hands on testing, and we did not treat an advertised two day figure as a guarantee. We also noted that early pay depends on your employer. If payroll is sent late, or if it is your first deposit, funds may arrive on the scheduled date instead of early. That is why the list stresses setup and conditions, not just the headline timing.
Setting up direct deposit well
Get the right account details
Open the app or website, find the routing and account numbers under direct deposit or move money, and copy them exactly into your payroll form. A single wrong digit can delay pay, so double check the numbers and keep a screenshot of the confirmation. If your employer uses a third party payroll portal, enter the details there as well.
Plan for the first paycheck
Do not plan bills around early pay for your first deposit, because first deposits are the most likely to arrive on time rather than early. Keep a small buffer in the account, and watch the first two pay cycles to learn your actual timing. Once timing is steady, you can plan around it with more confidence.
Use early pay as a tool, not a loan
Early pay moves your own money sooner, which is different from borrowing. If you regularly run out before payday, look at bill dates, automatic savings and spending patterns before adding an advance. Moving a bill date by a few days, or splitting a large bill across pay periods, often helps more than a fee based advance.
Frequently asked questions
What is the best app for direct deposit?
Chime is the simplest early pay pick, SoFi is the best full bank pick, and Current is the best pick if you also want a paycheck advance. The right choice depends on whether you want a bank, a payment app or an advance built in.
What are the best direct deposit apps with no fees?
Chime, Cash App, SoFi, Current, Varo, Ally, Capital One and Discover all offer basic accounts with no monthly fee in their standard forms. Check for other fees, such as ATM fees, advance fees or instant transfer fees, which can still apply.
How early can I get paid with direct deposit?
Most apps in this list offer pay up to two days early, which means funds can arrive up to two days before the scheduled payday when your employer sends payroll early through ACH. It is not a guarantee for every paycheck, and first deposits may arrive on time.
Do I need to switch banks to get early direct deposit?
Not always. Check whether your current bank already offers early pay, because many large banks now do. If it does not, opening a second account for direct deposit is an option, but keep your old account open until the first early deposit lands correctly.
Is early direct deposit safe?
Yes, when it comes from a legitimate bank or fintech account in your name, using the routing and account numbers from the official app. Never share those numbers with an unverified person or site, and only enter them in your employer's official payroll system.
Can I split direct deposit between two accounts?
Many employers allow split direct deposit, so you can send part of your pay to a savings account and part to checking. Check your payroll portal for a split option, and test it with a small amount first if you are unsure.
Sources
See where you really rank - block by block
ProMapRanker scans Google Maps across a grid of your service area. Simple monthly plans from $19, white-label on every plan.
Start freeKeep reading
 zscaler alternatives
Best Zscaler Alternatives in 2026
Looking for zscaler alternatives? We compare 9 SASE and zero trust platforms on architecture, data protection, pricing, and fit for your network and team.
Read → zapier alternatives free
Best Zapier Alternatives Free in 2026
Nine automation tools for zapier alternatives free in 2026, all with genuinely free tiers, plus free plan limits, starting prices and upgrade paths explained.
Read → which platform is best for online reputation
Which Platform Is Best for Online Reputation in 2026
Wondering which platform is best for online reputation? We compare 8 review, listing, and response tools for small and multi-location businesses and agencies.
Read →